


EN
Is Quarterly Net Loss Altering The Investment Case For Carlyle Group Stock?
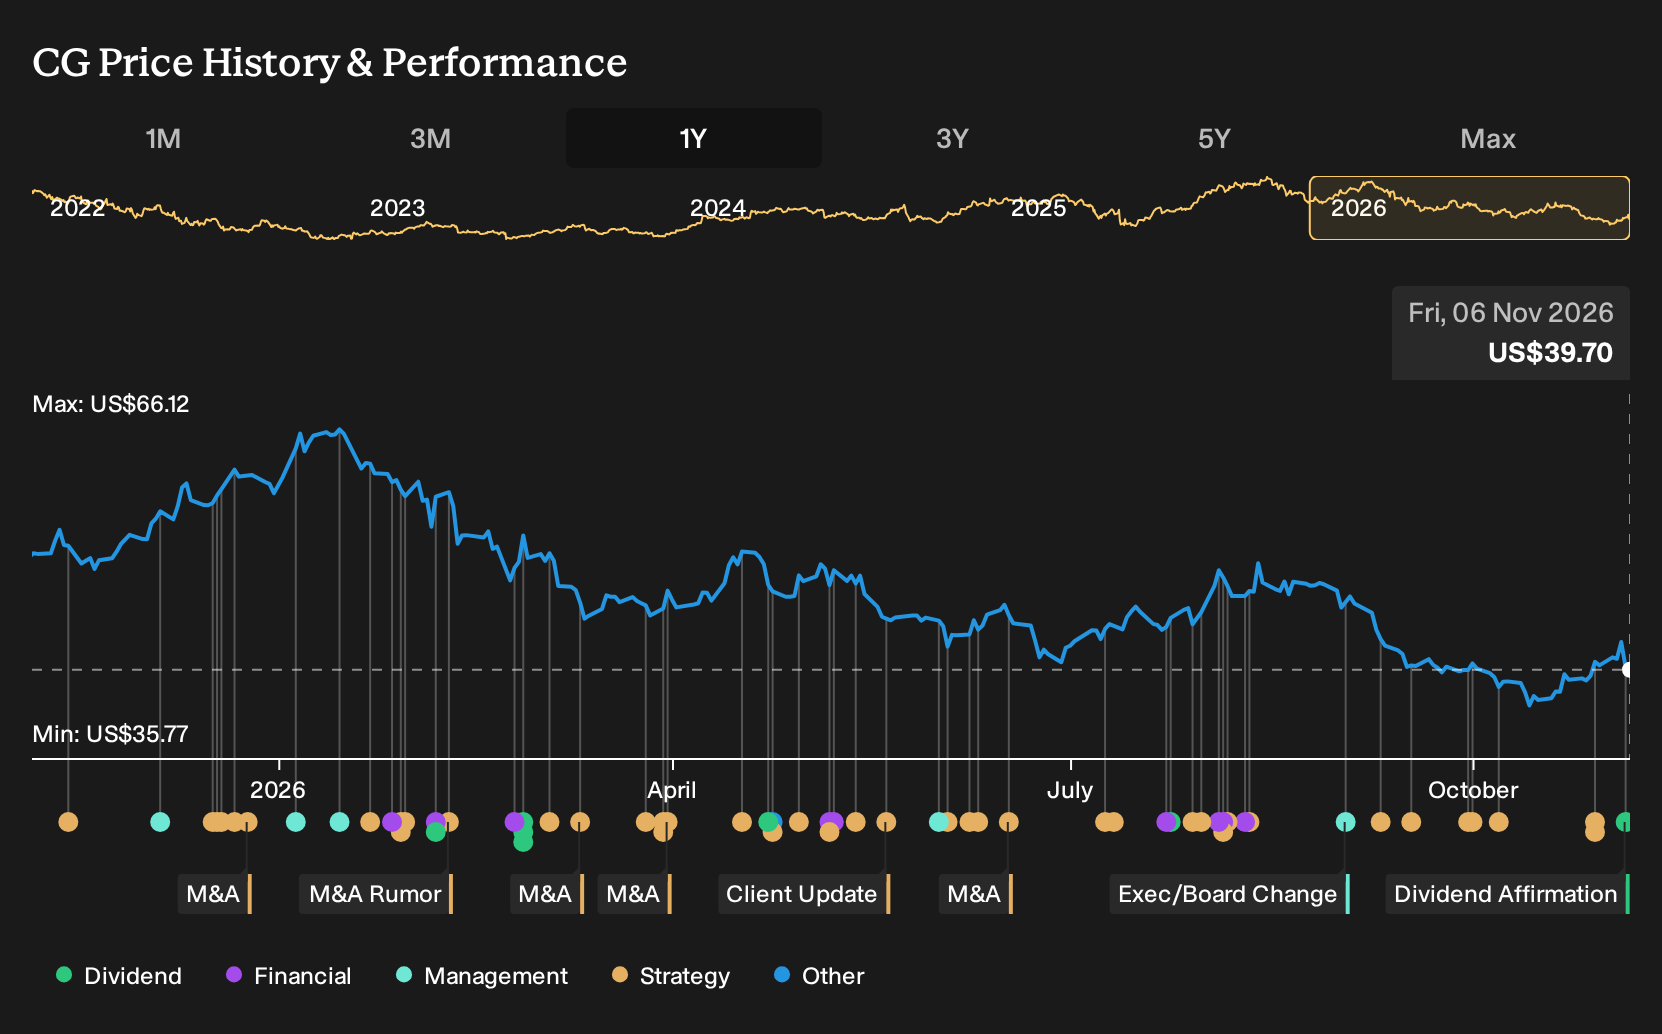
- Carlyle Group reported third quarter 2026 revenue of US$334.1 million with a net loss of US$7.7 million, and a nine month net loss of US$2.8 million alongside a maintained US$0.35 quarterly dividend.
- The return to losses, despite broadly similar quarterly revenue to a year earlier, points to pressure from costs, investment marks or other non fee items weighing on profitability.
- We will now look at how Carlyle Group's renewed net loss affects the earlier investment narrative built around improving operating profitability.
Compare Carlyle Group's renewed loss and maintained dividend with those of other listed asset managers by exploring our curated set of 39 high quality undervalued stocks.
Carlyle Group Investment Narrative Recap
To own Carlyle Group, you need to believe Harvey Schwartz’s operating clean up can still translate into steadier fee earnings and better use of existing funds, even after a quarter that slipped back into a small loss. The recent US$7.7 million loss and sharply weaker nine month earnings keep execution risk front and center rather than changing the basic thesis.
The short term swing factor remains fee related profitability and realization activity, especially given weaker accounting profits and pressure on margins highlighted in platform data. The biggest near term risk is that softer fund management fees or further investment losses extend this volatility and complicate debt coverage and dividend sustainability concerns already flagged for the business.
The reaffirmed US$0.35 quarterly dividend is the announcement that ties most directly to this earnings print. According to galinredo, an investor in the Simply Wall St Community, the appeal in Carlyle Group partly rests on shareholder distributions, with the dividend viewed as income while the operating recovery plays out.
Holding that payout while reporting a nine month net loss of US$2.8 million puts more focus on how quickly fee based earnings and cash generation can support both debt obligations and distributions. For readers treating the dividend as a key catalyst, the combination of weaker accounting profits and already flagged coverage issues means payout resilience now depends heavily on how consistently management executes the fee profitability and AlpInvest growth plan that galinredo describes.
In galinredo’s narrative, Carlyle Group reaches a fair value of US$52.50 if revenue expands at 16.9% a year and the business ultimately earns a 13.0% profit margin, which together support an assumed US$4.10 of normalized distributable earnings per share on a 12.8x P/E multiple.
Uncover how Carlyle Group's fair value indicates a 32% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Some of the most optimistic analysts frame Carlyle Group very differently from the baseline execution worries you have just read. They focus on a potential compounding story, with revenue forecasts around 33.2% annual growth and earnings climbing from US$363.9 million to US$2.4b by 2029. That is a far brighter setup, and these pre earnings forecasts may well be revisited after this latest loss and dividend decision, so it is worth comparing several viewpoints before deciding how the story fits your own expectations.
Explore 3 other Carlyle Group fair value estimates, including one that suggests as much as 182% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Carlyle Group research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Carlyle Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Carlyle Group's overall financial health at a glance.
Looking for more Carlyle Group style investment ideas?
If this Carlyle Group review has sharpened your thinking, use the Simply Wall St Screener to line up a wider watchlist that matches your risk profile and income goals.
- If you want potential upside with some quality filters already applied, scan through our curated set of 39 high quality undervalued stocks that pass both balance sheet and cash flow checks.
- For readers who care most about income resilience, focus on companies in the 7 dividend fortresses that pair payout strength with supporting fundamentals.
- If capital preservation matters more than chasing every rally, narrow your search to the 31 resilient stocks with low risk scores and build a list that leans toward steadier risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com