


EN
Could Cullen/Frost Bankers (CFR) Be 11% Undervalued On Raised 2026 Guidance?
Cullen/Frost Bankers (CFR) raised its full year 2026 net interest income outlook to 5% to 5.5% growth, while reaffirming an expected 10 to 13 basis point margin improvement.
Cullen/Frost Bankers shares trade at $155.23, with the price slipping 0.93% over the last session and 3.16% over the past week, even as the 30 day share price return of 3.32% and year to date share price gain of 21.11% point to positive momentum. Recent buybacks, steady dividends and updated earnings guidance arrive against that backdrop, while the 1 year total shareholder return of 28.58% and 3 year total shareholder return of 81.73% show that long term holders have, so far, been rewarded more than short term traders.
Scan beyond Cullen/Frost Bankers and compare its guidance, dividends and buybacks with a curated 7 dividend fortresses that combine income potential with balance sheet resilience.
Cullen/Frost Bankers has raised its outlook while the share price has eased, leaving a wide gap between the current US$155.23 level and fair value estimates. Is that discount justified or overstated?
Most Popular Narrative: 11% Undervalued
The analyst consensus Narrative on Simply Wall St sees Cullen/Frost Bankers’ fair value at $174.86, compared with the latest $155.23 close. This points to a valuation gap built on detailed revenue, earnings and risk assumptions.
Management’s guidance for 2026, including higher ranges for full year average loan growth of 7% to 8%, net interest income growth of 4.75% to 5.25% and noninterest income growth of 7.5% to 8.5%, along with lower expected expense growth, points to operating leverage that could support future margins and earnings if delivered.
See why 4 investors see Cullen/Frost Bankers as 11% undervalued.
Result: Fair Value of $174.86 (UNDERVALUED)
Still, Cullen/Frost Bankers leans heavily on Texas, and tougher local real estate or energy conditions, combined with rising competition for deposits, could quickly challenge that undervaluation story.
Find out about the key risks to this Cullen/Frost Bankers narrative.
Another View: Cullen/Frost Bankers Looks Priced Richly On Earnings
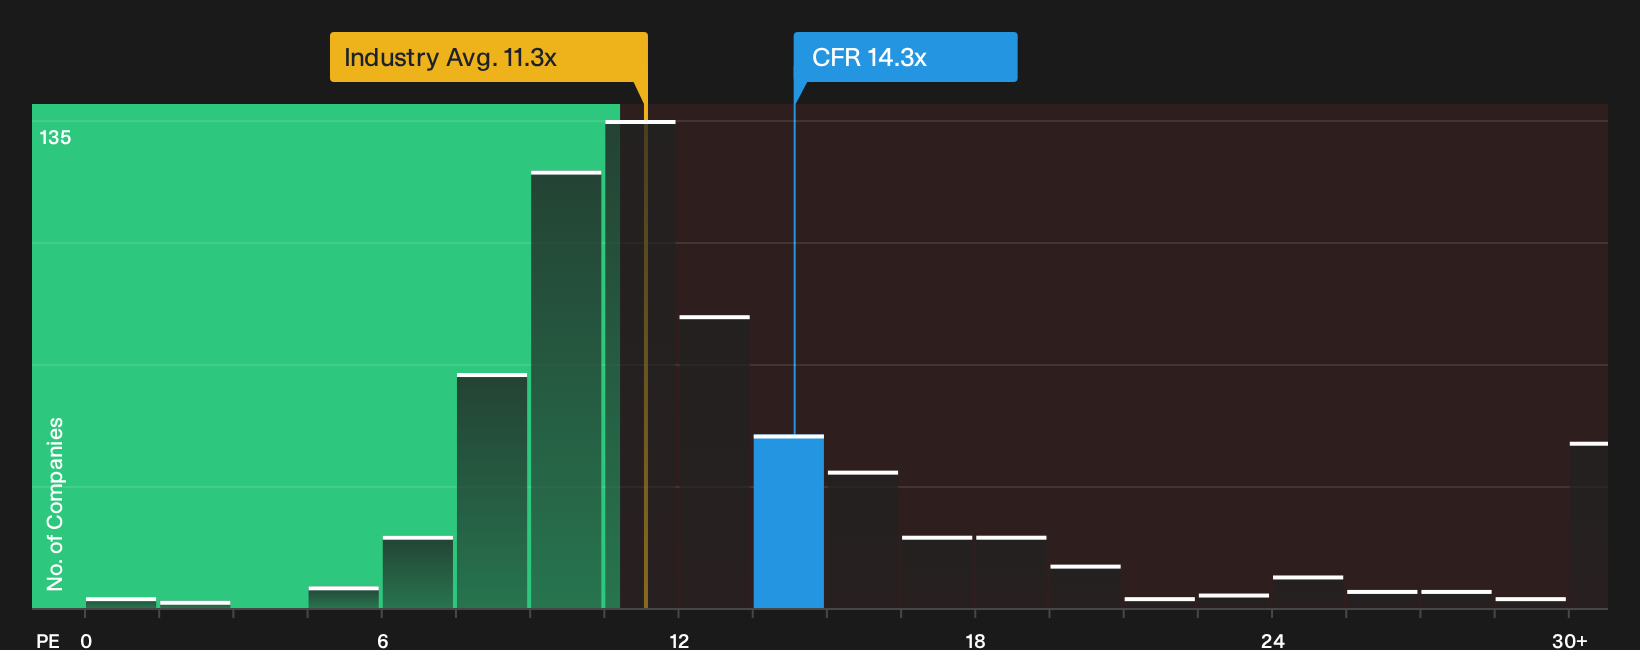
On the flip side of that 11% implied discount, Cullen/Frost Bankers trades on a P/E of 14.3x, compared with 11.3x for the wider US Banks group and 11.2x for close peers. The fair ratio sits at 11.9x. That richer multiple suggests less margin for error if the story wobbles.
For investors weighing what that premium P/E might mean if sentiment or forecasts change, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If you believe Cullen/Frost Bankers could move in either direction given this mix of signals, consider acting while sentiment is still developing and evaluate the potential upsides for yourself with 3 key rewards
Looking for more investment ideas beyond Cullen/Frost Bankers?
If this Cullen/Frost Bankers story has you thinking about what else might be hiding in plain sight, now is the moment to widen your net before the next move passes you.
- Target resilient balance sheets first and stress test your portfolio against shocks by scanning a list of solid balance sheet and fundamentals (25 results) that filters for financial strength.
- Spot potential mispricings early by reviewing a curated 39 high quality undervalued stocks that blends quality fundamentals with room for a re rating.
- Identify income ideas with staying power by checking a focused 7 dividend fortresses built around businesses that pair yield with staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com