


EN
Beacon Financial (BBT) Stock Looks Undervalued As Earnings Support Its Price
Beacon Financial has delivered a solid share price return over the past year, which naturally puts the spotlight on what investors are paying for its earnings today. With the stock moving around in recent weeks, the question is how well that price lines up with the profit engine underneath the business.
- The share price has risen 22.1% over the past year, so anyone looking at Beacon Financial now is effectively asking whether that move still makes sense when set against its earnings power.
- The company’s value story rests heavily on how efficiently it can turn its banking footprint into consistent profit margins and cash generation, which can support or limit what investors are prepared to pay for each dollar of earnings.
- Your read on Beacon Financial is one view; the desks covering it have another. See what analysts think Beacon Financial's shares could be worth.
The stock’s next move may depend on whether Beacon Financial’s current price is well supported by the earnings it is generating today.
If you want to test the same earnings question that Beacon Financial raises across a wider field, start by scanning 39 high quality undervalued stocks.
Does Beacon Financial Look Undervalued on Earnings?
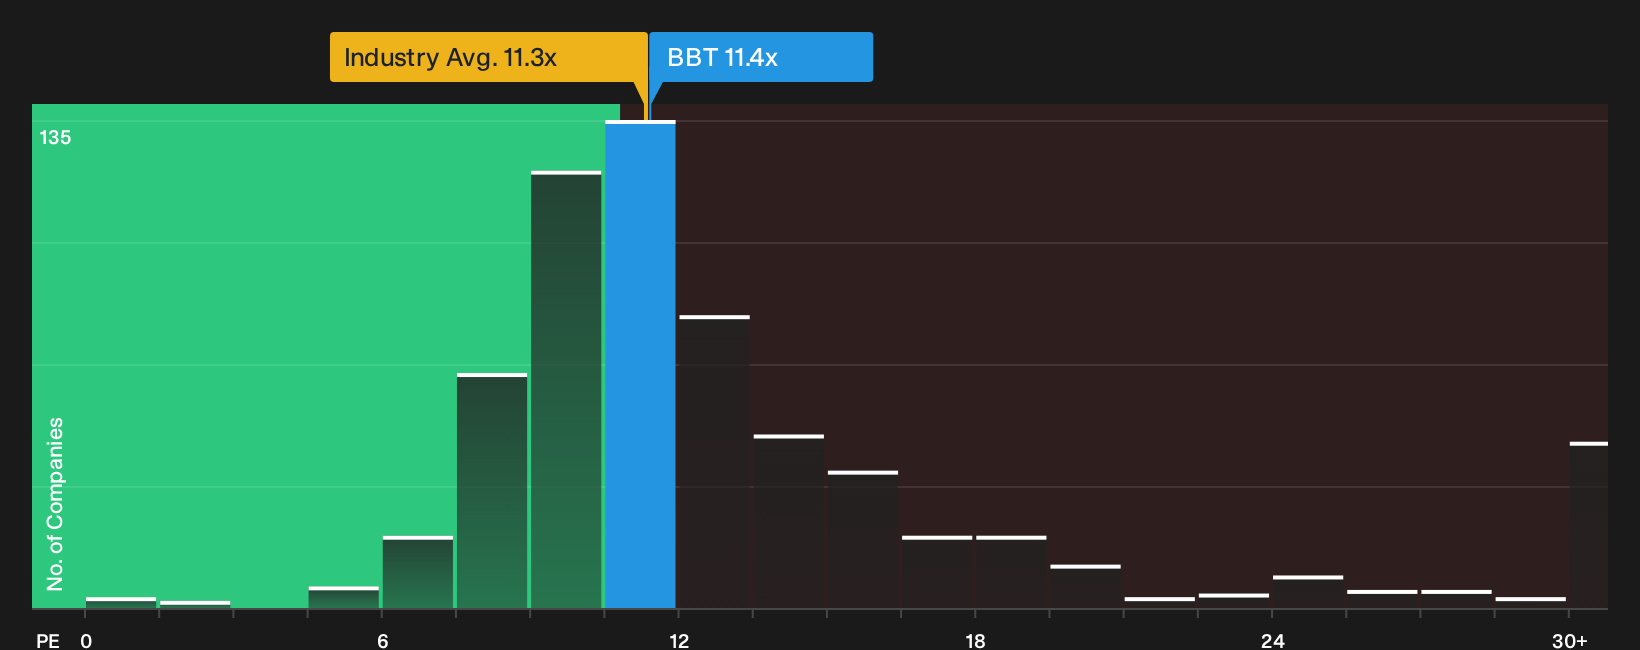
The P/E ratio suits Beacon Financial because earnings remain the core yardstick investors use to judge a bank’s price tag. On this measure, the stock trades on a P/E of 11.4x, which is close to the wider banks industry average of 11.3x. That puts the current tag in the same broad valuation zone as many sector peers, rather than at an obvious outlier level.
There is another lens that adjusts for Beacon Financial’s own profitability profile, growth expectations and risk. On that fair-value framework, the shares change hands below the multiple implied by those fundamentals, which points to the stock screening as undervalued on earnings. For anyone weighing an entry or adding to an existing position, the gap between the current P/E and that modelled fair level is where the valuation debate really sits. Explore the numbers behind Beacon Financial's P/E valuation.
The Beacon Financial Narrative: What Would Justify Today's Price?
Beacon Financial’s valuation puzzle only really comes into focus once you spell out the stories that could justify a higher or lower share price. This is where Simply Wall St Narratives on the Community page come in, as they map what would need to happen to Beacon Financial's future earnings, margins and growth for the stock to be worth materially more or less than today. Rather than a single valuation number, each scenario lays out the key assumptions behind its view of fair pricing so you can track how those expectations stack up against Beacon Financial's actual results over time.
One of the top narratives on Beacon Financial: 9% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Realization of merger cost synergies, including further headcount reductions and vendor consolidation after the core conversion, should reduce operating expenses toward the targeted quarterly run rate..."
Discover why this Narrative puts Beacon Financial at 9% undervalued.
One more Beacon Financial check before you stop at the share price
Before you treat Beacon Financial’s valuation as the full story, it is worth asking how the people steering the bank are rewarded and whether those incentives line up with your own. See who runs Beacon Financial and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com