


EN
CoreWeave (CRWV) Stock Looks Undervalued Against Its Current Sales Base
CoreWeave has seen its share price slide sharply over the past year, raising a pointed question for anyone watching the stock. Do the company’s current sales make today’s market value look sensible, or has the price moved out of line with what the business is actually generating in revenue?
- The share price has fallen 56.1% over the past year. This puts fresh focus on whether the drop simply reflects sentiment or says something deeper about how its sales are being valued.
- Recent headlines around data center regulation in Texas, expanded security collaboration with CrowdStrike and questions over debt funding mean investors are weighing how CoreWeave’s growth plans and capital needs might shape the sales multiple the market is willing to pay.
- Your read on CoreWeave is one view; the desks covering it have another. See what analysts think CoreWeave's shares could be worth.
The issue now is whether CoreWeave’s current share price is meaningfully supported by its sales when measured against the Fair Ratio benchmark.
Given the pressure on CoreWeave and other AI infrastructure stocks, it can help to compare how the market is pricing similar themes across 53 AI infrastructure stocks.
Does CoreWeave Look Undervalued on Sales?
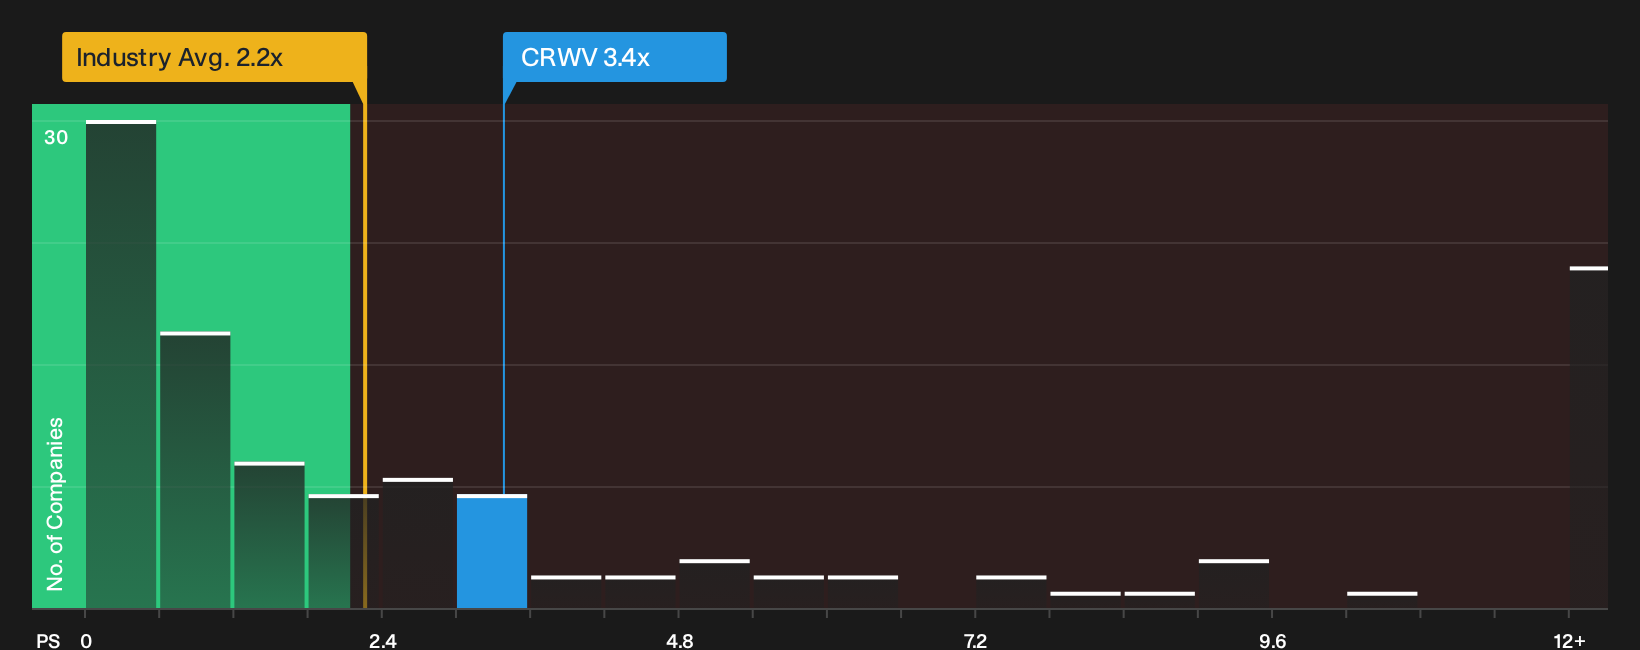
P/S is a useful lens for CoreWeave because investors are currently focused more on revenue traction than profits. The stock trades on a P/S ratio of 3.4x, which sits above the IT sector average of 2.2x but below the peer group around 10.0x. That mix indicates that the market prices CoreWeave’s sales at a premium to the broader industry, yet at a clear discount to closer AI infrastructure comparables.
The Fair Ratio, which adjusts the P/S benchmark for CoreWeave’s specific growth profile, margins, size and risk, points to the current 3.4x multiple as undervalued. Despite renewed concern over debt funding and data center regulation flagged in recent reports from Texas, the market is still assigning a lower P/S than this tailored yardstick implies, leaving the revenue base priced more conservatively than the framework suggests. Explore the numbers behind CoreWeave's P/S valuation.
The CoreWeave Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where that P/S puzzle for CoreWeave leaves off. They spell out which combinations of future growth, profitability and earnings power would need to play out for the stock to be valued meaningfully higher or lower than it is today. Each scenario ties a fair value estimate to a particular mix of potential catalysts and risks so you can watch over time which version of CoreWeave's story is gaining traction.
Bulls and bears looking at CoreWeave right now are arguing over whether leverage is a feature or a bug.
Bull case: 34% undervalued
According to WIn2026, an investor in the Simply Wall St Community, the hardware heavy model can still work in CoreWeave’s favour.
"Every dollar of operational cash flow must be recycled immediately into the next generation of NVDA GPUs and optical networking to remain competitive..."
Discover why this Narrative puts CoreWeave at 34% undervalued.
Bear case: 15% overvalued
The bearish analyst Narrative on Simply Wall St argues that CoreWeave’s balance sheet is where the real pressure shows up.
"Bearish analysts expect CoreWeave to struggle under very high capital intensity, widened net losses and rising unsecured bond yields around 15%..."
Explore why this Narrative puts CoreWeave at 15% overvalued.
One more CoreWeave angle worth checking before you move on
Valuation numbers only tell part of CoreWeave's story, because the people setting priorities and the way they are rewarded can heavily influence how this business is run over time. See who runs CoreWeave and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com