


EN
Tsakos Energy Navigation (TEN) Doubles Dividend As Fair Value Debate Comes Into View
Dividend move puts Tsakos Energy Navigation on income investors’ radar
Tsakos Energy Navigation (TEN) has put income policy in focus after its recent strategy meeting. Management plans a US$1.00 per share semi-annual dividend in January 2027, which is double the 2026 first semi-annual payout.
The dividend decision comes after a volatile period for Tsakos Energy Navigation’s stock. The share price is down 16.69% over the last week and 12.72% over the past month, while still showing a 17.10% 90-day share price return and a 104.93% year-to-date share price gain, along with a 5-year total shareholder return of 571.83%.
Scan beyond Tsakos Energy Navigation and compare this dividend move with other income ideas in our hand picked 7 dividend fortresses.
After a sharp pullback in Tsakos Energy Navigation following a strong run and with a richer dividend path now on the table, do you press the buy button today or wait for a cheaper entry before income kicks in?
Most Popular Narrative: 28% Undervalued
The analyst consensus Narrative on Simply Wall St points to a fair value of $62.50 for Tsakos Energy Navigation compared with the last close at $44.86, which frames the recent dividend talk against a stock that this model sees as undervalued using a 9.236% discount rate.
Tsakos Energy Navigation is committing around $3.1 to $3.2b to a 20 to 26 vessel newbuilding pipeline while also adding modern secondhand ships. This increases future capital employed and can lift revenue and earnings expectations well beyond what current contracted cash flows support.
See why 14 investors see Tsakos Energy Navigation as 28% undervalued.
Result: Fair Value of $62.50 (UNDERVALUED)
Still, Tsakos Energy Navigation remains exposed if tanker day rates cool faster than analysts model or if its large newbuilding program strains cash flows and the flexibility of its balance sheet.
Find out about the key risks to this Tsakos Energy Navigation narrative.
Another View: Cash Flows Paint A Tougher Picture For Tsakos Energy Navigation
There is a clear split in signals. While the analyst narrative sees Tsakos Energy Navigation as undervalued against a $62.50 fair value, the Simply Wall St DCF model points to a different conclusion, with an estimate of future cash flow value at $37.93 versus a $44.86 share price today.
This gap suggests the current market quote prices in stronger long term cash generation than that cash flow model supports. It leaves you asking a simple question: Is the analyst target too generous, or is the DCF too cautious on what Tsakos Energy Navigation can earn through a full tanker cycle?
Look into how the SWS DCF model arrives at its fair value.
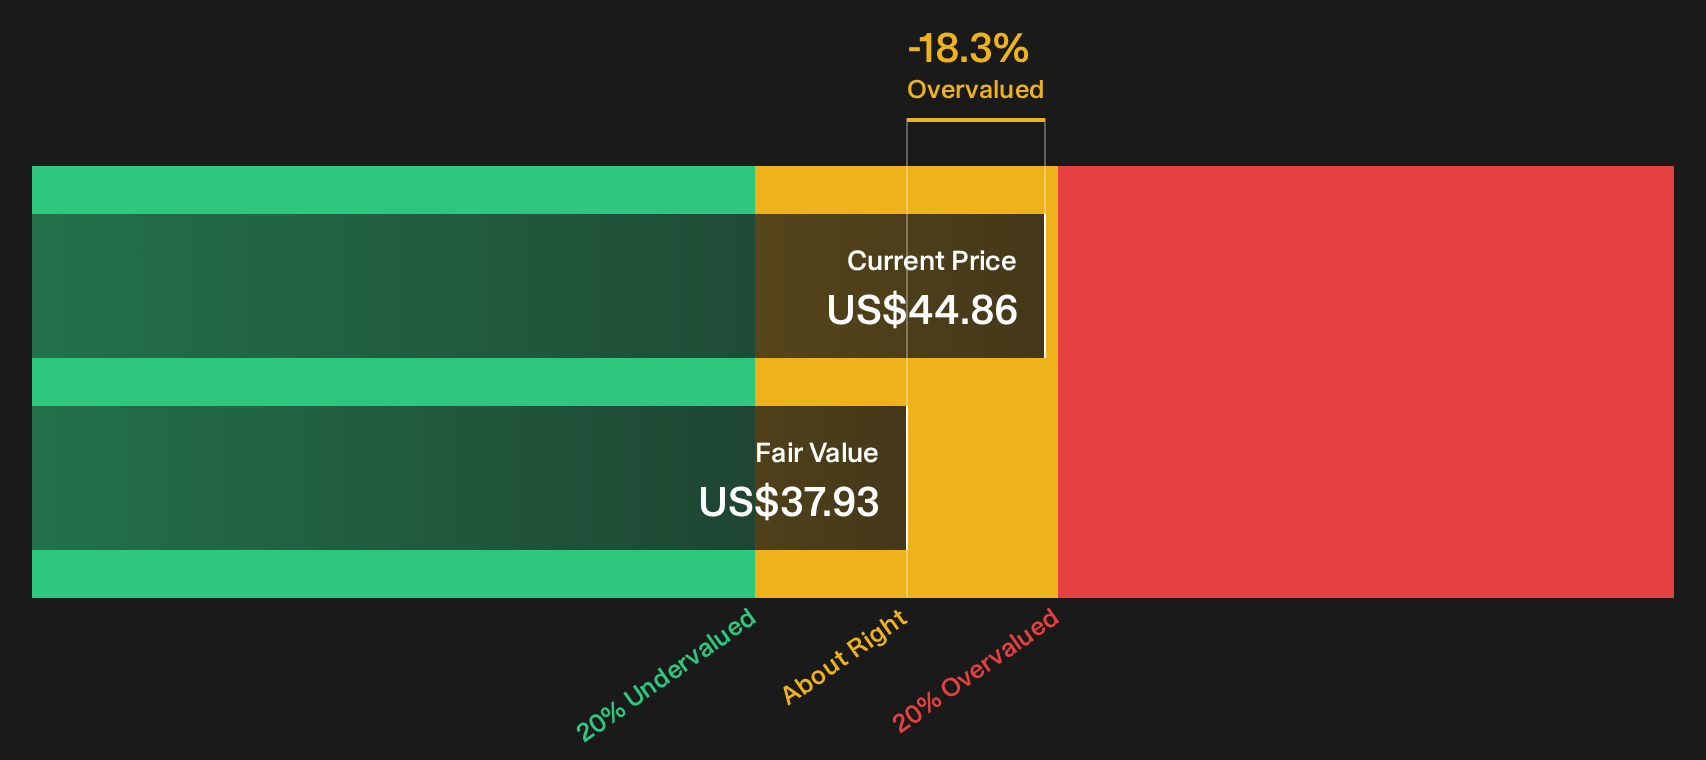
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tsakos Energy Navigation for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Tsakos Energy Navigation can either sharpen your thinking or paralyse it, so move quickly to the data, weigh both sides, and use the 3 key rewards and 4 important warning signs to pressure test your own conclusion.
Looking for more investment ideas beyond Tsakos Energy Navigation?
If Tsakos Energy Navigation has your attention, do not stop here. Broader context from other opportunities can sharpen your decisions and help you avoid tunnel vision.
- Scan for quality at a discount and shortlist companies that combine strong fundamentals with attractive pricing by using the 39 high quality undervalued stocks.
- Prioritise resilience and focus on businesses with sturdier financial footing by running a filter through the list of solid balance sheet and fundamentals (25 results).
- Hunt for overlooked potential and surface under-followed opportunities with stronger metrics using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com