


EN
Can Garmin (GRMN) Justify Its Valuation On Strong Q3 Earnings And Higher 2026 Guidance?
Garmin (GRMN) has been in focus after a strong third quarter, with higher year-over-year sales and net income, as well as a higher full-year 2026 revenue outlook that caught investors’ attention.
Garmin’s latest earnings beat and raised 2026 revenue outlook have come alongside a strong run in the shares, with a year-to-date share price return of 41.06% and a 1-year total shareholder return of 43.19% pointing to momentum that has been building rather than fading, despite a softer 90-day share price move that fell 7.78% from prior highs.
Scan Garmin’s momentum against a curated group of peers showing similar strength using our 39 high quality undervalued stocks for ideas that combine quality fundamentals with price pressure that has not fully caught up yet.
After Garmin’s sharp run and modest pullback, the choice is simple but not easy. Investors can either lean into the current price or wait for a cleaner entry as the valuation picture comes into focus next.
Most Popular Narrative: 5% Undervalued
Garmin’s last close at $285.57 sits below the analyst consensus Narrative fair value of $302, which points to modest upside according to the analyst consensus Narrative on Simply Wall St that ties together price targets, cash flow forecasts, and margin assumptions.
The launch of the Garmin Connect+ premium service, which offers AI based health and fitness insights, is described as a potential driver of subscription based revenue and an improvement in overall margins through higher margin services. The acquisitions of TrainingPeaks and TrainHeroic, which add endurance and strength training platforms around Garmin wearables, are presented as developments that could deepen the service ecosystem and create more recurring revenue streams that can support gross margin and operating margin over time.
See why 52 investors see Garmin as 5% undervalued.
Result: Fair Value of $302 (UNDERVALUED)
Still, the narrative can change quickly if Outdoor weakness persists or if higher memory costs squeeze Garmin’s margins more than analysts currently include in their models.
Find out about the key risks to this Garmin narrative.
Another View: Garmin’s Rich P/E Tells A Different Story
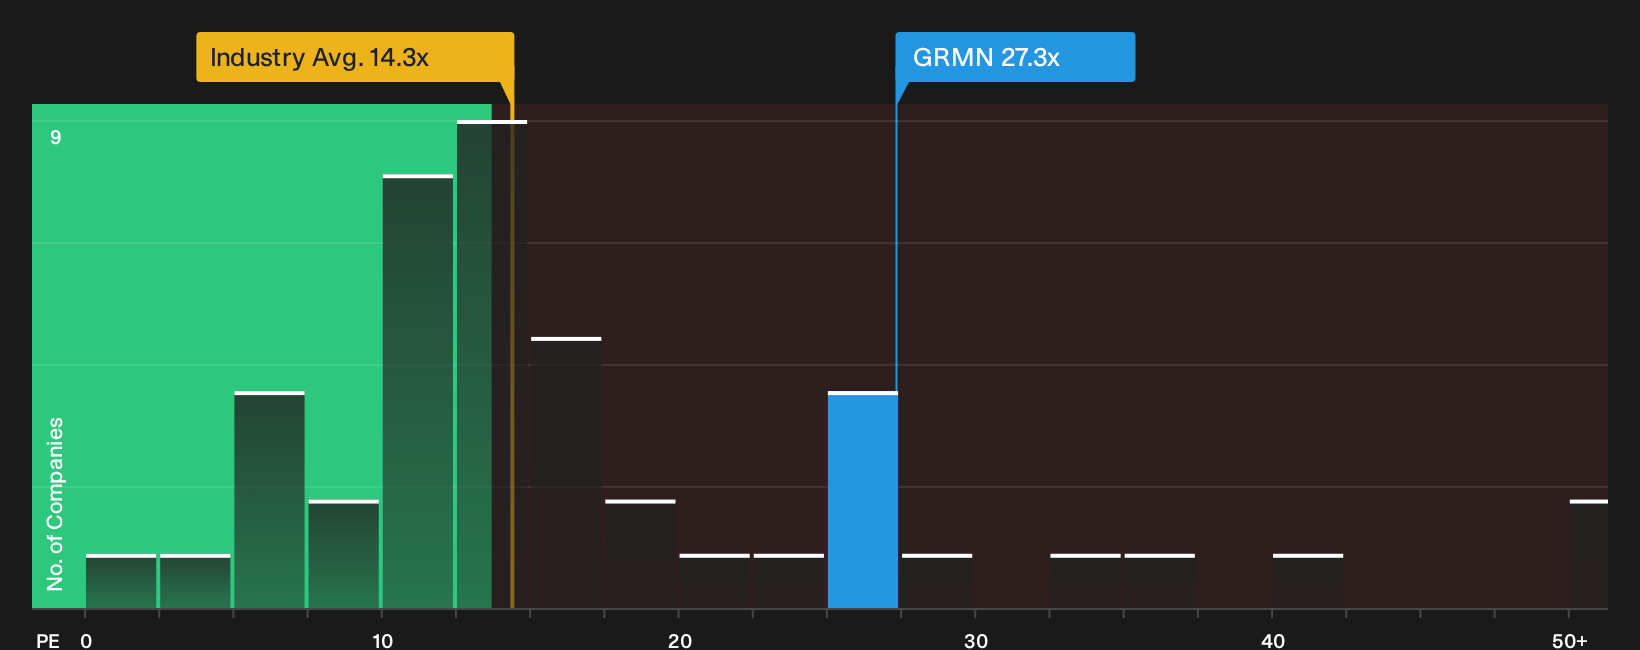
Garmin may look modestly undervalued on analyst fair value at $302, yet the current P/E of 27.3x paints a fuller picture. That multiple sits above both the US Consumer Durables industry on 14.3x and a fair ratio of 25.5x, which points to a premium that leaves less room for error if growth cools or sentiment shifts.
For investors weighing that premium against the quality of the business, the numbers raise a simple question. Is this a margin of safety, or a margin of optimism that needs constant execution to hold up, especially after such a strong 1-year total return?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Seen enough to sense that sentiment on Garmin is finely balanced between opportunity and concern, and want your own verdict before momentum shifts again? Start by weighing the 4 key rewards and 1 important warning sign.
Looking for more Garmin-sized opportunities?
If Garmin has sharpened your focus, do not stop here. Expand your watchlist with fresh ideas that match your goals, risk tolerance, and income needs.
- Target rock-solid businesses that can handle shocks by filtering for a 31 resilient stocks with low risk scores that may help you sleep better at night.
- Pursue quality at a sensible price by scanning a 39 high quality undervalued stocks where fundamentals and valuation both work in your favor.
- Boost potential cash flow from your portfolio by zeroing in on a 7 dividend fortresses that concentrates on higher yielding opportunities.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com