


EN
Lower Earnings Guidance Might Change The Case For Investing In Choice Hotels Stock (CHH)
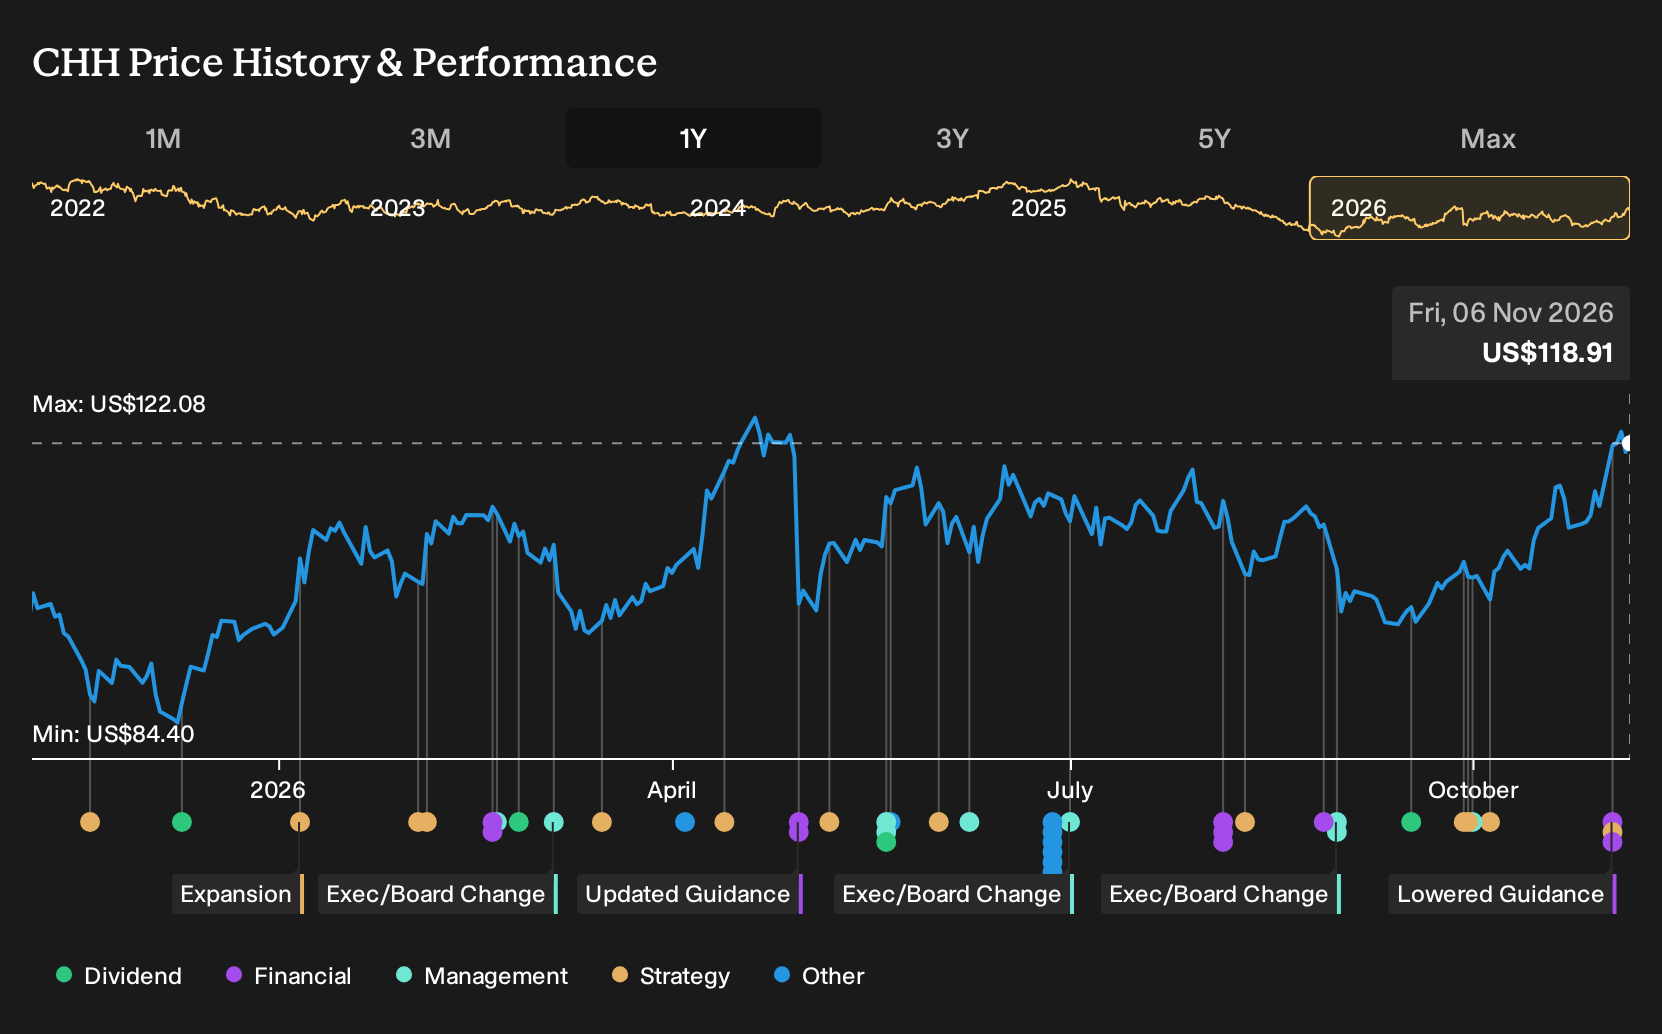
- Choice Hotels International reported third quarter 2026 results that showed much lower net income and EPS year over year, issued reduced full year 2026 net income and earnings guidance, and recorded an impairment of long lived assets against a backdrop of higher marketing and reservation system expenses.
- The updated outlook suggests Choice Hotels International is placing greater emphasis on spending for franchisee facing tools and guest delivery capabilities, which pressures near term profitability but may reshape how efficiently its hotel system attracts and serves travelers.
- We will now look at how Choice Hotels International's investment narrative is affected by the lower earnings guidance tied to higher expenses.
Choice Hotels International Investment Narrative Recap
For a shareholder in Choice Hotels International, the core belief is that a fee heavy, franchise led model can support earnings while technology and brand investments keep franchisees competitive. The lowered 2026 net income guidance to US$178 million to US$185 million, with EPS of US$3.92 to US$4.07, puts the near term focus squarely on whether these higher marketing and reservation system costs start to ease pressure on margins.
The analyst consensus Narrative on Simply Wall St leans on catalysts such as portfolio mix, tech tools and asset light capital recycling. The sharp cut from the prior net income outlook of US$230 million to US$241 million makes the next key catalyst more about closing the U.S. RevPAR gap and demonstrating that these added expenses do not entrench weaker profitability, which remains the major risk highlighted in the narrative.
The most relevant announcement is the third quarter 2026 earnings release. Revenue for the quarter was US$458.33 million, with net income of US$57.91 million and diluted EPS from continuing operations of US$1.28. For the first nine months of 2026, revenue was US$1,239.67 million, while net income reached US$142.55 million.
Those figures sit alongside a US$6.04 million impairment of long lived assets in the third quarter and full year impairment guidance of US$6 million. When these are lined up against the risk that debt is not well covered by operating cash flow and that RevPAR already trails benchmarks, execution on fee growth, digital tools and the extended stay pipeline becomes central to whether the existing catalysts in the analyst consensus Narrative on Simply Wall St remain credible.
Choice Hotels International's outlook anticipates US$1.9b in revenue and US$404.4 million in earnings by 2029. This is based on an assumed 22.9% annual revenue growth rate and an earnings increase of about US$77.6 million from current earnings of US$326.8 million.
Uncover why Choice Hotels International's fair value indicates a 4% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One bullish twist on Choice Hotels International focused on the asset light shift as a strong earnings catalyst. The most optimistic analysts were previously pencilling in revenue of about US$2.1b and earnings of roughly US$431.5 million by 2029, far above consensus. You can now ask whether the latest guidance cut bends those upbeat stories or completely rewrites them.
Explore another Choice Hotels International fair value estimate, including one that suggests it could be worth as much as $114.60.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Choice Hotels International research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Choice Hotels International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Choice Hotels International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Choice Hotels International?
If the latest update from Choice Hotels International has you reassessing where risk and reward line up best, it can help to widen the lens and compare it with other businesses that match your preferred profile on quality, balance sheet strength, and income potential.
- For investors who care most about resilient finances and staying power, start with a 31 resilient stocks with low risk scores that score well on both stability and downside protection.
- If reliable balance sheets matter more than headline stories, scan a list of solid balance sheet and fundamentals (25 results) that pair prudent funding with consistent fundamentals.
- For those who want income to do more of the heavy lifting, focus on 7 dividend fortresses that aim to combine yield with durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com