


EN
What Dine Brands Global Holders Bought Into
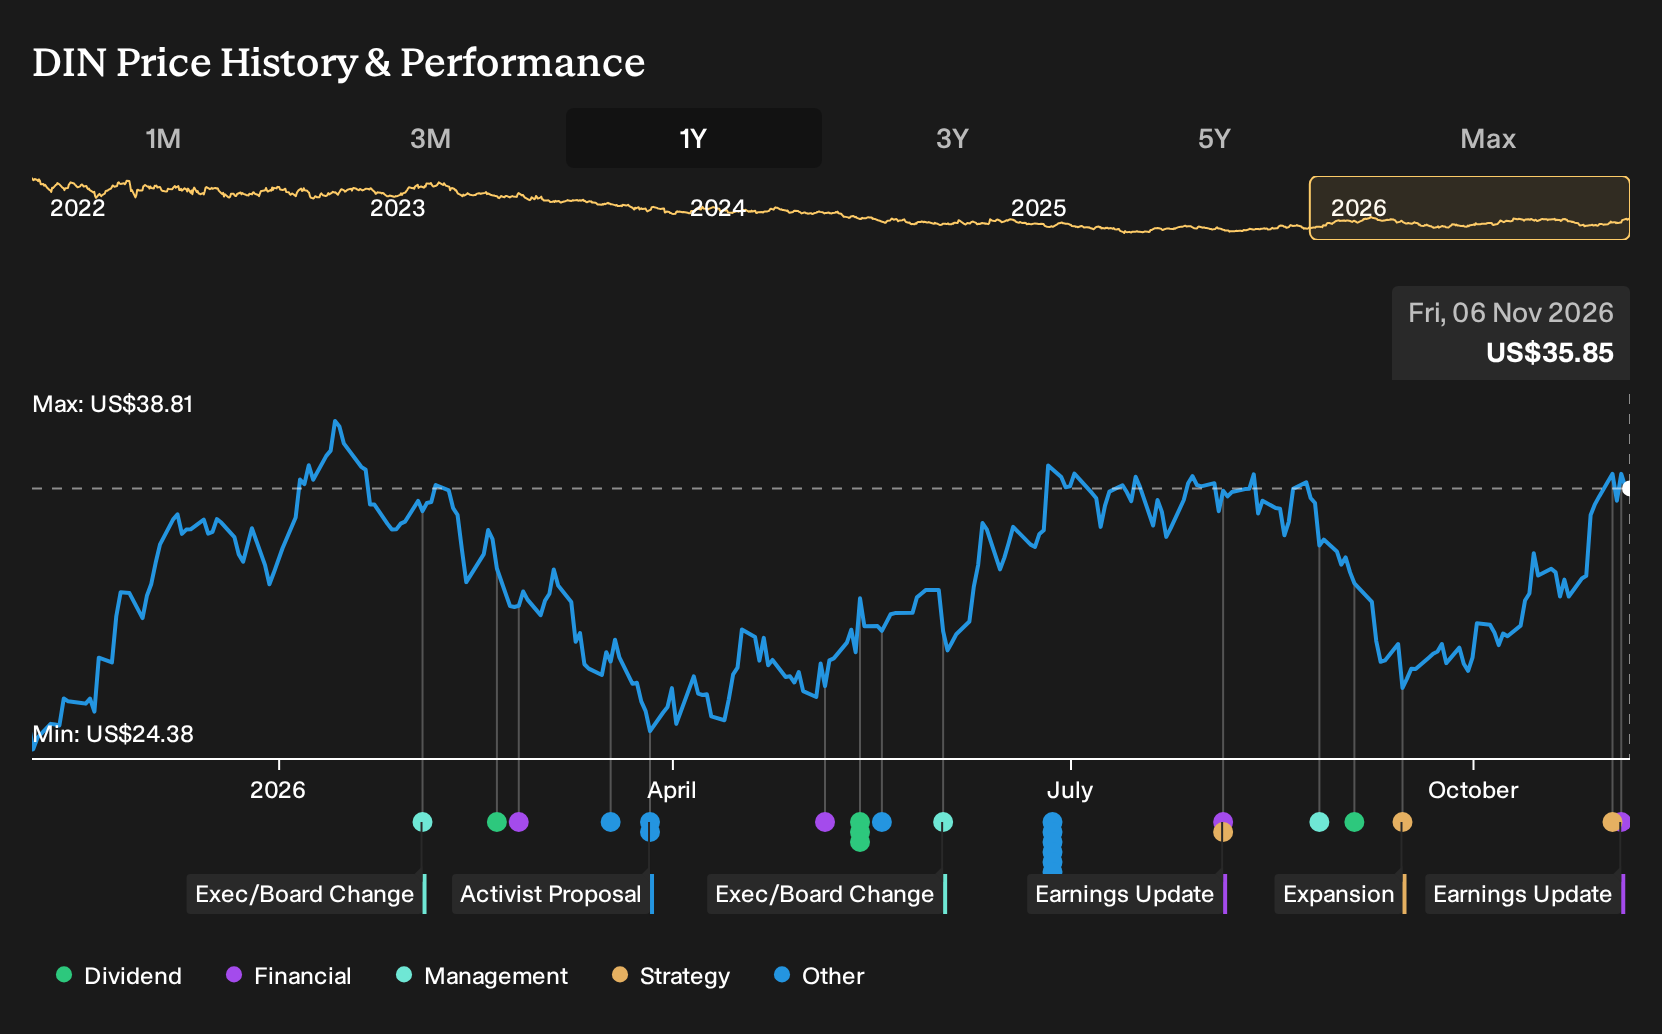
At first glance, Dine Brands Global did not look set up for an easy ride, with same-store sales declines, pressured franchisees, rising costs, and falling net margin already on record when the clock started in November 2025. For Dine Brands Global shareholders, the return over the past year was 44.2%, including dividends. If you had been weighing those worries back then, what did you really need to focus on to decide whether to stay out or step in?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made Dine Brands Global harder to judge, start where the gap is still open and scan 39 high quality undervalued stocks.
The Two Stories Investors Had To Choose Between On Dine Brands Global
The shares cost US$24.38 at the start of the period, which put Dine Brands Global between two sharply different stories about where Applebee’s and IHOP might be heading.
On the optimistic side, one narrative described rapid conversions, remodels, and technology-driven loyalty programs supporting higher sales and net margins, with Fair Value estimated at US$28.15. That view relied on assumptions that digital offers, expanding off-premise sales, and automation would support higher-margin revenue.
The cautious view put Fair Value at US$21. It emphasized pressure from shifting consumer tastes, rising labor and real estate costs, and the risk that dependence on Applebee’s and IHOP would weigh on franchise revenue and earnings.
What The Results Put To The Test For Dine Brands Global
The most concrete shift was operational. Dine Brands Global bought 12 Applebee’s restaurants, which leaned toward the optimistic story of conversions and company influence over formats. At the same time, Q3 2026 revenue reached US$248.9 million against US$216.1 million a year earlier, while net income slipped to US$4.5 million and margin narrowed to 1.8%. The period cut both ways.
The key lesson is simple. When a thesis leans on better profitability, it is important to track net margin alongside any expansion moves and acquisitions rather than only watching headline sales growth.
What Dine Brands Global's Price Already Bakes In
Dine Brands Global now trades at US$35.85, with this cautious Narrative’s Fair Value sitting below that quote based on its own assumptions. The bearish analyst Narrative on Simply Wall St frames today’s valuation as a test of whether remodels, dual branding and value menus can translate into durable economics for franchisees.
Anyone paying today’s price is effectively betting that dual-brand Applebee’s IHOP locations and a heavier off-premise mix will support healthier long term margins. The key question is how the risk of higher construction costs, commodity inflation and remodel spending weighs on that assumption according to this Narrative.
"Although dual-brand Applebee's IHOP conversions are currently delivering higher sales and margin flow through on the incremental revenue, the modeled 900 unit opportunity over about 10 years relies on sustained franchise appetite and capital. These could be constrained if recent construction related closures and the higher cost to add the second brand weigh on unit level returns, which would cap the expected uplift in systemwide sales and royalties."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
How Could You Get There Earlier?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 31% below our estimate - targets higher cost gold production while managing reserve life and political risks.
- Company 2 - 39% below our estimate - expands multidisciplinary consulting as clients navigate complex technical and regulatory challenges.
- Company 3 - 19% below our estimate - leans on custom security hardware and unified software to strengthen network customer retention.
Those are three of them. See every one of the 25 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com