


EN
Insmed Stock Has The Bull Case Changed After Raised Revenue Guidance
- Insmed reported a third quarter 2026 net loss of US$100.32 million and a nine month loss of US$277.12 million, with basic and diluted loss per share from continuing operations of US$0.46 for the quarter and US$1.28 for the nine month period.
- The company also raised 2026 revenue guidance for its key respiratory products, lifting the BRINSUPRI range to US$1.35b to US$1.4b and ARIKAYCE to US$460 million to US$470 million, which reflects management's stated confidence in demand for the current portfolio.
- Investors may now evaluate how Insmed's investment narrative is influenced by the narrower quarterly loss and higher BRINSUPRI revenue guidance.
Scan how Insmed’s mix of ongoing losses and higher product guidance compares across the sector by running your own check against our hand picked 35 healthcare AI stocks.
Insmed Investment Narrative Recap
To own Insmed, you have to believe the respiratory franchise can eventually offset sizeable ongoing losses and turn into a self funding business. The narrower third quarter loss and higher 2026 BRINSUPRI and ARIKAYCE guidance point to a company leaning harder on its commercial base while it continues to invest. The key short term catalyst is progress on expanding use of these therapies into larger patient pools.
The biggest risk right now is that ex US growth and comorbid COPD or asthma bronchiectasis adoption remain slower than the analyst consensus Narrative on Simply Wall St assumes. If that happens, revenue may not scale fast enough against R&D and commercial spending, making the current loss profile harder to improve on the timelines some investors might be working with.
The raised 2026 BRINSUPRI revenue guidance to US$1.35b to US$1.4b is the headline shift that matters most for this earnings update. It connects directly to the core thesis that the U.S. bronchiectasis category can support a large, durable product. For anyone tracking catalysts, this guidance becomes a new reference point for execution on patient growth and adherence.
The same update nudged ARIKAYCE guidance to US$460 million to US$470 million, which ties into the planned broader use in MAC lung disease and the existing commercial base. Investors watching the January 28, 2027 Priority Review decision will likely use this year’s revenue range as a yardstick for how much additional upside an expanded label could add if approved.
Insmed's narrative projects US$4.4b revenue and US$1.2b earnings by 2029. This rests on analysts assuming 56.6% yearly revenue growth and earnings rising by about US$2.1b from current earnings of a US$875.3 million loss.
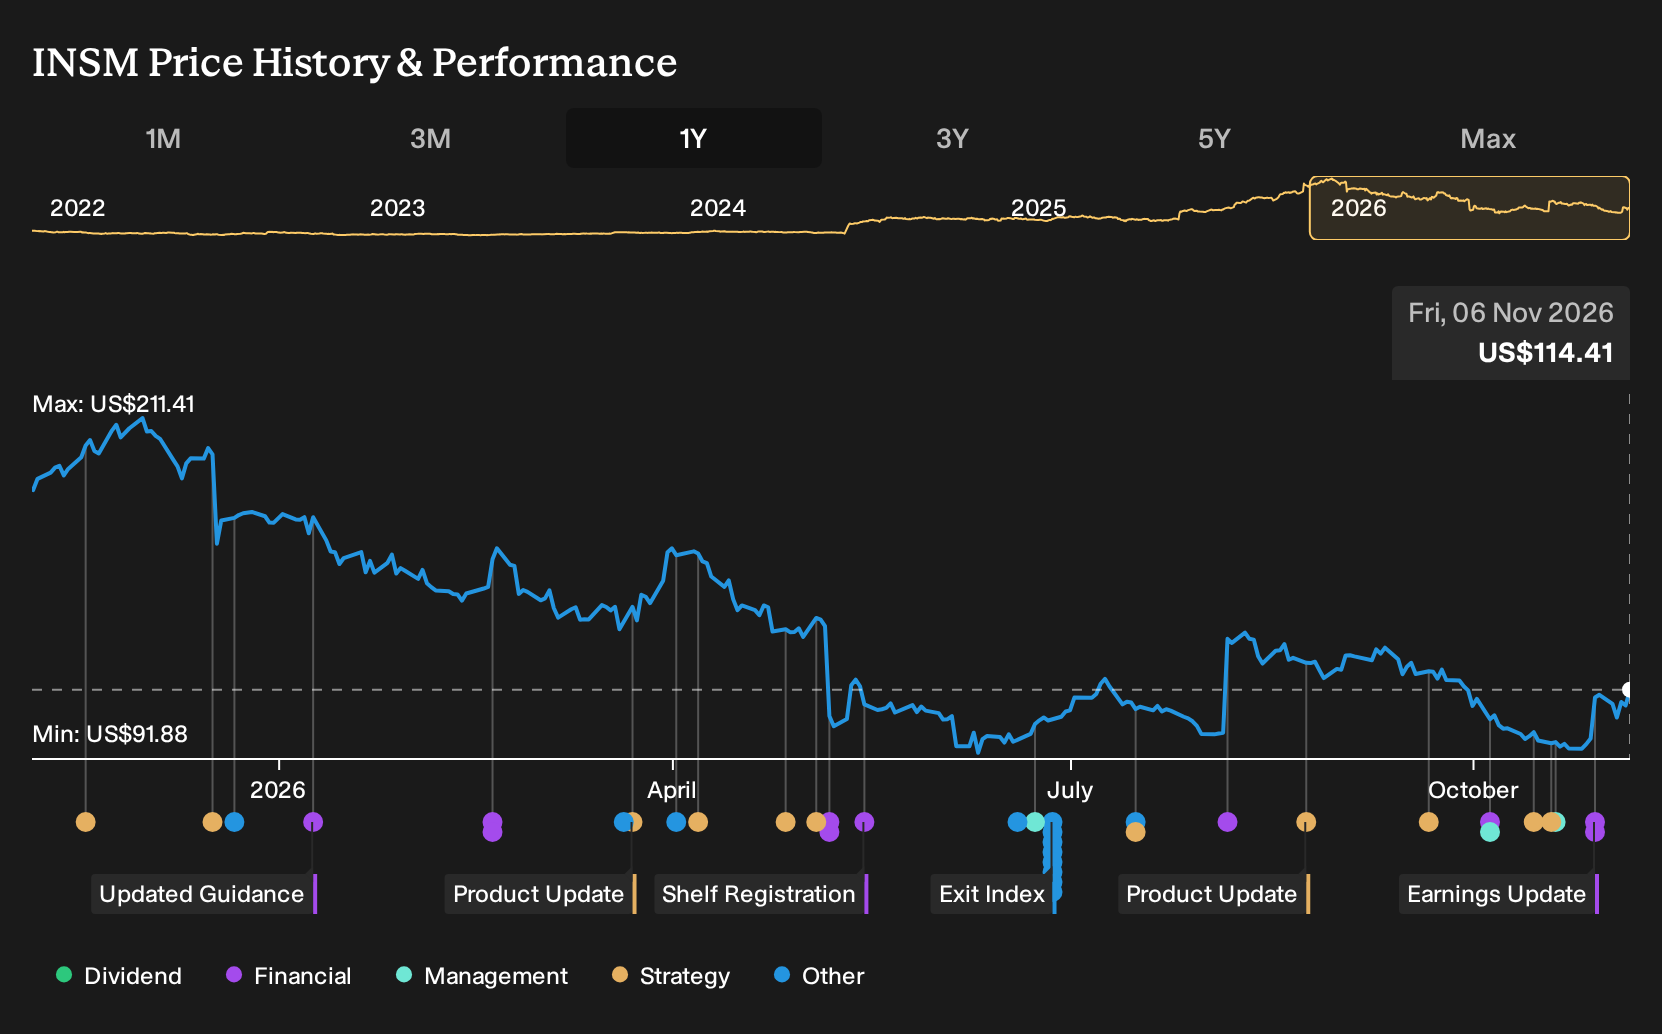
Uncover how Insmed's fair value indicates a 71% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
One alternate angle on Insmed focuses on the risk that TPIP timelines stretch out. The most cautious analysts were assuming 38.1% annual revenue growth and about US$659.8 million in earnings by 2029, far below the consensus US$1.2b view. Those projections came before this earnings update, so you may see those narratives shift.
Explore 2 other Insmed fair value estimates, including one that suggests it could be worth just $194.18!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Insmed research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Insmed. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Insmed's overall financial health at a glance.
Looking for more investment ideas beyond Insmed?
If Insmed does not quite fit your risk and return preferences, widen your search by using the Simply Wall St Screener to scan other listed businesses that better match your style.
- For investors who care most about financial resilience and cleaner balance sheets, start with a list of solid balance sheet and fundamentals (25 results) that may better weather tough conditions.
- If your priority is uncovering potential value where price and fundamentals look misaligned, filter for 39 high quality undervalued stocks that might be worth a closer look.
- Those who want to cast a wider net across under followed opportunities can focus on 19 high quality undiscovered gems that often sit outside the usual watchlists.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com