


EN
Earnings Update Could Change The Case For Huron Consulting Group Stock
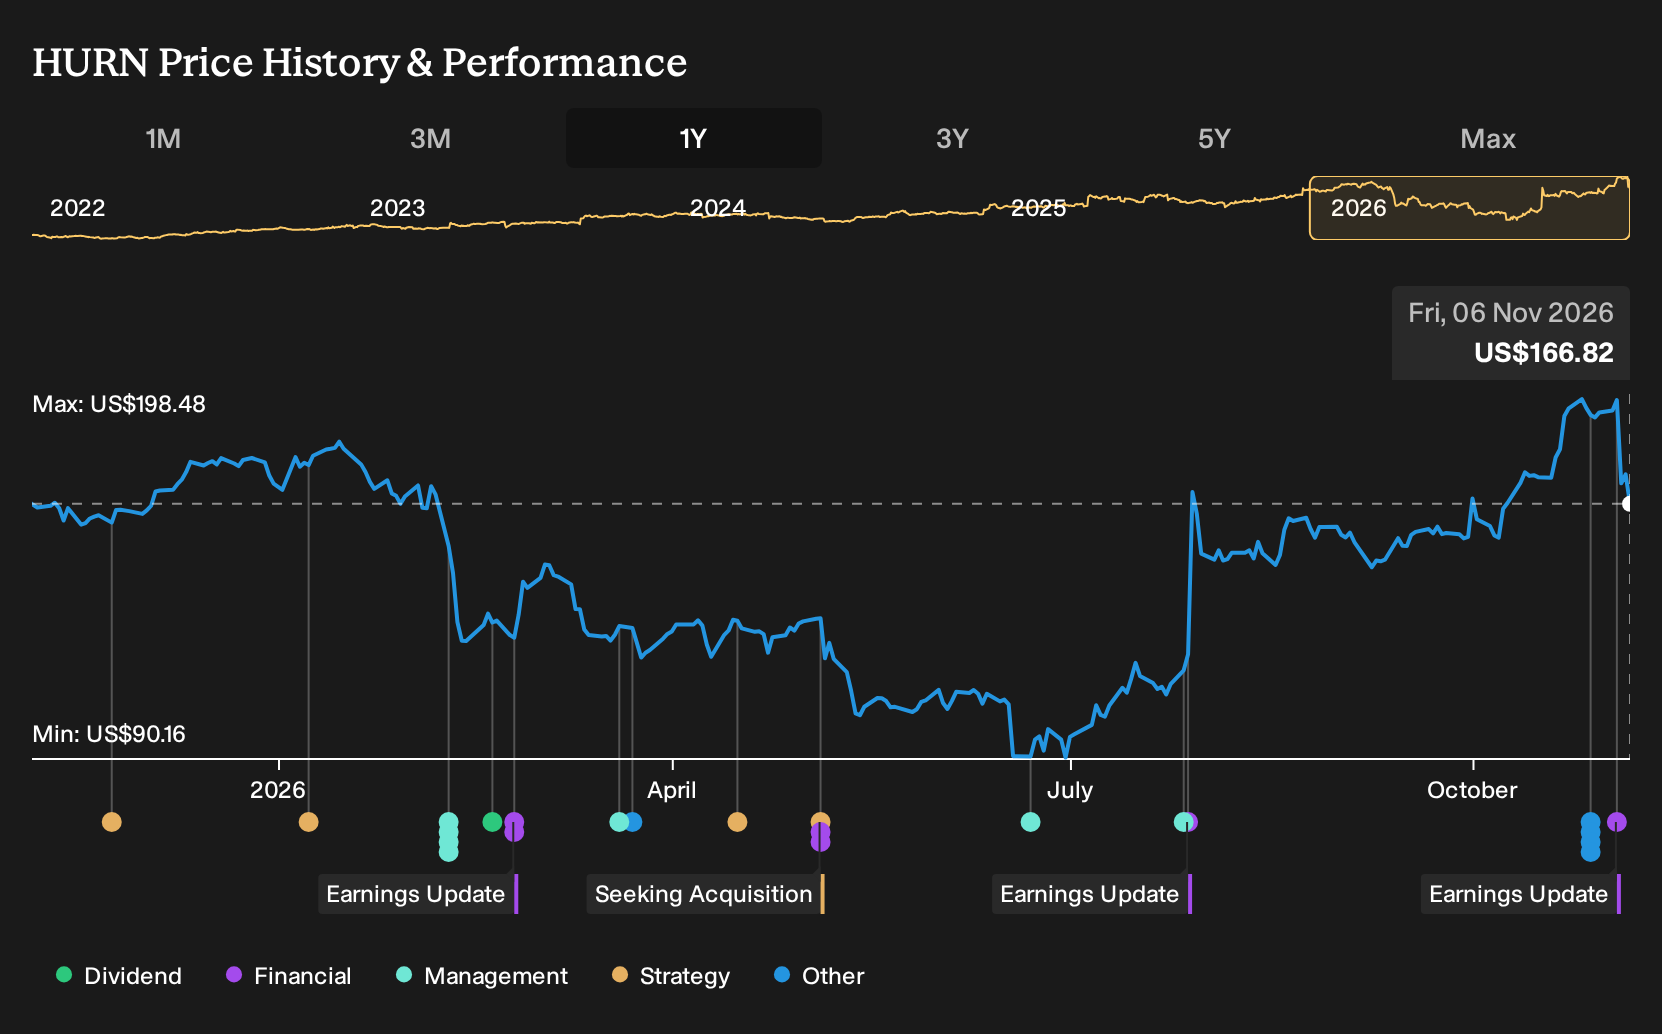
- Huron Consulting Group reported third quarter 2026 revenue of US$491.45 million and net income of US$28.4 million, along with higher earnings per share from continuing operations compared with the same period a year earlier.
- Shortly after releasing these results, Huron Consulting Group was added to the S&P 1000, S&P 600, S&P 600 Industrials sector, and S&P Composite 1500 indices, increasing its visibility among index-linked investors.
- Attention now turns to how Huron Consulting Group's index inclusion may influence the existing investment narrative and risk reward profile.
Scan beyond Huron Consulting Group to find other index-ready contenders using our hand-picked 31 resilient stocks with low risk scores with resilient balance sheets and steadier risk profiles.
What Is Huron Consulting Group's Investment Narrative?
To own Huron Consulting Group, you need to believe this consulting platform can keep turning solid client demand into recurring, high quality earnings while managing its debt load sensibly. The latest quarter fits that story in a mixed way. Revenue for the third quarter and the first nine months of 2026 came in higher than the prior year, and earnings per share from continuing operations also edged up over both periods. Net income, though, was lower in the quarter, and profit margins are thinner than a year ago, which puts more pressure on execution and pricing discipline.
In the short term, the big levers are continued project wins across healthcare, education, and commercial clients, utilization of billable staff, and how much cash actually flows through to the balance sheet, given that debt is not well covered by operating cash flow. Index inclusion into the S&P 600 and related benchmarks may deepen the shareholder base but is unlikely to change day to day operations. Analysts see room above the current share price and classify Huron Consulting Group as good value on several metrics, yet insider selling in recent months and slower earnings growth compared with its 5 year pace keep the risk reward balance tight.
That said, there is still a less visible pressure point in this story once you factor in ...
There's only one way to know the right time to buy, sell or hold Huron Consulting Group. Head to Simply Wall St's company report for the latest analysis of Huron Consulting Group's Fair Value.
Exploring Other Perspectives
One alternate angle on Huron Consulting Group focuses on AI risk. The most bearish analysts worry that clients may slow digital and AI projects. They were penciling in about US$2.4b of revenue and US$223.8 million of earnings by 2029. Those forecasts came before this earnings beat and index inclusion, so their story may shift.
Explore 3 other Huron Consulting Group fair value estimates, including one that suggests there could be as much as 43% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Huron Consulting Group research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Huron Consulting Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Huron Consulting Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Huron Consulting Group?
If Huron Consulting Group has sparked fresh questions about where to allocate your next dollar, it often pays to widen the search and compare it with a broader set of opportunities before making any moves.
- If you want potential mispricing plus balance sheet strength, scan a curated pool of companies screened as 39 high quality undervalued stocks that combine quality fundamentals with relatively lower pricing.
- Income focused investors who care about consistent cash returns can review businesses filtered as 7 dividend fortresses that pair higher yields with sturdier payout profiles.
- For readers who put capital preservation first, work through a list of solid balance sheet and fundamentals (25 results) to concentrate on companies with stronger finances and fewer obvious red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com