


EN
3 US Stocks Tied To Crisis Communications As Governance Risks Hit The Spotlight
When a high profile figure like Nvidia’s Jensen Huang becomes the story, questions about trust, disclosure, and corporate messaging move from the fine print to the front page. That spotlight can create new work and fresh scrutiny for crisis communication and investor relations specialists. This article walks through three stocks exposed to this governance shock and explains how reputational risk can turn into a very real investing decision for you.
The three stocks below are a starting sample of US crisis communications and investor-relations service providers, while the full screen surfaced 23 more businesses with equally detailed stories that are not unpacked in this article. If you want to quickly identify which of these reputational gatekeepers align with your risk tolerance and thesis, head straight to the US Crisis Communications and Investor-Relations Service Providers screener.
CRA International (CRAI)
CRA International plugs directly into this crisis communications theme because its economists and consultants often sit behind the scenes on high stakes investigations, governance reviews, and regulatory questions that shape how boards talk to investors. This is exactly what the analyst consensus Narrative on Simply Wall St focuses on.
CRA International provides economic, financial, and management consulting, often around litigation, regulation, and high stakes corporate decisions linked to governance and communications. The firm generated about US$824 million from professional and consulting services and has a market value of roughly US$1.24b.
CRA International is investing heavily in expert recruitment and retention, with tens of millions of dollars in forgivable loans and retention awards and around 30 new vice presidents ramping ahead of expectations. This can support future utilization, revenue growth and EBITDA dollars once these hires fully mature.
The real swing factor is how one persistent cost pressure interacts with future case flow to shape both margins and crisis related demand.
That swing factor is exactly what the full narrative for CRA International unpacks, including how case flow, hiring and utilization could be accelerating or quietly masking risk.

Omnicom Group (OMC)
Omnicom Group plugs into this crisis communications screen through its PR, governance and investor relations agencies, which step in when reputations and disclosure practices come under pressure for large corporates.
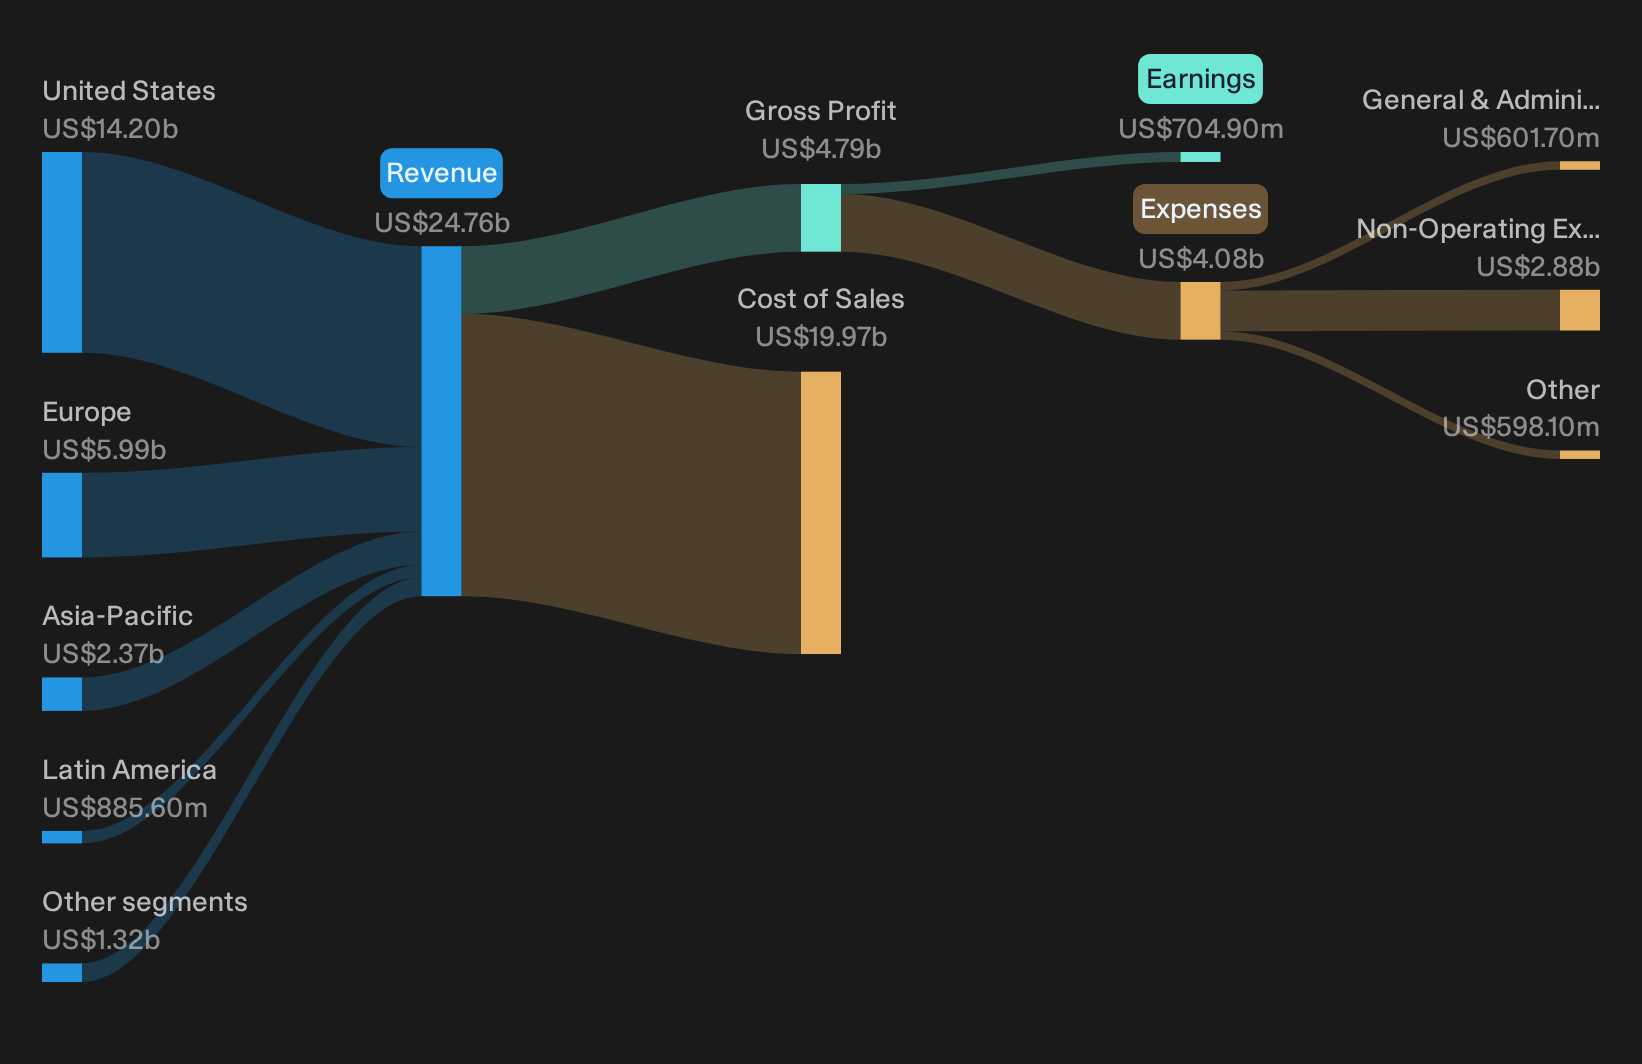
Omnicom Group runs a global advertising, marketing, and corporate communications network, including crisis PR and investor relations services, and generated about US$24.8b from these activities. With a roughly US$23.6b market cap, it is one of the larger players in reputation sensitive communications work.
The analyst consensus Narrative on Simply Wall St notes that Omnicom Group is reshaping itself into a data and AI led operator in marketing and reputation work, with scale becoming a key edge in high stakes communications mandates.
The integration of Interpublic assets with Omnicom Group’s existing media and marketing capabilities is creating what management now describes as the largest global media management network by market share. This can support organic revenue growth through scaled client wins and wider use of data driven solutions.
The real test will be how one quiet cost and integration assumption interacts with future crisis related demand to shape margins and earnings power.
That integration bet is exactly what the full narrative for Omnicom Group pulls apart, separating what might be masking risk from what could be accelerating Omnicom Group’s crisis mandate strength.
Stagwell (STGW)
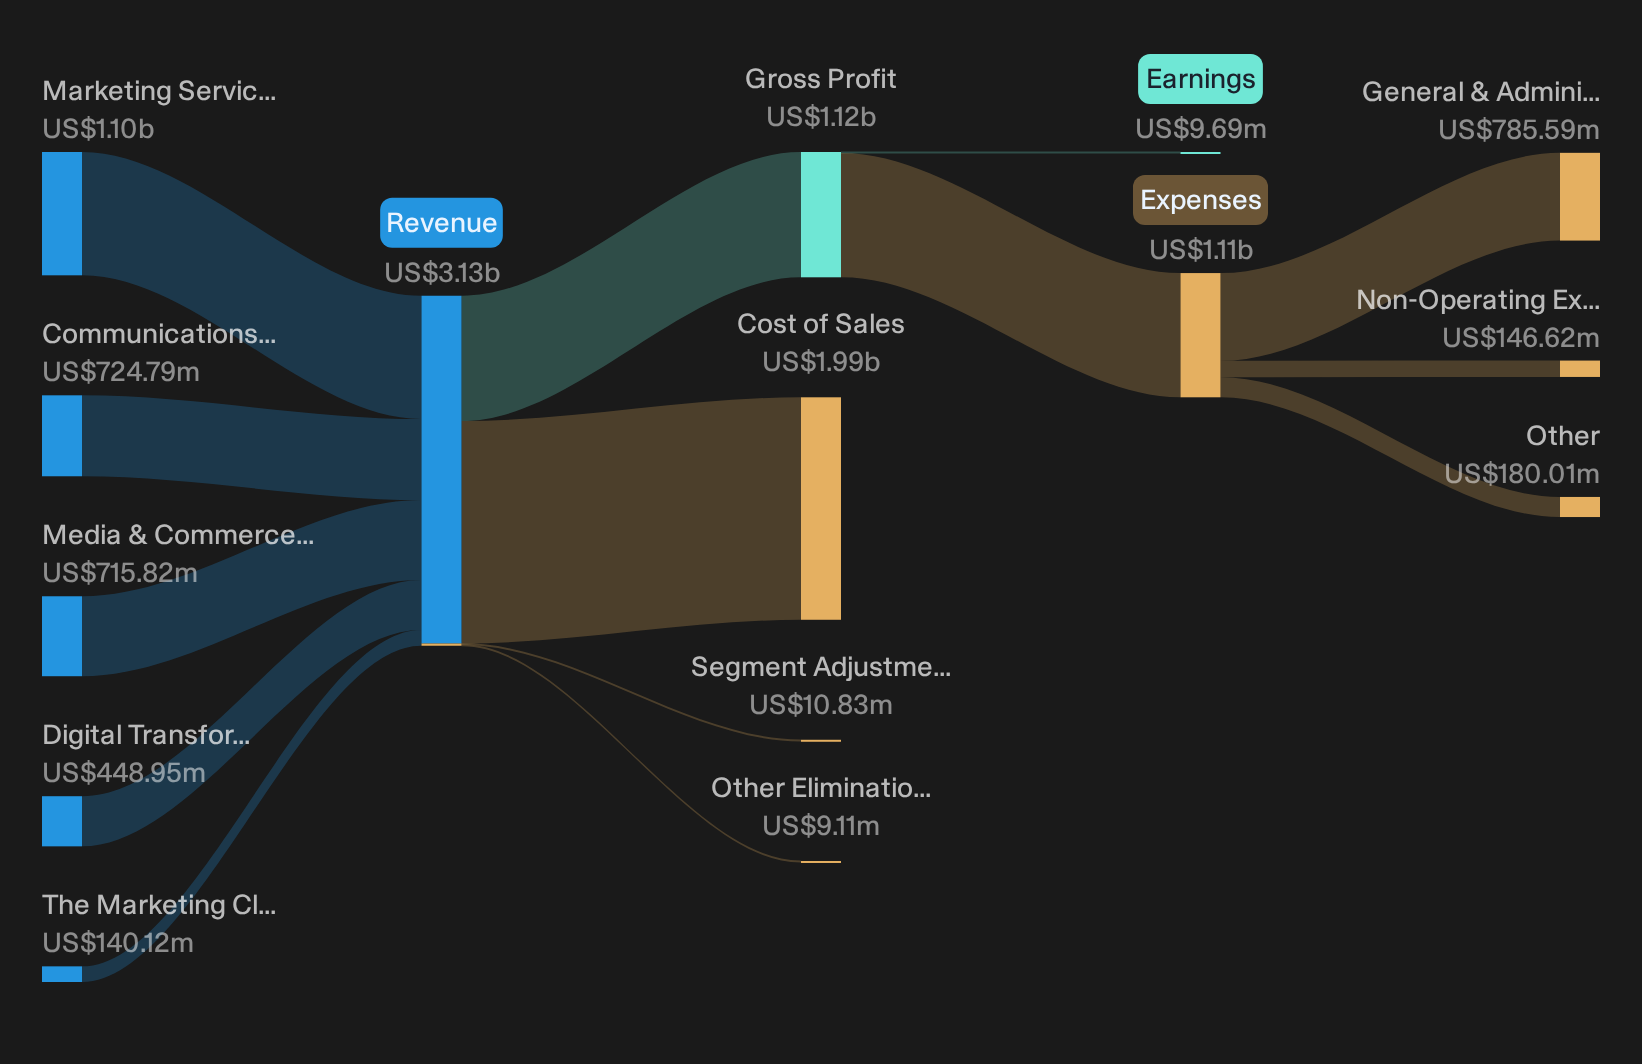
Stagwell links directly to this crisis communications theme through its reputation and stakeholder management work, while most of its roughly US$3.2b in revenue still comes from broader marketing services at about US$1.1b, communications at about US$725 million, and media and commerce at about US$716 million, with a market value near US$2.9b.
Stagwell matters here because it blends classic brand work with reputation management for major corporates, and the analyst consensus Narrative on Simply Wall St argues that its AI led marketing and communications platforms are changing how those sensitive mandates translate into long term earnings power.
Expansion and integration of proprietary digital and martech platforms, including The Machine, Stagwell AI and broader Marketing Cloud offerings, are creating higher margin software and data revenue streams that are already posting EBITDA margins above 30% and are expected to support further net margin expansion.
What happens if a single pressure on that higher margin mix quietly shifts the balance between crisis driven demand and the old lower margin work?
That mix shift risk is exactly what the full narrative for Stagwell digs into, showing where crisis driven demand could be quietly accelerating Stagwell’s higher margin engine.
Seeking Alternatives Before Everyone Else?
Fresh ideas move first. Breakout potential, early momentum and stories still flying under the radar for now can be caught before the crowd. Windows close fast. Consider acting while opportunities are still developing.
- Target dependable income while rates keep shifting by scanning a curated 7 dividend fortresses that focuses on durability, not just headline yield.
- Ride structural trends in automation by reviewing the hand picked 91 robotics and automation stocks shaping factories, logistics and next generation hardware before valuations potentially change.
- Follow infrastructure spending cycles by tracking a filtered 41 power grid technology and infrastructure stocks where demand for grid upgrades may influence future momentum.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com