


EN
Alexander's (ALX) Posts Strong Q3 Results, Is The Valuation Case Still Mixed?
Alexander's (ALX) just posted third quarter results that included higher sales and a sharp jump in earnings per share from continuing operations, putting a fresh spotlight on the real estate investment trust’s recent performance.
Alexander's share price closed at $253.02 on 8 November, with a 1 day share price return of 1.59% and a 30 day share price return of 4.99%, while the 90 day share price return is down 6.73%, indicating improving momentum after a softer stretch. That shorter term shift sits alongside a 15.61% year to date share price return and a 1 year total shareholder return of 19.97%. The 3 year total shareholder return is 64.86% and the 5 year total shareholder return is 35.51%, which highlights that investors who stayed the course have seen materially stronger outcomes over time than those focused only on recent quarterly moves.
Scan beyond Alexander's and see how it compares with a hand picked group of income focused real estate plays in our 7 dividend fortresses.
Bulls point to Alexander's earnings jump and long term return record, while bears flag the current share price and analyst discount. Which side does the valuation evidence support?
Price-to-Earnings of 6.8x: Is it justified?
On a simple earnings lens, Alexander's looks inexpensive. The stock closed at $253.02 while trading on a P/E of 6.8x that screens below both the wider US market and the Retail REITs group.
P/E compares what you pay per share to the profit attributed to that share. For a property trust like Alexander's, this ratio gives a quick feel for how much investors are currently willing to pay for its earnings stream versus other listed businesses.
Here, the multiple sits well under the US market P/E of 17.4x and is far below the US Retail REITs industry average of 24.7x. It is also below the peer average of 23.7x and under the estimated fair P/E of 7.8x, a level the market could move towards if sentiment and earnings quality align with that benchmark.
Explore the SWS fair ratio for Alexander's.
Result: Price-to-Earnings of 6.8x (UNDERVALUED)
Still, the Alexander's story carries clear pressure points, including an annual revenue decline of 2.8% and net income growth moving sharply lower by 98%.
Find out about the key risks to this Alexander's narrative.
Another View on Alexander's Valuation
The earnings multiple paints Alexander's as cheap, yet the SWS DCF model tells a different story. On that cash flow lens, an estimated value of $211.45 per share sits below the current $253.02 price, which suggests the stock screens as overvalued on this method. Which lens should carry more weight for you right now?
Look into how the SWS DCF model arrives at its fair value.
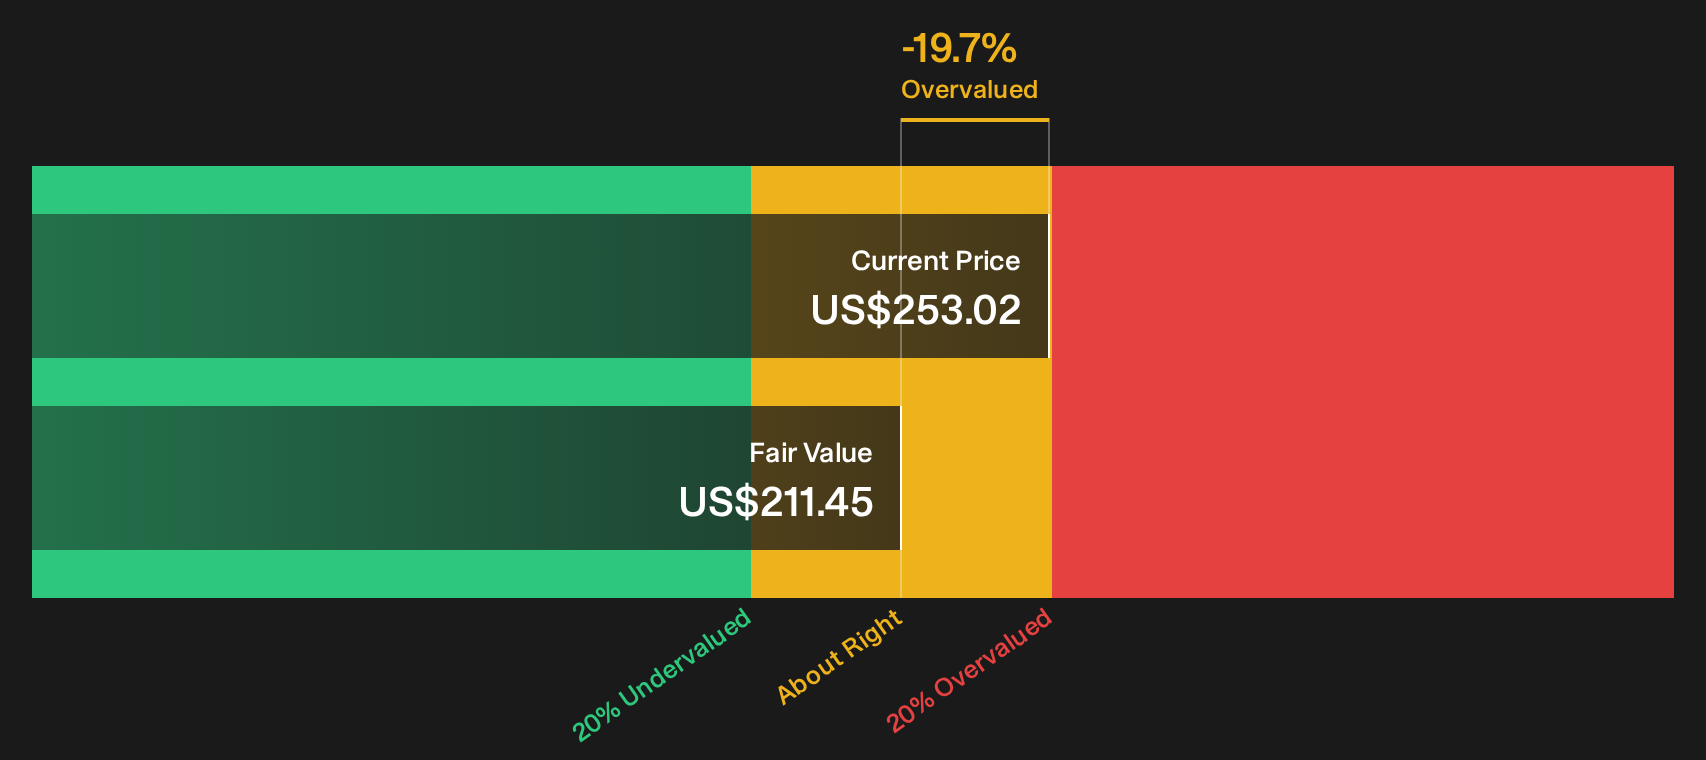
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Alexander's for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Alexander's valuation and fundamentals can pull opinions in opposite directions, so check the underlying data now and form your own stance. To weigh both sides of the story in one place, start with the 3 key rewards and 4 important warning signs.
Looking for more Alexander's investment ideas?
If Alexander's has sharpened your focus on valuation and income, do not stop here. Broader opportunity often sits just outside your current watchlist.
- Target resilience first and scan a list of solid balance sheet and fundamentals (25 results) that can help you concentrate on companies with stronger finances behind their operations.
- Hunt for value by reviewing a 39 high quality undervalued stocks that highlights businesses where quality and price may not fully align.
- Put income front and center with a 7 dividend fortresses that focuses on higher yielding payers backed by more robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com