


EN
Broadcom (AVGO) Shipped New Security Fixes, Is The Stock Cheap?
Broadcom (AVGO) has become a focus again after its TrueSource Spring Enterprise platform shipped fixes for 89 new security vulnerabilities to critical infrastructure customers, expanding its broader patching effort across 408 identified issues.
Broadcom’s share price has retreated sharply from recent highs, with the 30 day share price return down 18.77% and the 90 day share price return down 30.47%. This has occurred even as recent headlines have focused on AI demand, sector wide risk repricing, and large fund flows into semiconductor stocks. Over a longer window, the picture looks different, with total shareholder return over 3 years at about 3.2x and over 5 years at roughly 4.7x. This indicates that the long term story has been strong even while short term momentum has faded in the current reset.
Spot opportunities across AI infrastructure by comparing Broadcom with a curated list of 53 AI infrastructure stocks.After a 30% reset and with Broadcom trading well below the average analyst target and an intrinsic value estimate, the gap is clear. The harder call is whether that gap reflects risk or opportunity.
Most Popular Narrative: 55% Undervalued
Broadcom closed at $293.69 while the leading narrative on the stock anchors fair value at $651.05, implying a wide valuation gap and putting more weight on the long term cash engine than on the recent share price slide.
That view comes from niteco, an investor in the Simply Wall St Community, who frames Broadcom less as a chip pure play and more as a critical digital infrastructure platform that converts demand for computing and connectivity into cash over time at an 11.18% discount rate.
The opportunity is not that Broadcom becomes the next Nvidia. The opportunity is that Broadcom continues doing what it has done for years: owning critical infrastructure, generating cash, and allocating capital intelligently.
See why 175 investors see Broadcom as 55% undervalued.
On this view, the current discount is tied to short term concern about AI spending cycles while the narrative focuses on whether data movement, networking capacity, and software complexity keep Broadcom’s infrastructure role relevant over many years. The narrative leans on the company’s history of cash generation, its role across custom silicon and networking, and a capital allocation track record that supporters see as central to compounding value.
The result is a valuation framework where the fair value of $651.05 sits well above the present price, with the gap framed as a function of long term digital infrastructure demand rather than near term quarterly swings.
Result: Fair Value of $651.05 (UNDERVALUED)
Still, the Broadcom narrative can break if AI infrastructure orders reset faster than expected, or if large customers slow custom silicon adoption and compress returns.
Find out about the key risks to this Broadcom narrative.
Another View: Broadcom Through The P/E Lens
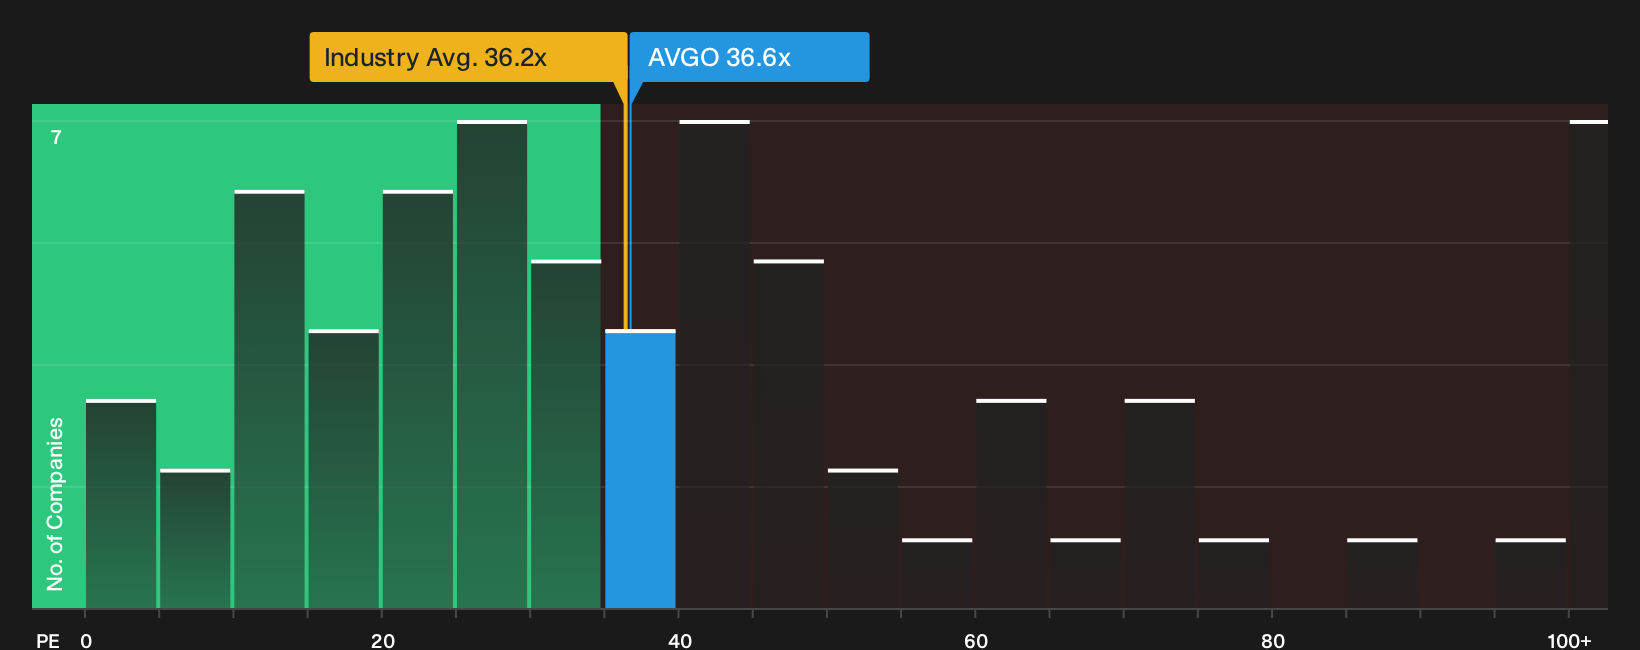
There is a very different message if you value Broadcom using its P/E ratio instead of cash flows. At 36.6x earnings, the stock trades slightly above the US Semiconductor industry at 36.2x, yet sits below its own fair ratio of 40.7x and well under a peer average of 81.9x. That mix points to some valuation risk if sentiment cools, but also to potential room for the multiple to drift closer to the fair ratio if current expectations hold. So which way do you think the market leans next?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the Broadcom story so far sounds divided, treat that tension as your prompt to move fast, stress test the numbers, and then trust your own read. To see what others flag as potential upsides, review the 4 key rewards.
Looking for more Broadcom investment ideas?
If Broadcom has sharpened your thinking, do not stop here. Broaden your watchlist with focused screeners that highlight different strengths so you keep your edge.
- Target stronger balance sheets by reviewing companies filtered through our list of solid balance sheet and fundamentals (25 results) that pair financial resilience with cleaner fundamentals.
- Hunt for potential mispricings with a curated set of 39 high quality undervalued stocks that combine solid cash flows and supportive balance sheets.
- Prioritize stability and income by scanning 7 dividend fortresses that offer higher yields with an emphasis on consistency.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com