


EN
How Expanded Buyback Authorization At Commerce Bancshares Stock Has Changed Its Investment Story
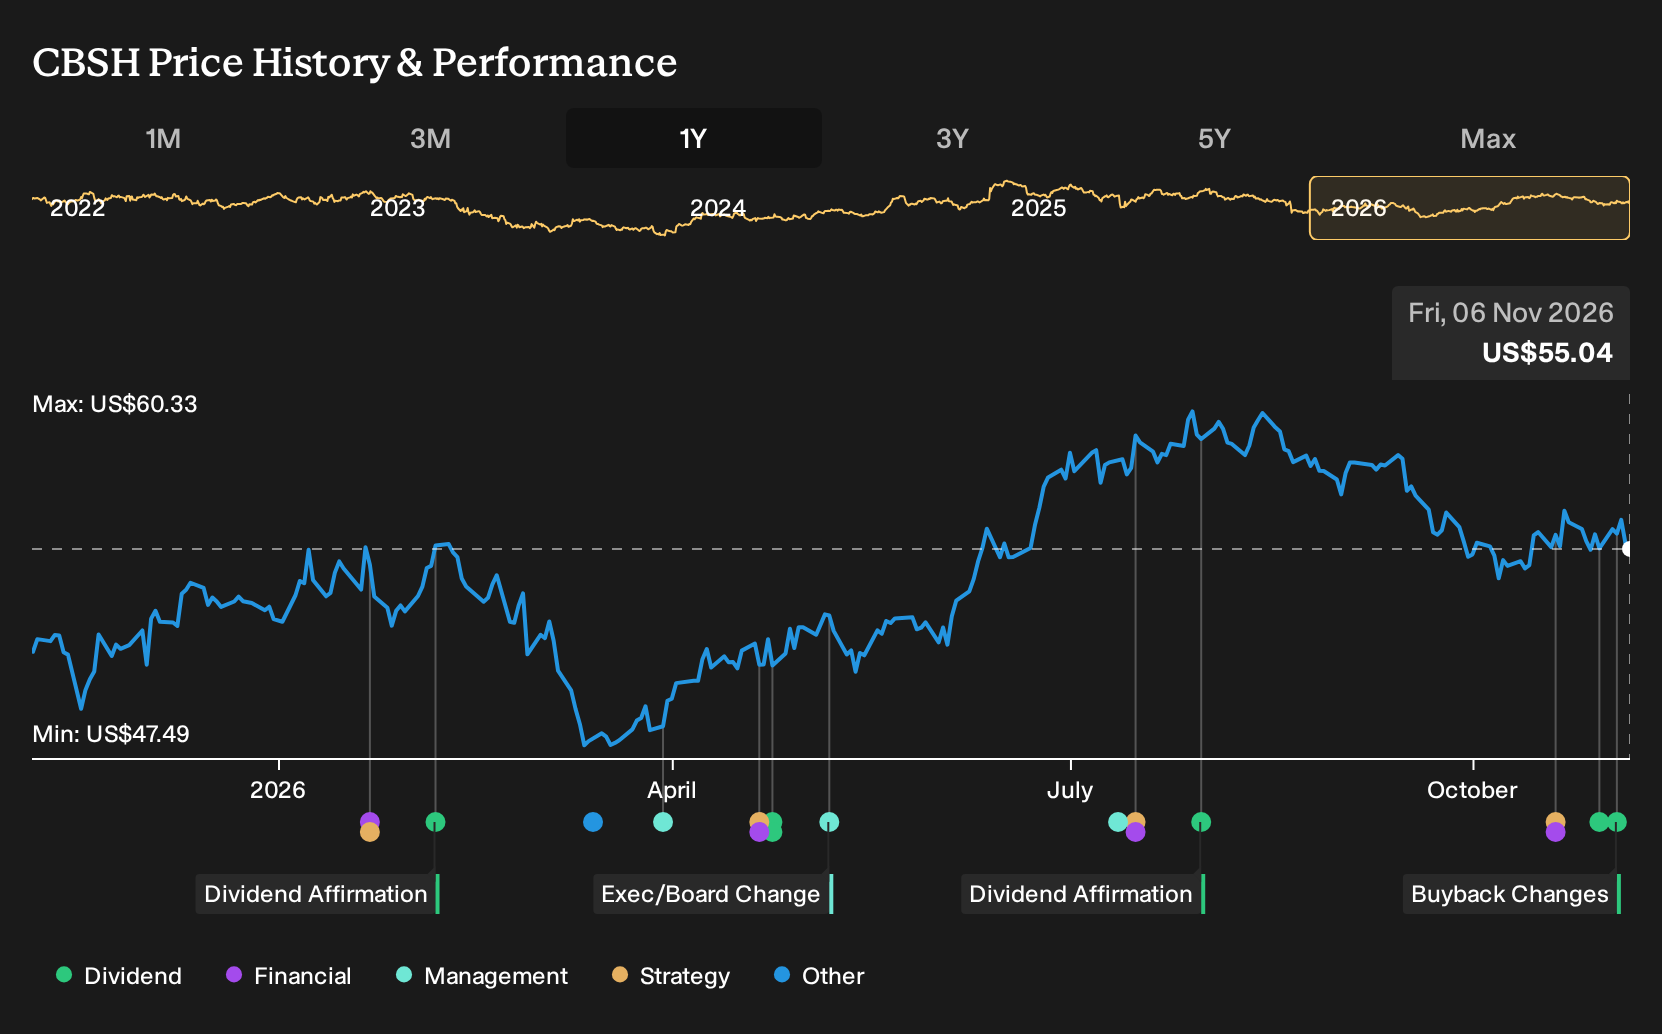
- Commerce Bancshares increased its remaining share repurchase authorization to 7,500,000 shares and recently affirmed a quarterly dividend of $0.275 per share payable on December 21, 2026 to stockholders of record on December 1, 2026.
- The larger buyback capacity gives Commerce Bancshares more flexibility in how it allocates capital between supporting fee driven growth initiatives, absorbing acquisition integration costs, and returning cash to shareholders.
- We will now explore how Commerce Bancshares' investment narrative may be influenced by the expanded share repurchase authorization announced alongside its ongoing dividend.
Commerce Bancshares Investment Narrative Recap
To own Commerce Bancshares you need to be comfortable with a bank that leans heavily on fee income and wealth management alongside traditional lending. The analyst consensus Narrative on Simply Wall St highlights execution on acquisitions and systems as central. The bigger near term swing factor still looks like how net interest margin trends if deposit costs stay sticky while asset yields reset lower.
Expense control remains the other pressure point. Integration spending around FineMark and Nolan & Associates has already lifted non interest costs. The enlarged capital return plans do not materially change that near term risk, and the key operational catalyst still sits with completing systems work and proving those deals translate into better efficiency and fee revenue.
The expanded 7,500,000 share repurchase authorization is the announcement that ties most directly to this story. A larger program can influence per share metrics, especially if earnings grow in line with analyst expectations, but it also competes with other uses of capital like technology investment and acquisition integration.
For you as a shareholder, the question is whether Commerce Bancshares can keep funding fee based growth, digital initiatives such as the CONNECT platform, and integration of FineMark and Nolan while still supporting the dividend and using this buyback capacity. Execution around those projects, plus how long margin pressure persists, will likely matter more than the headline repurchase figure itself.
Commerce Bancshares' current analyst narrative points to forecast revenue of US$2.2b and earnings of US$664.7m by 2029, based on an assumed 6.2% yearly revenue growth rate and an increase in earnings of about US$86.5m from US$578.2m today.
Uncover why Commerce Bancshares' fair value indicates a 17% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community cluster between US$63.94 and US$81.41, which is a wide band for the same Commerce Bancshares story. Those retail views pre date the larger buyback and affirmed dividend, while margin pressure and higher costs remain live issues that could steer the company’s actual performance away from any single estimate.
Explore 2 other Commerce Bancshares fair value estimates, including one that suggests it could be worth just $63.94.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Commerce Bancshares research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Commerce Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Commerce Bancshares' overall financial health at a glance.
Looking For More Investment Ideas Beyond Commerce Bancshares?
Once you have a view on Commerce Bancshares, it can help to set it beside other opportunities with different risk profiles, income potential, and balance sheet strength. The Simply Wall St Screener lets you do that quickly by filtering for specific traits that matter to you as an investor.
- If you want a broader opportunity set with higher potential upside but also higher risk, scan the market using 10 elite penny stocks with strong financials and see which smaller companies pass a basic quality filter.
- For investors who put capital preservation first, start with 31 resilient stocks with low risk scores and compare how those businesses stack up on volatility and financial resilience.
- If you are looking for strong fundamentals that have not attracted much attention yet, use the 19 high quality undiscovered gems as a shortlist to research further.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com