


EN
Why Westinghouse Air Brake Technologies (WAB) Is Getting Attention Today
Westinghouse Air Brake Technologies (WAB) just locked in a long term Material and Technical Support Agreement with Transnet Engineering, a roughly US$390 million deal centered on locomotive maintenance and digital monitoring.
Recent trading suggests investors are rewarding that kind of long term contract visibility, with Westinghouse Air Brake Technologies’ share price up 31.12% year to date and its 1 year total shareholder return of 38.10% building on a very strong 3 year total shareholder return of 155.81%.
Scan beyond Westinghouse Air Brake Technologies to see which other rail and industrial suppliers are showing strong momentum and fundamentals in the list of solid balance sheet and fundamentals (25 results).
After a near 32% year to date surge and a fresh US$390 million contract win, Westinghouse Air Brake Technologies now sits at a crossroads. Does the current valuation still offer a favourable trade off between risk and reward?
Most Popular Narrative: 14% Undervalued
On the analyst consensus Narrative on Simply Wall St, Westinghouse Air Brake Technologies screens as undervalued, with a fair value estimate of $329.58 against a last close of $283.59. That setup leans heavily on how services, software and acquisitions reshape the earnings mix over time.
Rapid growth in Digital Intelligence offerings, with sales up around 76% in Q1 2026 and around 89% in Q2 2026 helped by Inspection Technologies and Frauscher, is increasing the mix of software and data driven services that tend to carry higher gross margins and can lift overall earnings quality.
See why 25 investors see Westinghouse Air Brake Technologies as 14% undervalued.
Result: Fair Value of $329.58 (UNDERVALUED)
Still, the Westinghouse Air Brake Technologies story can break if tariffs persistently squeeze margins or if weaker modernization volumes keep services income from matching the bullish narrative.
Find out about the key risks to this Westinghouse Air Brake Technologies narrative.
Another View: What Multiples Say About Westinghouse Air Brake Technologies
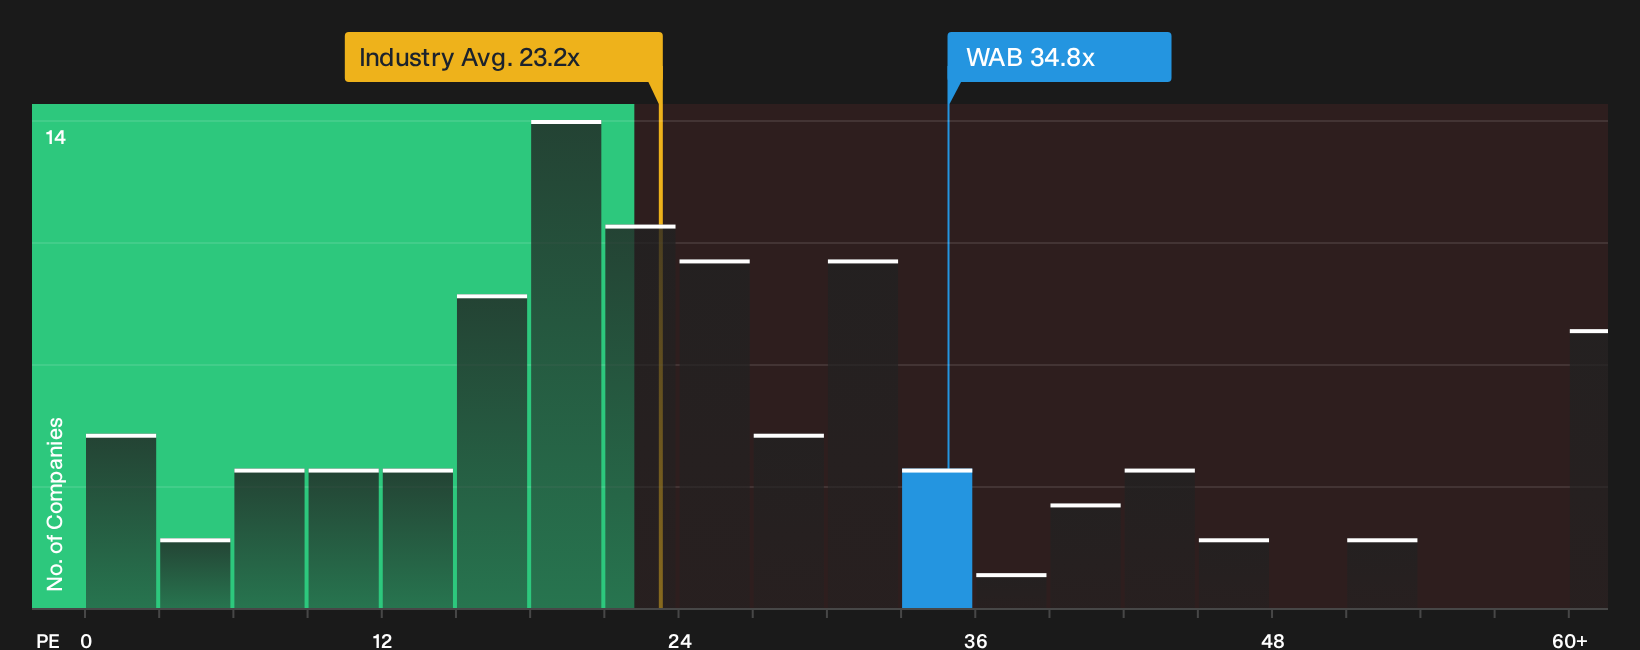
Analyst models on Simply Wall St frame Westinghouse Air Brake Technologies as undervalued, yet the current P/E of 34.8x sits above both its fair ratio of 32.1x and the US Machinery industry on 23.2x and peers on 19x. That richer tag raises a simple question for investors: Is the margin of safety really as wide as it looks?
For anyone leaning on comparison multiples, it helps to see how this richer P/E stacks up visually and where valuation pressure could emerge over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Westinghouse Air Brake Technologies so far. If you want to move fast and judge the balance for yourself, start by weighing its 2 key rewards and 2 important warning signs.
Looking for more Westinghouse Air Brake Technologies investment ideas?
Westinghouse Air Brake Technologies might be front of mind today, but your next strong idea could be hiding in plain sight if you know where to look.
- Chase value first and focus on quality by scanning 39 high quality undervalued stocks that combine appealing prices with fundamentals you can actually justify.
- Prioritise resilience and protect your downside by working through 31 resilient stocks with low risk scores that aim to keep volatility and fragile balance sheets in check.
- Hunt for tomorrow's potential leaders before they hit the spotlight using 19 high quality undiscovered gems that already show solid financial underpinnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com