


EN
Did Return To Profit Just Shift ATS' Investment Narrative?
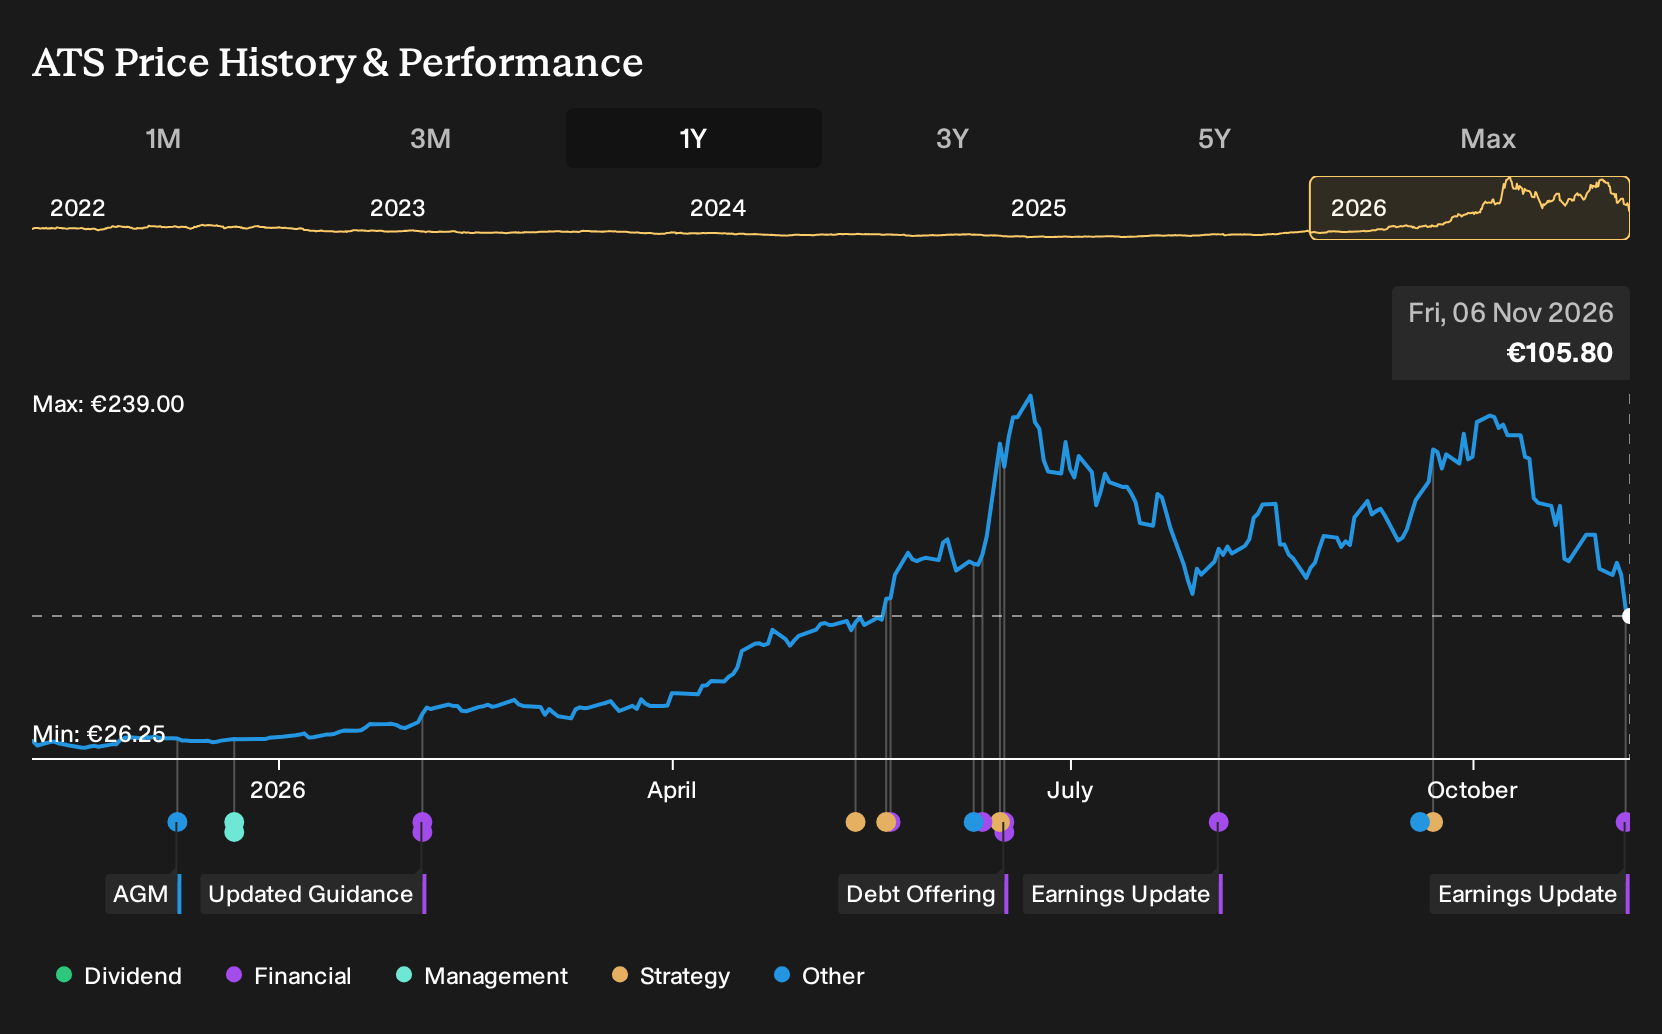
- AT & S Austria Technologie & Systemtechnik reported second quarter sales of €681.88 million and net income of €125.37 million, with basic earnings per share from continuing operations at €3.05 for the period ended September 30, 2026, compared with a loss a year earlier.
- For the first half of the financial year, AT & S Austria Technologie & Systemtechnik recorded €1,230.58 million in sales and €166.22 million in net income.
- We will look at how AT & S Austria Technologie & Systemtechnik's investment narrative is affected by this return to quarterly profitability.
Compare AT & S Austria Technologie & Systemtechnik's earnings rebound with other potential beneficiaries of AI infrastructure demand by scanning 53 AI infrastructure stocks in the same theme.
AT & S Austria Technologie & Systemtechnik Investment Narrative Recap
To own AT & S Austria Technologie & Systemtechnik, you need to believe in sustained demand for advanced substrates and printed circuit boards tied to AI, data centers, and complex electronics, as framed in the analyst consensus Narrative on Simply Wall St. The latest quarter shows the business earning money again, which helps confidence that existing and new plants can support that story.
The key near term swing factor remains how quickly new capacity in Austria and Malaysia fills with high value substrate orders. The sharp move from loss to profit reduces immediate earnings stress but does not remove execution risk around customer qualification, utilization, and heavy investment that still leans on debt and operating cash flow.
The earnings release for the quarter and first half to 30 September 2026 is the announcement that matters most here. AT & S Austria Technologie & Systemtechnik reported €681.88 million in quarterly sales and €125.37 million in net income, turning around a loss a year earlier, and €1,230.58 million in sales with €166.22 million in profit for six months.
Those figures give you fresh evidence on two big catalysts from the analyst consensus Narrative on Simply Wall St. First, whether AI and data center exposure is starting to show up in the income statement. Second, whether cost saving plans and new facilities can move margins while the business manages balance sheet pressure from high investment and volatile orders.
AT & S Austria Technologie & Systemtechnik's current narrative is anchored on analysts expecting revenue to reach €4.1b and earnings of €754.4 million by 2029, implying forecast revenue growth of 28.2% a year and an increase in earnings of about €701 million from €53.4 million today.
Uncover why AT & S Austria Technologie & Systemtechnik's fair value indicates a 191% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view hangs on AT & S Austria Technologie & Systemtechnik keeping EBITDA margins above 30%, helped by higher margin optical interconnects and co packaged optics. Bullish analysts were already pencilling in about €4.6b of revenue and €922.6 million of earnings by 2029. This earnings surprise might push those optimistic narratives even further, or prompt a reset.
Explore 2 other AT & S Austria Technologie & Systemtechnik fair value estimates, including one that suggests potential upside of up to 191% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AT & S Austria Technologie & Systemtechnik research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AT & S Austria Technologie & Systemtechnik. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AT & S Austria Technologie & Systemtechnik's overall financial health at a glance.
Looking for more AT & S Austria Technologie & Systemtechnik style ideas?
If this earnings turnaround has you rethinking where AT & S Austria Technologie & Systemtechnik fits in your portfolio, it can help to line it up against other stocks with different risk and quality profiles using the Simply Wall St Screener.
- If capital preservation is near the top of your list, look at a set of stocks that score well on resilience and balance sheet risk by reviewing the 207 resilient stocks with low risk scores.
- If income is a priority, compare AT & S Austria Technologie & Systemtechnik with companies offering stronger yields by scanning the 227 dividend fortresses.
- If you want to cast the net wider for quality that might be off most radars, broaden your research with the 572 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com