


EN
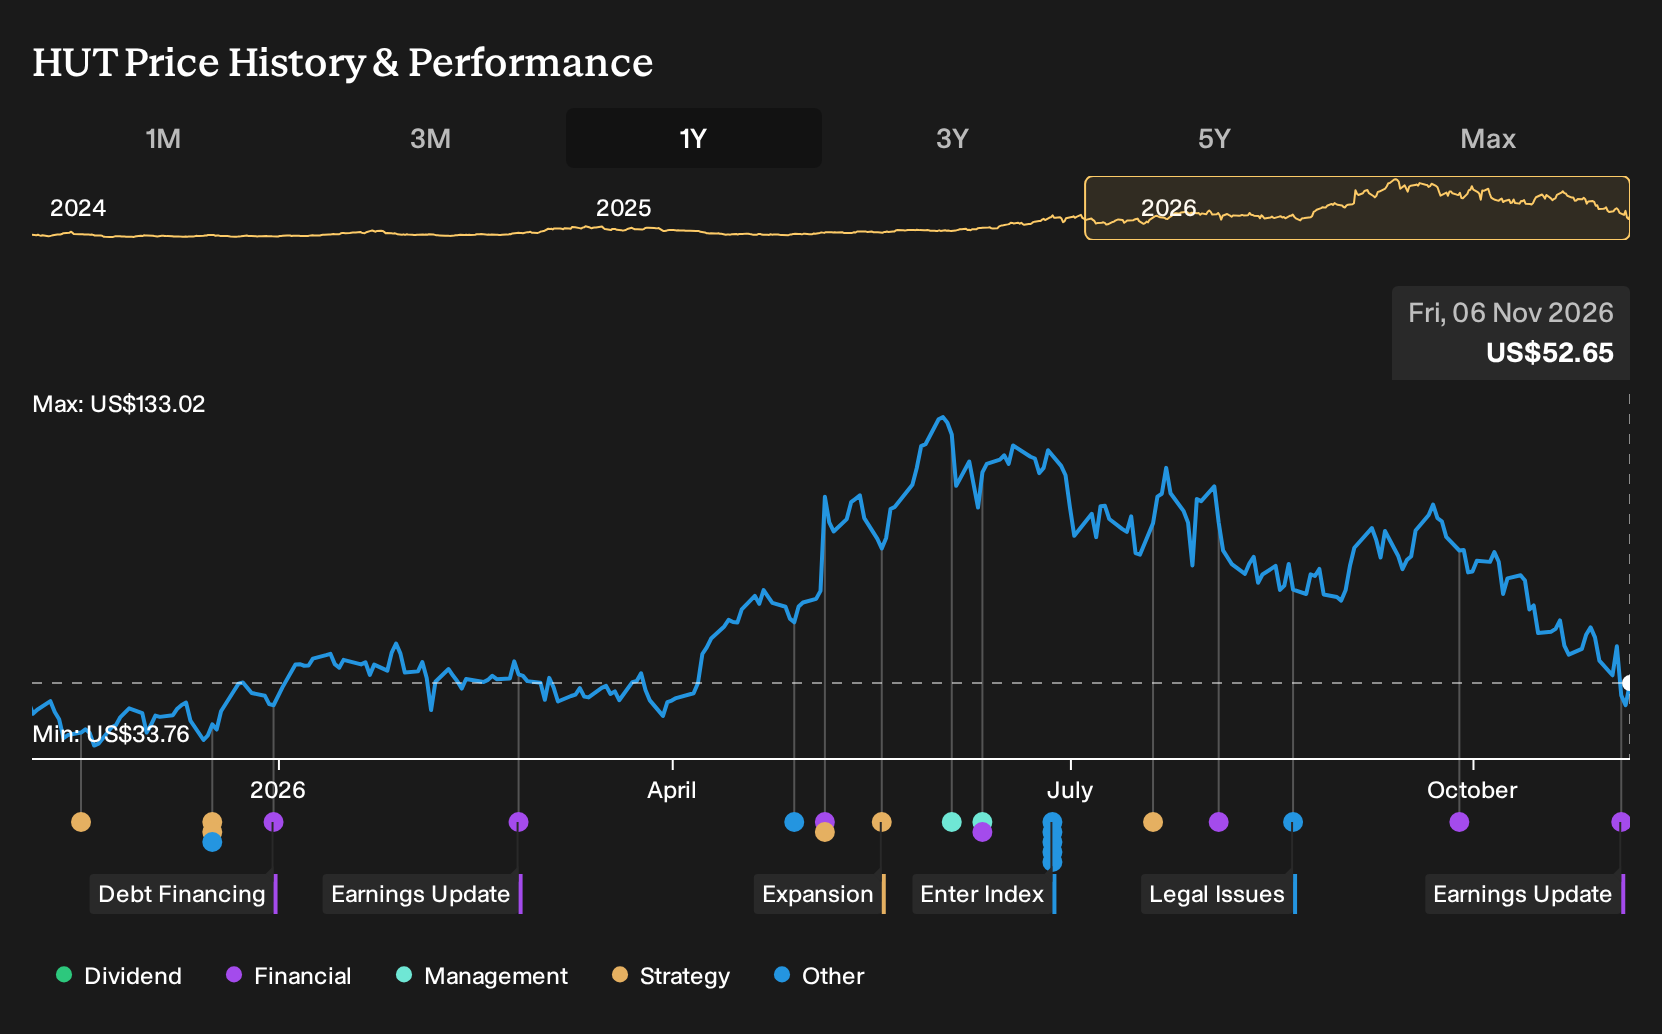
Hut 8 Stock Faces Texas AI Center Risk After Revenue Slip
- Hut 8 reported third quarter 2026 revenue of US$71.07 million, compared with US$83.51 million a year earlier, while net income reached US$131.07 million and diluted earnings per share from continuing operations came in at US$0.98.
- Despite higher third quarter profitability, Hut 8 is contending with a nine month loss of US$238.97 million and regulatory uncertainty in Texas that could affect its AI data center build out and contracted capacity.
- We will now look at how Hut 8's investment narrative is shaped by Texas regulatory risk alongside the recent revenue softness.
Compare how Hut 8's mix of AI infrastructure and crypto exposure stacks up against other potential breakout plays in our curated list of 53 AI infrastructure stocks.
Hut 8 Investment Narrative Recap
To own Hut 8, you need to believe the blend of AI data centers and Bitcoin related compute can turn current volatility into a more durable cash engine. The latest quarter shows this tension clearly. Revenue for the third quarter came in at US$71.07 million, while net income reached US$131.07 million, alongside a nine month loss of US$238.97 million.
The near term hinge point is Beacon Point in Texas, which DanielOliveira, an investor in the Simply Wall St Community who wrote the Narrative, flags as the key operational swing factor. Management’s comments that the Texas political shift does not alter its Beacon Point view matter for confidence, but regulatory timing and Hut 8’s limited cash runway still look like the central risk to execution.
The clearest fresh data point is the earnings release itself. Hut 8 reported US$71.07 million of third quarter revenue compared with US$83.51 million a year earlier, while net income reached US$131.07 million compared with US$50.11 million. Over nine months, the group produced US$217.02 million of revenue but a net loss of US$238.97 million, which keeps the focus firmly on financing and cash burn.
DanielOliveira argues that December 17, when management expects clarity on Beacon Point’s baseload designation and financing path, is more important than the election date itself. That timing now frames the main catalyst for Hut 8. Progress on the River Bend AI data hall targeted for the second quarter of 2027, together with large Texas leases, sits on one side of the scale. Regulatory decisions on Beacon Point and limited cash runway sit clearly on the other.
In that Narrative, DanielOliveira arrives at a fair value of US$48.94 for Hut 8 mainly because the analysis treats December 17 as the key date that could clear Beacon Point’s baseload status and financing hurdles, which in turn anchors the potential value of the broader development pipeline.
Uncover how Hut 8's fair value indicates a 7% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate view focuses less on Texas risk and more on how much AI leasing could reshape Hut 8. The most optimistic analysts were pencilling in roughly US$2.0b of revenue and US$596.9 million of earnings by around 2029 before this earnings release. That outlook is far more upbeat, and the latest numbers may prompt them to rethink.
Explore 6 other Hut 8 fair value estimates, including one that suggests up to 344% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hut 8 research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Hut 8. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hut 8's overall financial health at a glance.
Looking for more ideas beyond Hut 8?
If Hut 8 has your attention but you want a few more angles for your watchlist, the Simply Wall St Screener can help you quickly scan for different types of opportunities that match your risk and income preferences.
- If capital preservation is a priority, start by filtering for companies that look more resilient on key metrics with a curated 31 resilient stocks with low risk scores.
- For investors who care about balance sheet strength first, focus on businesses with cleaner leverage profiles and stronger fundamentals through this list of solid balance sheet and fundamentals (25 results).
- If you are hunting for overlooked stories, expand your research with a hand picked collection of 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com