


EN
Is IPG Photonics (IPGP) Cheap As Earnings And Guidance Come Into Focus?
IPG Photonics earnings and guidance come into focus
IPG Photonics (IPGP) drew fresh attention after releasing third quarter 2026 results and updating guidance for the next quarter, giving investors new revenue and profit markers to assess the stock.
That fresh guidance came after a sharp move in IPG Photonics’ share price, with a 1-day share price return of 5.29% offsetting part of a recent slide that left the 30-day share price return down 16.56% and the 1-year total shareholder return down 24.56%. Investors appear to be weighing the improved quarterly earnings against a longer track record of weaker total shareholder returns, as the 5-year total shareholder return has fallen 61.63%, even as the stock reacts quickly to new information such as the latest third quarter results and fourth quarter revenue outlook.
See how IPG Photonics compares with other potential rebound stories in our hand picked list of 39 high quality undervalued stocks.
Bulls argue the earnings rebound and fresh guidance show IPG Photonics is turning a corner. Bears point to years of weak shareholder returns. Which story does the current valuation support next?
Most Popular Narrative: 45% Undervalued
IPG Photonics last closed at $65.31, while the analyst consensus Narrative on Simply Wall St anchors fair value at about $118.43. This narrative frames the stock as materially discounted against its own cash flow and earnings path using an 8.74% discount rate.
The main factor that needs to work in the company’s favor is that IPG Photonics converts its shift toward higher value systems, medical expansion including Lumibird Medical, and directed energy programs such as CROSSBOW into sustained, profitable revenue that can help offset volatility in micromachining and defense.
See why 4 investors see IPG Photonics as 45% undervalued.
Result: Fair Value of $118.43 (UNDERVALUED)
Still, the IPG Photonics story can break if volatility in Advanced Solutions persists or if margin recovery stalls and the recent earnings rebound loses momentum.
Find out about the key risks to this IPG Photonics narrative.
Another View: What IPG Photonics’ P/E Is Really Saying
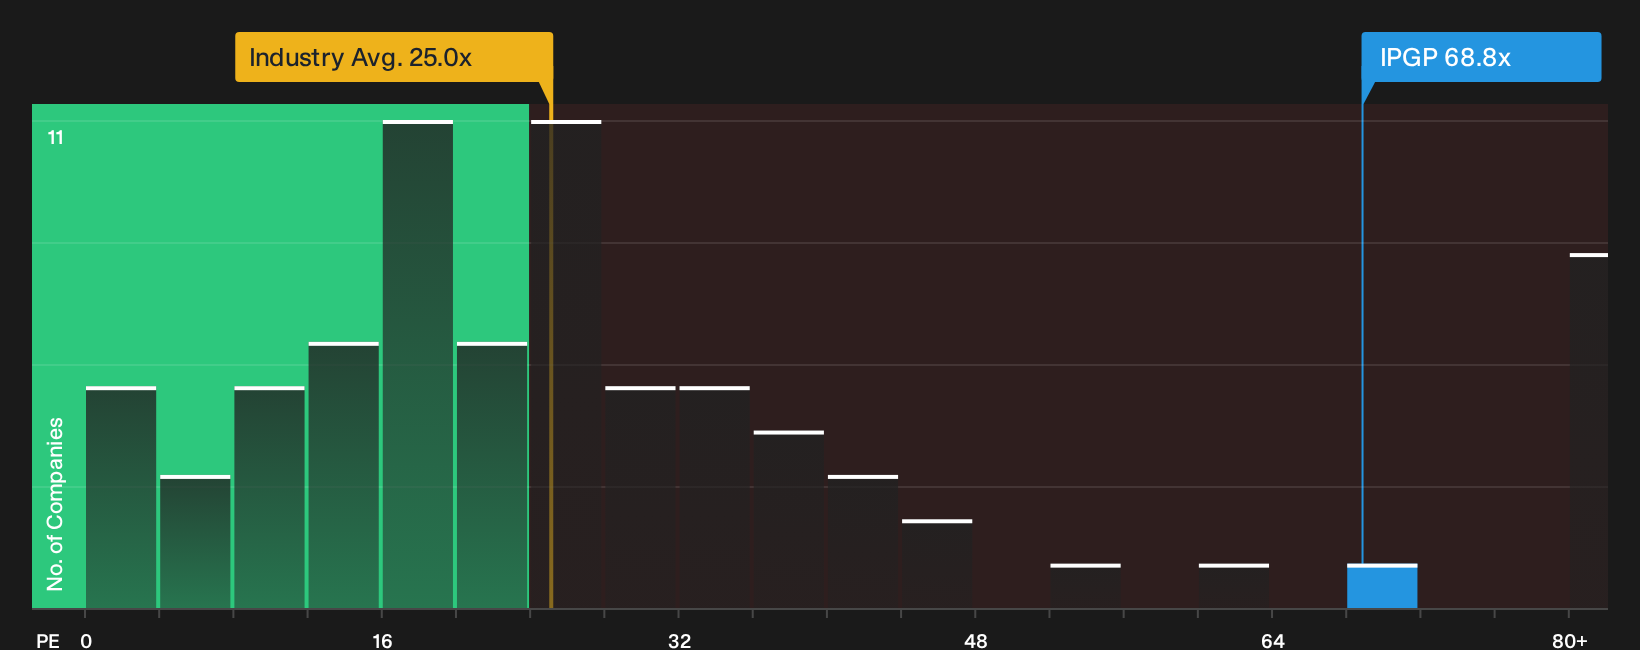
There is a very different message when you look at IPG Photonics through its P/E ratio. The stock trades on about 68.8x earnings, compared with roughly 25x for the broader US Electronic industry and about 27.4x for peers, while the fair ratio sits closer to 50x.
That gap means the market is already paying a richer price for IPG Photonics than both its sector and the fair ratio suggest, even as long term shareholder returns have been weak. The question for you is simple: are the current growth forecasts strong enough to keep justifying that premium if sentiment shifts again?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on IPG Photonics so far. If you want to move quickly and shape your own view, start by weighing both the concerns and the upside in the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond IPG Photonics?
If IPG Photonics has sharpened your focus on valuation and quality, broaden your watchlist now so you do not miss stronger setups elsewhere.
- Target resilient cash generators by scanning our list of solid balance sheet and fundamentals (25 results) that can help anchor your portfolio when sentiment swings.
- Hunt for mispriced opportunities using the 39 high quality undervalued stocks and spot companies where fundamentals and current prices are out of sync.
- Build a potential income stream with the 7 dividend fortresses that highlights businesses offering higher yields with supporting financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com