


EN
Amneal Pharmaceuticals (AMRX) Lifts 2026 Guidance, Is The 12% Undervalued View Enough?
Why Amneal Pharmaceuticals Is Back on Investors' Radar
Amneal Pharmaceuticals (AMRX) has drawn fresh scrutiny after raising its full year 2026 revenue outlook, even as the latest quarter mixed higher sales, a net loss, and new impairment charges.
The latest guidance hike and discussion of a larger biosimilars platform come after a choppy few weeks for Amneal Pharmaceuticals. The company has seen a 7-day share price return of 6.37% in the red, a 90-day gain of 12.64%, and a year-to-date share price return of 59.08%. This indicates that momentum has broadly been building over 2026, in line with a 1-year total shareholder return of 77.13% and a multi-year total shareholder return that has multiplied several times over for long-term holders.
Scan how Amneal Pharmaceuticals compares to other potential breakouts by reviewing a curated list of 38 high quality undervalued stocks with solid fundamentals and room for re-rating.
Bulls point to Amneal Pharmaceuticals lifting guidance and building a biosimilars platform, while bears focus on the recent quarterly loss and fresh impairments. Which side does the current valuation lean toward?
Most Popular Narrative: 12% Undervalued
The analyst consensus Narrative on Simply Wall St puts Amneal Pharmaceuticals at a fair value of $23, compared with the latest close at $20.14. That gap rests on a detailed view of how complex generics, biosimilars, and branded drugs could reshape the earnings mix under a 7.24% discount rate.
Amneal Pharmaceuticals is pursuing a deliberate shift toward complex generics such as transdermal patches, injectables, ophthalmics and drug device combinations. Management is targeting an additional US$1b to US$2b of Affordable Medicines revenue by 2030, which directly targets higher value revenue growth.
See why 20 investors see Amneal Pharmaceuticals as 12% undervalued.
Result: Fair Value of $23 (UNDERVALUED)
Still, the narrative around Amneal Pharmaceuticals can weaken if U.S. generics pricing pressure persists or if higher capital spending fails to translate into stronger profitability.
Find out about the key risks to this Amneal Pharmaceuticals narrative.
Another View: What Amneal Pharmaceuticals’ P/E Is Signalling
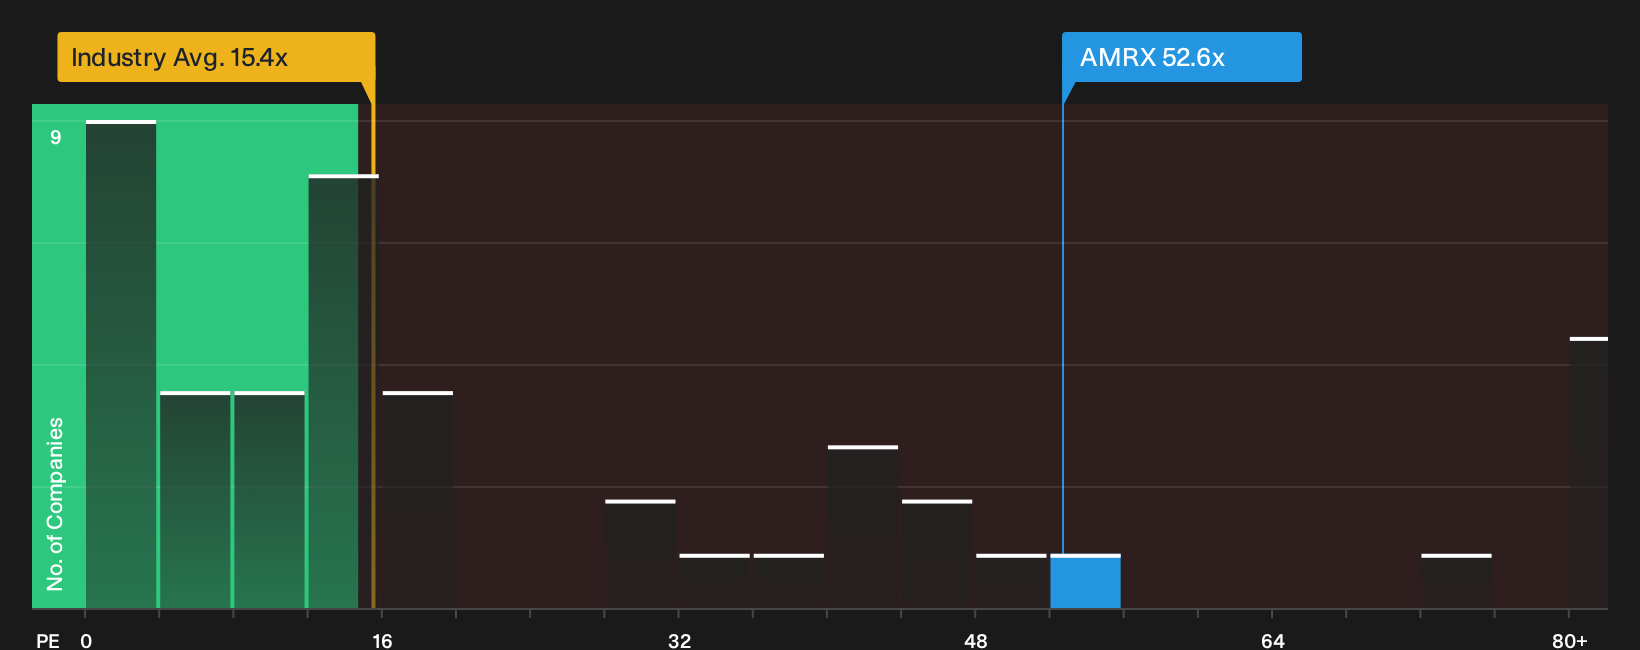
The SWS DCF model points to Amneal Pharmaceuticals trading well below an estimated future cash flow value of $79.78, yet the P/E ratio of 52.6x is far above the US Pharmaceuticals industry on 15.4x and a fair ratio of 34.5x. That gap suggests pricing risk is real even if the cash flow model flags upside, so which signal carries more weight for you?
See what the numbers say about this price in more detail, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Amneal Pharmaceuticals is clearly split, with real concerns and real optimism both in play. Move quickly, review the numbers yourself, and then weigh the 4 key rewards and 3 important warning signs
Looking for more investment ideas beyond Amneal Pharmaceuticals?
If Amneal Pharmaceuticals has your attention, do not stop here. Broaden your watchlist and pressure test your thesis against other potential opportunities.
- Target resilient compounding potential by scanning a curated 31 resilient stocks with low risk scores that keeps downside risk scores front and centre.
- Spot established payers by reviewing a focused group of 7 dividend fortresses that combine income potential with higher yield thresholds.
- Hunt for mispriced opportunities by sifting through a concentrated set of 19 high quality undiscovered gems before the crowd catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com