


EN
Healthpeak Properties (DOC) Just Gave Investors Something To Think About
Healthpeak Properties (DOC) just paired a third quarter earnings update with a trim to its full year 2026 profit outlook, putting both reported results and fresh guidance in focus for investors.
Recent trading suggests investors are reassessing Healthpeak Properties after the guidance cut. The share price is up 4.0% over the past week and 7.8% over the past month, yet the 90 day share price return is slightly negative. The 1 year total shareholder return of 22.3% contrasts with a 5 year total shareholder return that remains down 21.5%.
Spot fresh momentum stories around Healthpeak Properties by scanning a curated set of income focused real estate and defensive yield plays in our 7 dividend fortresses.Healthpeak Properties now trades at a clear discount to both intrinsic estimates and analyst targets after the guidance cut and share price rebound. Is that a valuation gap, or a warning signal investors should respect?
Most Popular Narrative: 10% Undervalued
Compared with the last close of $20.26, the analyst consensus Narrative on Simply Wall St anchors Healthpeak Properties at a fair value of $22.61, which implies a discount of about 10%. That view rests on detailed assumptions about future cash generation, earnings power and the 8.2% discount rate used in the model.
The current valuation implies that Healthpeak Properties' share price does not fully reflect the implied FFO yield above 10% on recent buybacks, the value ascribed to the Janus Living stake, or the earnings impact of capital recycling and lower leverage.
The main thing that has to go right is that Healthpeak Properties continues to execute on outpatient leasing spreads and occupancy, scales Janus Living as planned, and stabilizes life science NOI despite current pressure in the lab portfolio.
See why 36 investors see Healthpeak Properties as 10% undervalued.
Result: Fair Value of $22.61 (UNDERVALUED)
Still, the Healthpeak Properties story hinges on a lab recovery that has yet to fully show through, and on continued capital recycling and joint venture activity proceeding on current terms.
Find out about the key risks to this Healthpeak Properties narrative.
Another Take on Healthpeak Properties Valuation
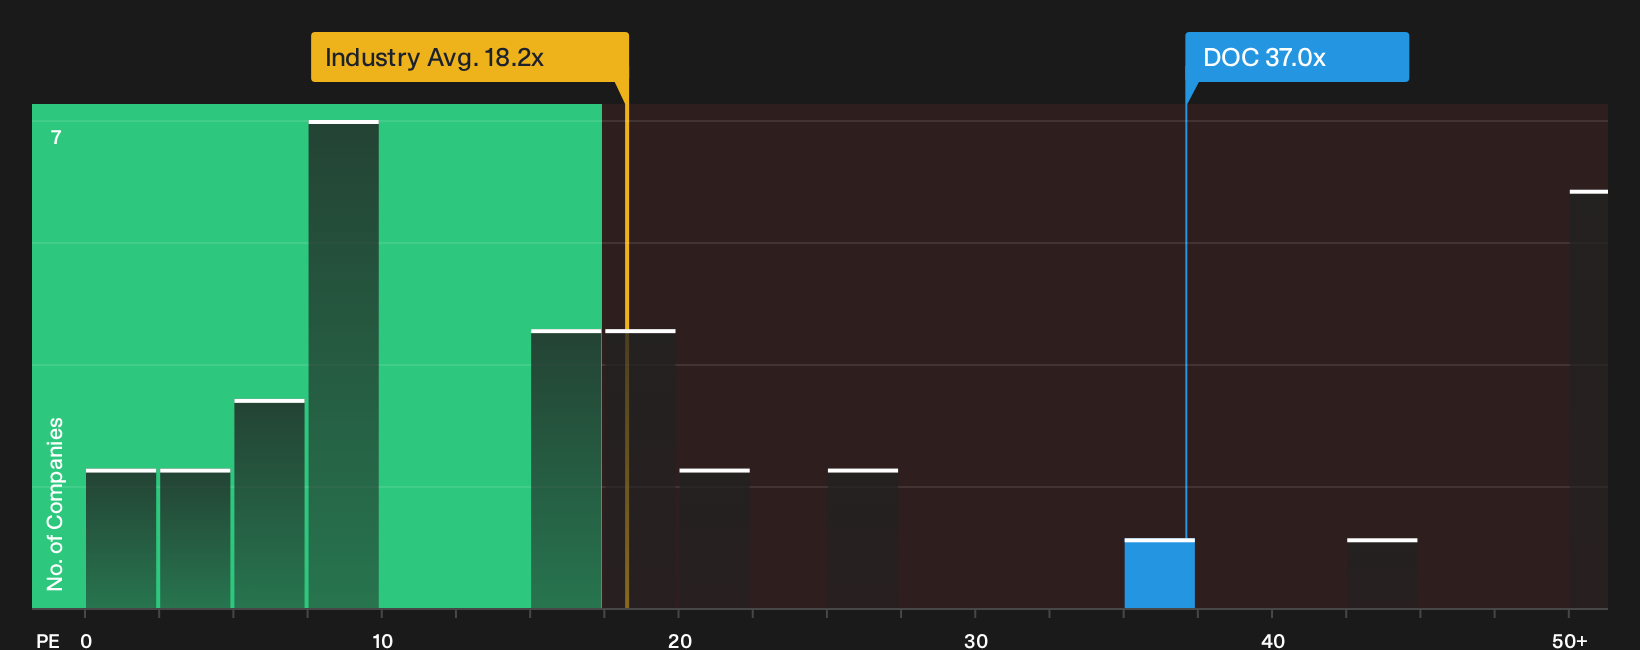
On simple earnings yardsticks, Healthpeak Properties screens less generous than the fair value story suggests. The stock trades on a P/E of 37x, while the global health care REIT group sits near 18.2x and the fair ratio points closer to 14.3x. That gap signals real multiple risk if sentiment cools.
Before leaning too hard on one approach, it helps to see what the numbers imply if the market drifts toward that fair ratio instead of the current premium, and what that would mean for your entry and exit discipline over time. See what the numbers say about this price — find out in our valuation breakdown. Explore the SWS fair ratio for Healthpeak Properties.
Next Steps
Mixed signals around Healthpeak Properties can feel confusing, so treat that tension as a prompt to move fast, study the full picture, and decide where you stand by weighing its 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Healthpeak Properties?
If Healthpeak Properties has you rethinking your next move, consider broadening your watchlist with a few focused idea sets built directly from the Simply Wall St Screener.
- Target steady compounders by scanning a 19 high quality undiscovered gems that combines quality fundamentals with quieter market attention.
- Reduce portfolio stress by filtering for a 31 resilient stocks with low risk scores that emphasizes resilient balance sheets and lower volatility profiles.
- Strengthen your income stream by exploring a 7 dividend fortresses built around higher yielding, income focused opportunities.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com