


EN
How Investors Are Reacting To Expedia Group (EXPE) Raised Revenue Guidance
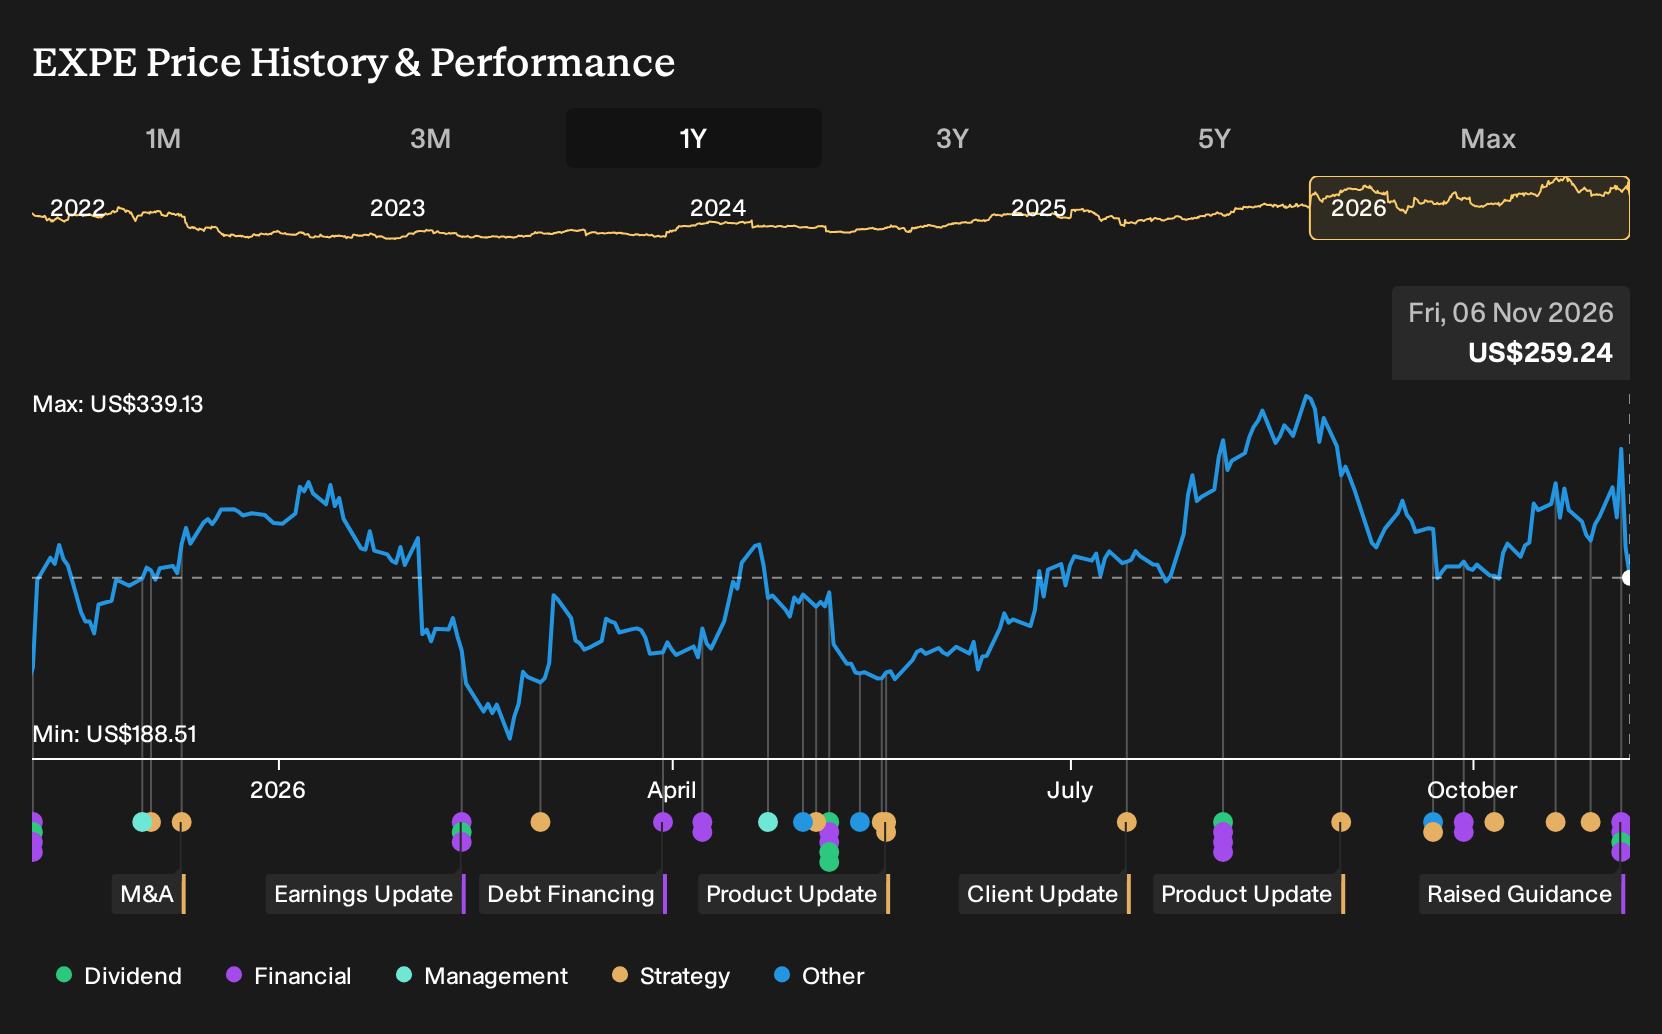
- Expedia Group reported third quarter 2026 revenue of US$4.94b and net income of US$1.03b, lifted earnings per share from continuing operations, raised full year 2026 revenue guidance to US$16.37b to US$16.43b, and affirmed a US$0.48 quarterly dividend payable on 10 December 2026.
- Alongside the stronger guidance, Expedia Group is rolling out more than 30 AI driven product upgrades across Expedia, Hotels.com, and Vrbo that focus on trip planning, personalization, and servicing, which ties operational progress to the financial momentum seen so far in 2026.
- Now the focus shifts to how Expedia Group's raised full year revenue outlook might reshape the existing investment narrative around AI, B2B growth, and margins.
Scan other travel and AI focused platforms showing similar momentum by reviewing the hand picked 41 profitable AI stocks that aren't just burning cash that may echo Expedia Group's blend of product rollouts and earnings strength.
Expedia Group Investment Narrative Recap
To own Expedia Group, you need to believe its mix of AI driven product upgrades, multi brand reach, and B2B relationships can keep turning healthy travel demand into consistent earnings, even as competition in online travel and new AI agents intensifies. The raised full year revenue outlook and confirmed Q4 guidance keep the near term story anchored on execution, not reinvention.
The most immediate catalyst is whether Expedia Group can translate these product changes and higher guidance into sustained booking and margin progress, while holding marketing efficiency. The main risk is that softer U.S. consumer travel or share loss to rivals caps B2C growth, which would blunt the benefit of its recent investments.
The dense cluster of more than 30 Expedia Group product updates around AI search, personalization, and servicing looks most relevant here, because it directly connects to what the analyst consensus Narrative on Simply Wall St highlights as key drivers: faster iteration and customer conversion. These tools touch core traveler journeys, from how people search for a stay to how they manage trips and resolve issues.
For catalysts, that matters more than any single quarter of guidance. If natural language search, Hotels.com AI Compare, and Vrbo’s AI voice agent improve conversion or reduce support costs at scale, they support the margin and earnings story sketched in analyst forecasts. Execution risk is clear, though: rivals are rolling out similar capabilities and any stumble in product quality or reliability could quickly erode that edge.
Expedia Group's narrative projects US$19.1b revenue and US$2.9b earnings by 2029. That path assumes 6.8% yearly revenue growth and an earnings increase of about US$0.9b from current earnings of roughly US$2.0b.
Uncover why Expedia Group's fair value indicates a 31% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One alternate view puts far more weight on marketing pressure. Before this earnings release, the most cautious analysts were only penciling in about US$18.8b of revenue and roughly US$2.4b of earnings by 2029 for Expedia Group. That is a much cooler story. Use this fresh guidance to test which camp you lean toward.
Explore 5 other Expedia Group fair value estimates, including one that suggests it could be worth just $251.38.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Expedia Group research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Expedia Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Expedia Group's overall financial health at a glance.
Looking for more Expedia Group style ideas?
If this Expedia Group update has sharpened your thinking, use the Simply Wall St Screener to pressure test that thesis against other companies with different strengths but similar financial clarity.
- For investors who want potential mispricing on their side, scan a curated 39 high quality undervalued stocks that pair solid fundamentals with prices the market has not fully rewarded yet.
- If balance sheet resilience matters most to you, focus on stability first by sifting through a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without relying on constant refinancing.
- When your priority is uncovering less crowded ideas, broaden your watchlist with a 19 high quality undiscovered gems that combine quality metrics with relatively low investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com