


EN
Exelixis (EXEL) Posts Stronger Earnings, Is The Stock Already 21% Overvalued?
Exelixis (EXEL) is back in focus after its latest quarterly report, which featured higher revenue, net income, and earnings per share compared with the same period a year earlier.
Exelixis shares have gained 16.22% over the past month and 35.53% over the last quarter, while the 1 year total shareholder return of 68% and 5 year total shareholder return of 285% reflect momentum that recent earnings and the ongoing buyback have reinforced.
Scan how Exelixis stacks up against other potential breakout ideas across our curated list of 19 high quality undiscovered gems to see what else fits your watchlist criteria.
After a 35% three month surge, Exelixis still screens at a large discount to some fair value estimates while trading above the average analyst target. Is the market being cautious for good reason, or mispricing the story?
Most Popular Narrative: 21% Overvalued
The analyst consensus Narrative on Simply Wall St sets Exelixis fair value at about $57.64 per share, which compares with a last close of $69.57. The framework already incorporates detailed revenue and earnings forecasts before rating the stock as overvalued.
The current view that Exelixis is fairly valued and bullish implies the share price already reflects a strong CABOMETYX cash engine, successful zanzalintinib approvals across key indications, and disciplined R&D and buyback-driven capital returns, without assigning much premium for additional potential beyond these elements.
See why 79 investors see Exelixis as 21% overvalued.
Result: Fair Value of $57.64 (OVERVALUED)
Still, the Exelixis story could shift quickly if cabozantinib faces a tougher patent or generic outcome, or if zanzalintinib’s regulatory path disappoints.
Find out about the key risks to this Exelixis narrative.
Another View on Exelixis Valuation
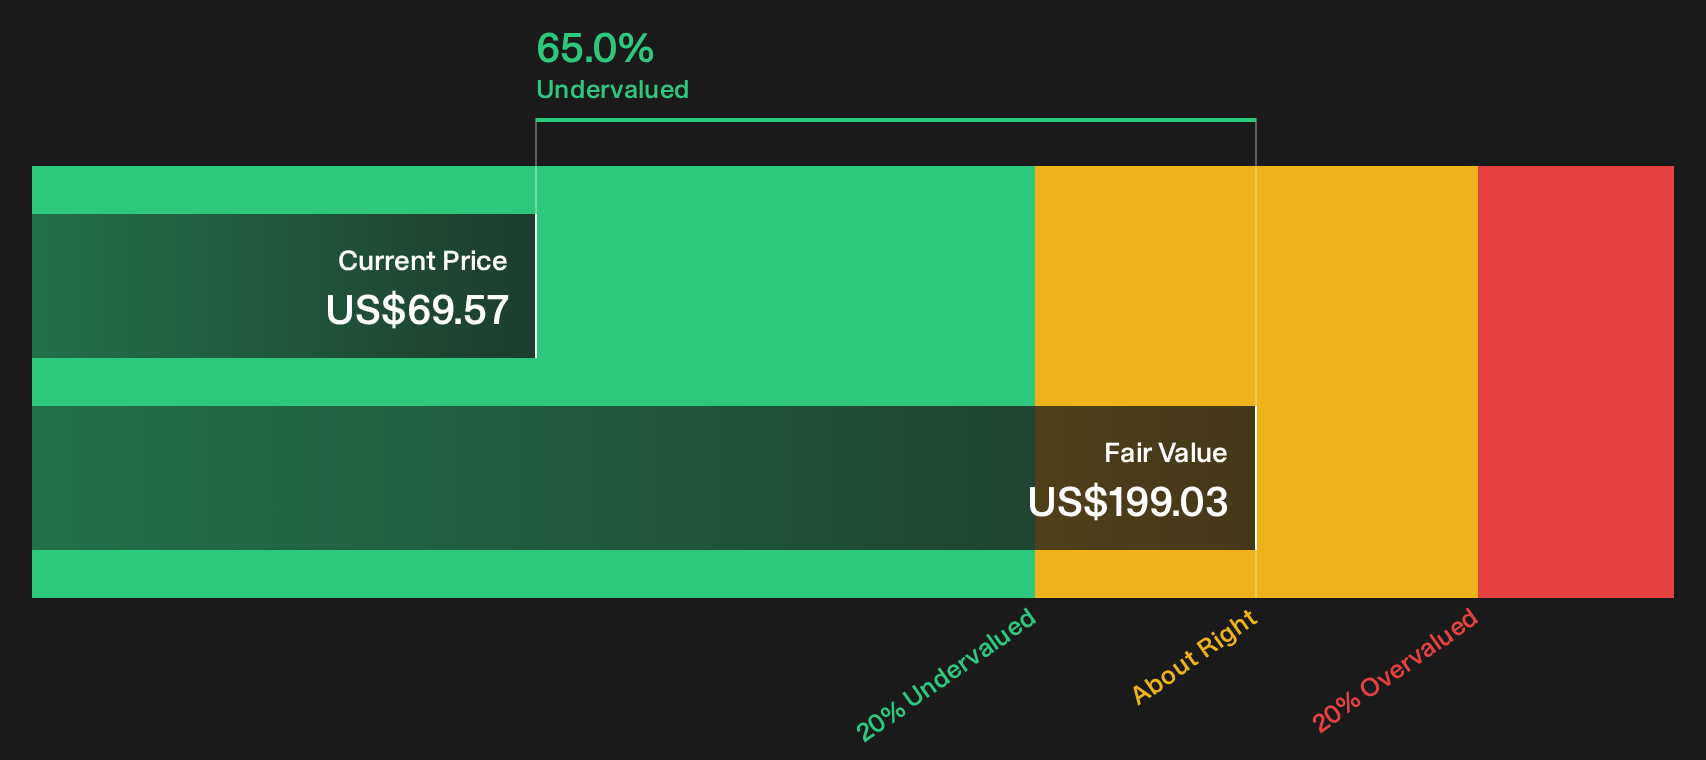
Analyst targets indicate Exelixis appears about 21% overvalued at $69.57, while the SWS DCF model values the same cash flows at approximately $199.03 per share. This implies the stock trades around 65% below that future cash flow estimate. The question is which perspective carries more weight: the market multiple or the model.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If you feel that Exelixis might be priced ahead of itself or still misunderstood, you can move quickly, compare that instinct with the available information, and weigh up 3 key rewards.
Looking for more investment ideas beyond Exelixis?
Do not stop your research with Exelixis. Broaden your field of vision and compare this story with other opportunities that might fit your style and risk comfort.
- Hunt for potential bargains that pair quality fundamentals with attractive pricing by scanning our 38 high quality undervalued stocks.
- Build a steadier income stream by focusing on companies in the 7 dividend fortresses that combine higher yields with resilient cash support.
- Prioritise capital preservation and smoother portfolio swings by filtering for businesses in the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com