


EN
Antero Midstream (AM) Stock Looks About Right On Its Earnings Story
Antero Midstream has delivered a powerful 151.0% share price gain over the past 5 years, yet the recent pullback raises a fresh question about what investors are really paying for its earnings today. With the stock now trading at US$18.98 after declines over the past week and month, the key issue is how that price lines up with the profits the business is currently generating.
- A 151.0% rise over 5 years has materially changed the entry price for Antero Midstream, so every move now leans more heavily on what its earnings can justify.
- The business model as a midstream operator can tie cash generation to long term contracts and capital spending needs. This may support a more stable earnings base but also makes the pay off period for investments crucial to any valuation built on profits.
- Your read on Antero Midstream is one view; the desks covering it have another. See what analysts think Antero Midstream's shares could be worth.
The issue now is whether Antero Midstream's current share price is supported by its earnings when set against a Fair Ratio benchmark.
If you want more context on whether Antero Midstream's recent pullback still lines up with its profit story, compare it with companies in the same conversation using 38 high quality undervalued stocks
Where Does Antero Midstream Sit on Earnings?
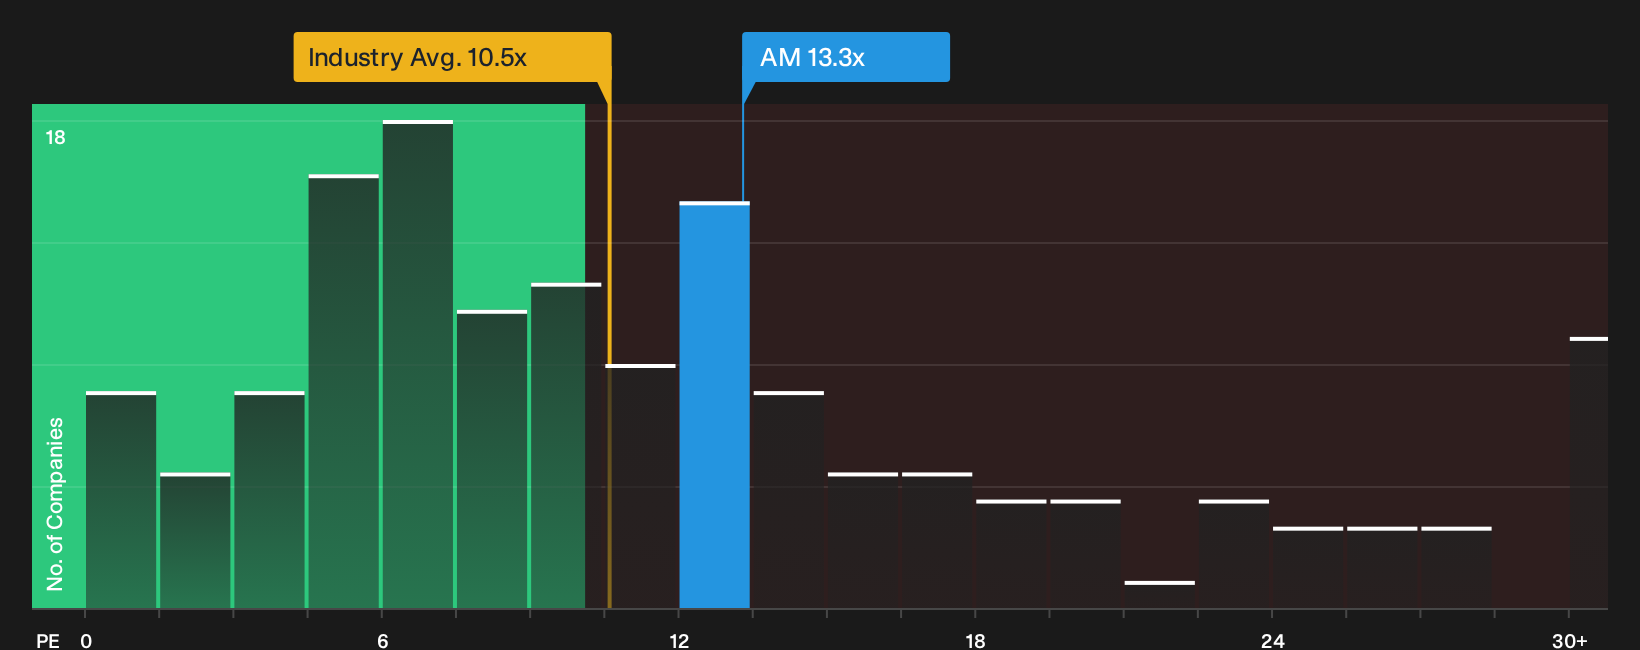
The P/E ratio suits Antero Midstream because investors often focus on the earnings power behind its fee based midstream model. On this lens, the stock trades on a P/E of 13.3x, compared with an Oil and Gas sector average of 10.5x and a peer group around 15.3x, so the shares change hands at a premium to the broader industry but a discount to closer comparables.
The Fair Ratio, which reflects what the market might typically pay for Antero Midstream given its risk profile, profitability and scale, points to a level very close to where the current P/E sits. That keeps the earnings multiple in a zone where small changes in expectations around contract quality, capital intensity or future cash generation can tip the debate either towards the stock looking overvalued or undervalued. To test whether that knife edge works in your favour, you need to weigh the current price against the full earnings and cash flow picture behind Antero Midstream. Explore the numbers behind Antero Midstream's P/E valuation.
The Antero Midstream Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle leaves off for Antero Midstream by spelling out the specific earnings, growth and margin paths that would need to play out for the stock to be worth materially more or less than it is today. Each one links its number to a clear view on where Antero Midstream's growth, profitability and risks could move next so you can come back to that thesis as fresh information arrives on the Community page.
One of the top narratives on Antero Midstream: 21% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Rising in basin natural gas demand from new West Virginia gas fired power plants and data centers is expected to increase throughput on Antero Midstream’s gathering and intrastate pipeline system over time…"
Discover why this Narrative puts Antero Midstream at 21% undervalued.
The share price is only one question for Antero Midstream investors
Before you anchor too heavily on Antero Midstream’s P/E and narrative, it is worth checking the specific risk checks that have raised flags in our work, then weighing those for yourself. Take a closer look at 4 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com