


EN
Hershey (HSY) Raises Full Year Guidance, Is The Upside Already Priced In?
Hershey (HSY) just paired upbeat third quarter results with a higher full year outlook, giving investors fresh numbers to weigh against recent share gains and the stock's longer term total return profile.
The recent 1 month share price return of 9.4% suggests momentum has picked up as investors react to Hershey’s stronger earnings, raised full year guidance and a refreshed 2026 holiday product lineup. However, the 3 month share price return is still down 2.1% and the 1 year total shareholder return is 8.6%.
Compare Hershey’s latest move against a curated group of resilient consumer stocks using the 31 resilient stocks with low risk scores to see which businesses combine steadier risk profiles with recent momentum.
Bulls point to Hershey’s stronger earnings and higher guidance, while bears focus on muted multiyear returns and a full valuation. Which story do the current numbers support as you weigh what today’s price implies?
Most Popular Narrative: 125% Overvalued
Hershey last closed at $178.08, while the leading narrative on the stock pegs fair value far lower at $79.25, creating a wide gap for investors to assess. According to Esteban, an investor in the Simply Wall St Community who wrote the narrative, the key question is whether Hershey’s quality justifies that premium or whether the price overreaches what the business can reasonably deliver.
A fortress brand and scale position in U.S. confectionery (Reese’s, Hershey’s, Kisses) generates ~23% through-cycle ROIC and exceptionally durable free cash flow that fell only ~13% even in the worst input-cost year on record. The 2025 cocoa shock, a ~60% GAAP EPS collapse driven largely by non-cash hedge mark-to-market, obscured an underlying cash engine that remained intact.
See why 6 investors see Hershey as 125% overvalued.
Result: Fair Value of $79.25 (OVERVALUED)
Still, if cocoa costs stay elevated for longer than expected or GLP-1 appetite trends accelerate, Hershey’s current valuation narrative could be challenged.
Find out about the key risks to this Hershey narrative.
Another View on Hershey’s Valuation
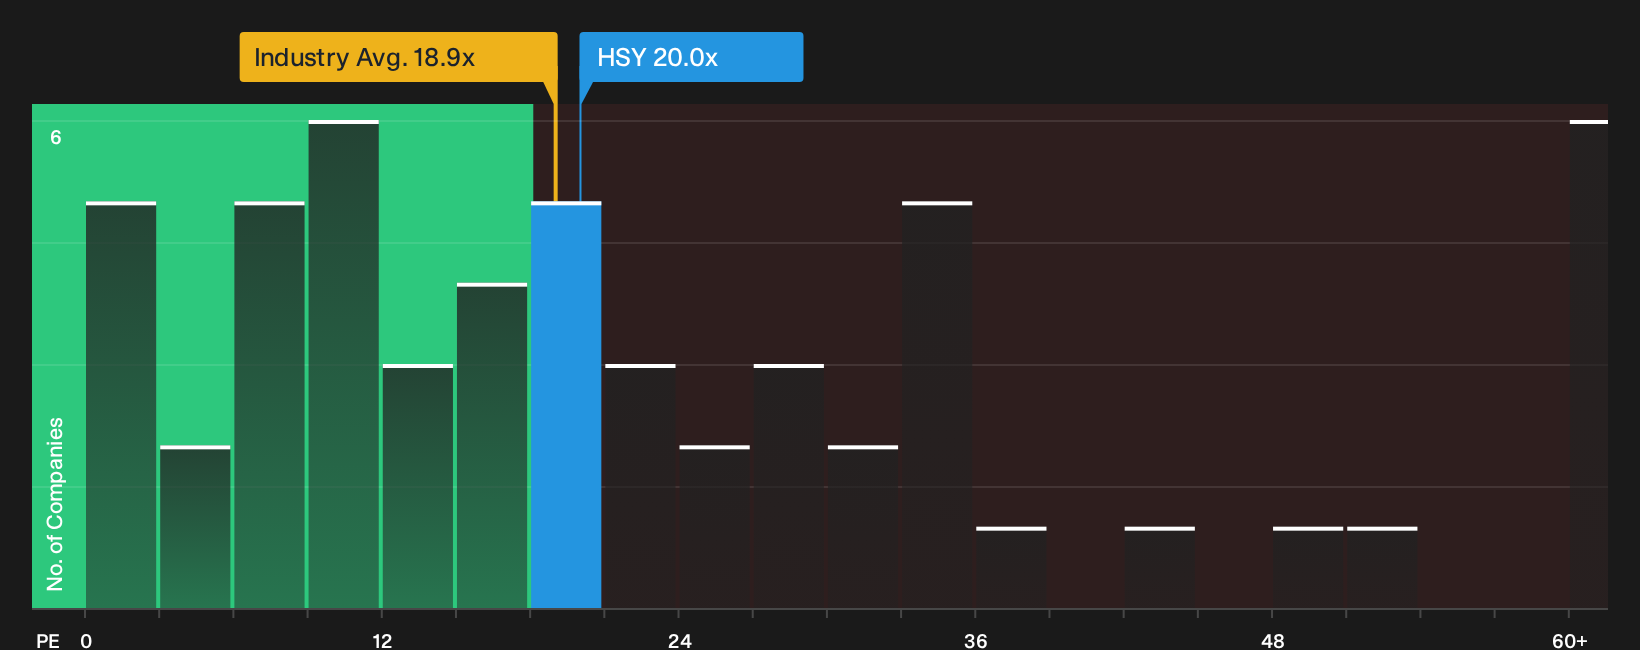
That 125% overvaluation call sits awkwardly next to one of the simplest cross-checks investors use. On a P/E of 20x, Hershey trades below peer averages of 31.6x, slightly above the wider US Food group at 18.9x and almost on top of an estimated fair ratio of 20.2x. Does that look like excess optimism or something closer to a middle ground you could justify?
See what the numbers say about this price in our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Hershey’s valuation and risk profile can pull you in opposite directions, so move fast, review the data firsthand, and weigh the 4 key rewards and 1 important warning sign.
Looking for more Hershey sized investment ideas?
If Hershey has sharpened your focus on quality and price, do not stop here. Broaden your watchlist now or risk missing tomorrow’s standouts.
- Explore potential opportunities by scanning a hand picked pool of attractively priced companies through the 38 high quality undervalued stocks.
- Review a shortlist of higher yielding payers using the 7 dividend fortresses to assess potential additions to your income stream.
- Filter for sturdier balance sheets and cleaner fundamentals with the list of solid balance sheet and fundamentals (25 results) to help support capital preservation goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com