


EN
Did Lotus Bakeries' 86% Run Pass You By? What The Bulls Got Right
If you only glanced at Lotus Bakeries headlines during the year, the story might have looked straightforward. For Lotus Bakeries shareholders, the return over the past year was 86.3%, including dividends. Yet the starting point in November 2025 was anything but simple, with bullish voices focused on Mondelez partnerships and a Thailand plant, and skeptics worried about regulation, health trends, and Biscoff concentration. If you were weighing those arguments then, what truly tipped the scales?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Lotus Bakeries has already moved. See which of 226 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Were Weighing On Lotus Bakeries
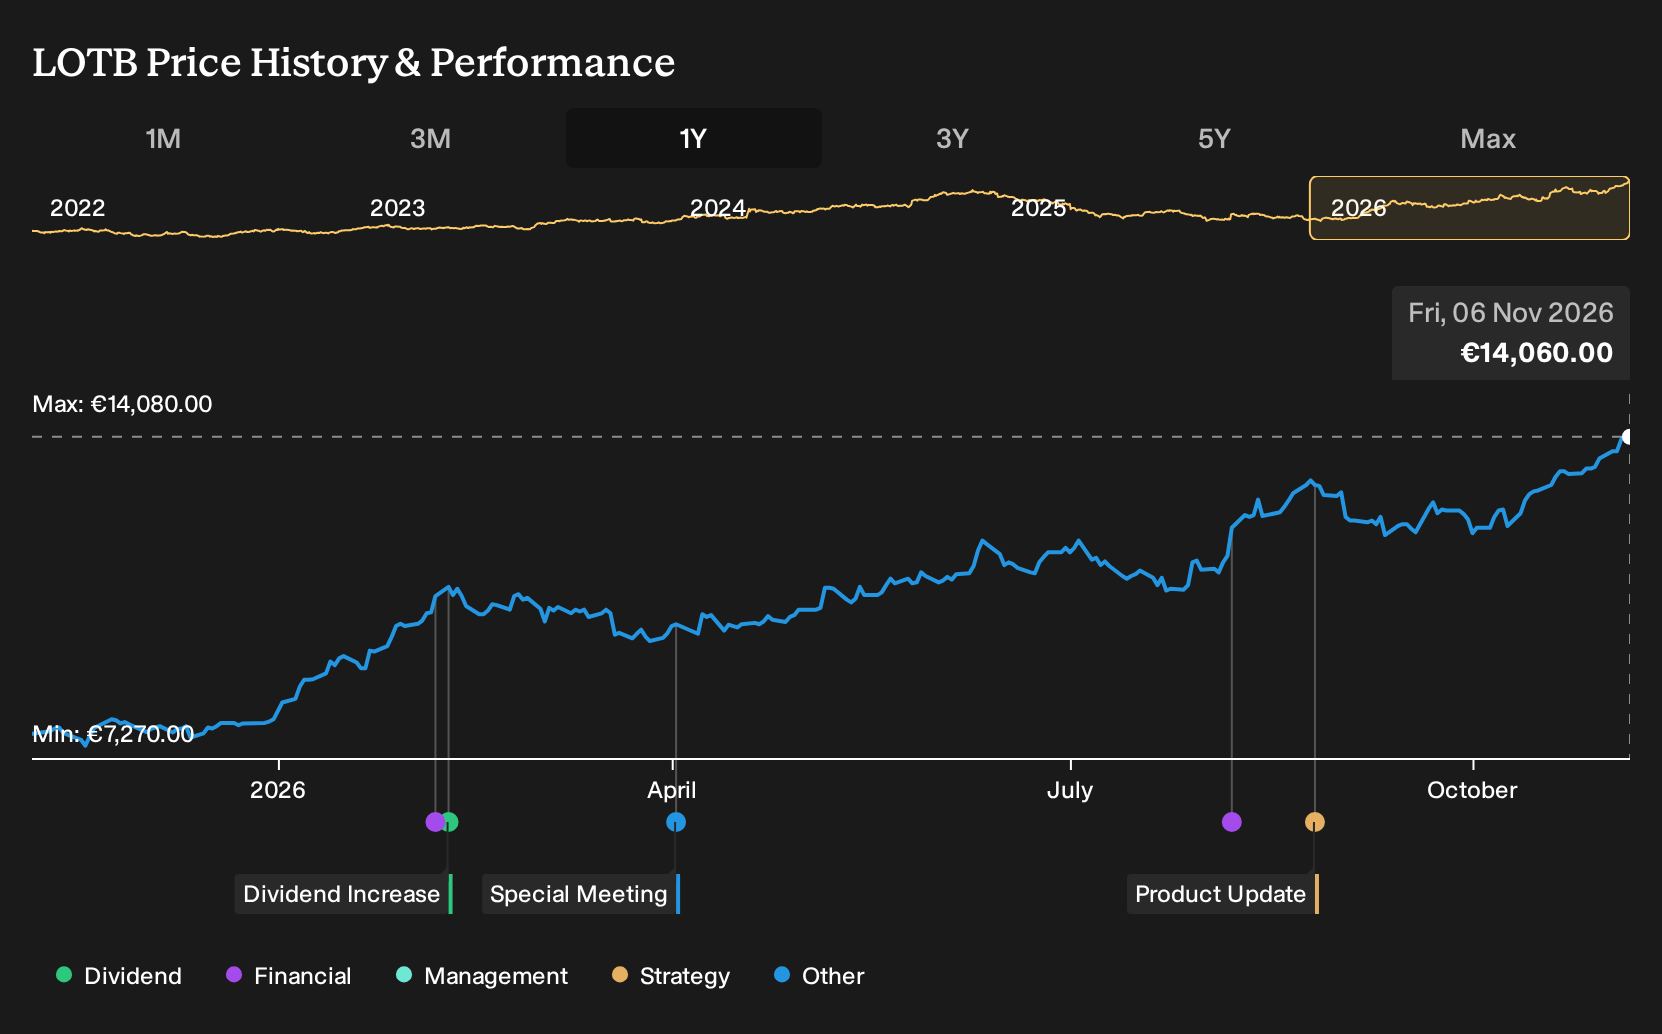
The shares cost €7,530 at the start of the period, and anyone eyeing Lotus Bakeries then was really choosing between two sharply different stories about where things might go next.
On the optimistic side, one Narrative saw the Mondelez partnership and the planned Thailand plant widening global reach, with a Fair Value of €9,636. That view leaned on assumed 10.2% annual revenue growth and a profit margin rising to 13.0% over three years.
The more cautious Narrative focused on regulation and health demands pressuring core products, putting Fair Value at €6,731. That case still assumed 8.3% yearly revenue growth, but flagged Biscoff concentration and rising compliance and supply chain costs as key threats.
What The Results Changed For The Lotus Bakeries Debate
Lotus Bakeries then announced a €500 million Biscoff expansion plan and reported H1 2026 revenue of €749.093 million and net income of €98.08 million. Net margin moved from 12.1% in H1 2025 to 13.1%. That combination, together with news of extra capacity in Belgium, Thailand and the US, largely supported the optimistic reach and profitability story, while leaving regulation worries untested.
The hinge assumption here was whether volume and margin could move together. When you assess another consumer stock, compare that claim with revenue, absolute profit and net margin in the next full reporting period.
What Lotus Bakeries' Run Up 86% Already Prices In
Lotus Bakeries now trades at €14,060 after an 86.3% gain over the past year. The current Narrative on the stock puts Fair Value below that level, which signals a view that recent enthusiasm may already build in demanding expectations.
According to StoxEurope, a Simply Wall St Community investor who wrote the Narrative, you would need to decide whether long term returns on today’s heavy capacity spend can justify this price, since a buyer now effectively leans on future utilisation of those new Biscoff lines.
"The uncertainty that matters most This estimate assumes that investment after year five earns only its cost of capital; if capacity already paid for by 2030 produces additional profit after 2030, the base understates the value, because Lotus does not say how full the halls will be at the end of 2030, so no figure is claimed."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Looking One Step Beyond Lotus Bakeries
Lotus Bakeries highlights how much can rest on brand power and distribution reach. You might ask what supports that kind of reach from another angle.
Snack buyers often want familiar treats and a drink together. That habit creates ongoing demand for broad beverage and packaged food ranges.
One large global group focuses on exactly that combination. It supplies drinks and convenient foods that fill shelves across supermarkets and other outlets.
Those baskets can move differently to premium biscuits like Lotus Biscoff. If you are thinking about consumer exposure, that contrast may be worth a closer look.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 42% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com