


EN
How Lowered Earnings Guidance At Mercedes Benz Group (XTRA:MBG) Has Changed Its Investment Story
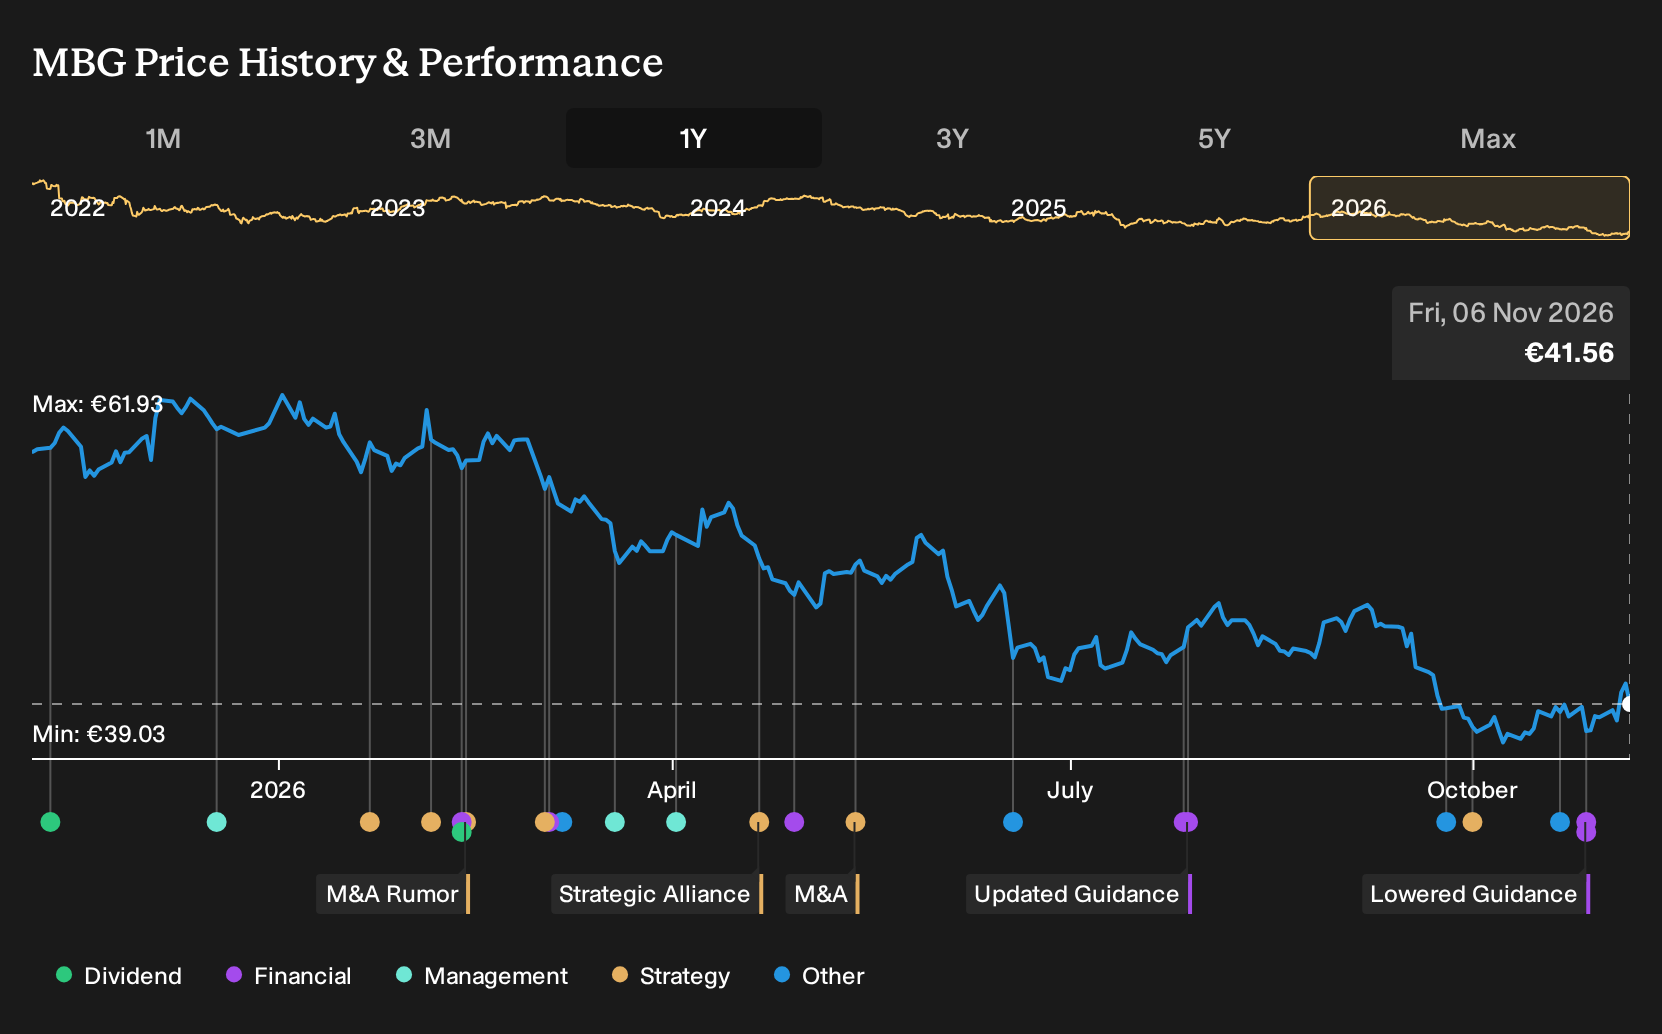
- Mercedes-Benz Group reported Q3 2026 sales of €25,111 million and net income of €1,518 million, then later cut full year 2026 EBIT guidance to the prior year level, citing tougher conditions in China and higher material costs in the fourth quarter.
- The combination of softer sales and reduced guidance highlights how Mercedes-Benz Group is wrestling with cost inflation and Chinese demand pressure, even as earnings per share from continuing operations for both the quarter and nine month period were reported above the prior year figures.
- We will look at how Mercedes-Benz Group's investment narrative is tested by the lowered 2026 EBIT outlook tied to pressures in China.
Mercedes-Benz Group Investment Narrative Recap
To own Mercedes-Benz Group, you need to be comfortable with a premium auto business that is trying to shift more value into software, electrified models and cost efficiency, as described in the analyst consensus Narrative on Simply Wall St. The cut to 2026 EBIT guidance pulls the focus back to execution risk. The key near term catalyst is whether management can still deliver planned cost and productivity gains fast enough to counter higher material costs.
The biggest risk right now sits in China and broader pricing pressure. Management already guided to slightly lower 2026 deliveries and revenue, and the latest outlook reinforces that demand and tariffs can still compress returns. If China pressure persists or tariffs and FX knock another turn off margins, the current cost and product roadmap will feel tighter.
The most relevant announcement here is the Q3 2026 result and the updated full year 2026 outlook. Sales for the quarter were €25,111 million, with net income of €1,518 million and earnings per share from continuing operations of €1.64. For the nine months, revenue was €76,489 million and net income reached €4,001 million, with earnings per share of €4.27.
Those figures give you two competing signals to weigh. On one side, profitability from continuing operations held up in the period, which supports the longer term catalysts around MB.OS, higher xEV mix and planned fixed cost cuts. On the other side, the reset of EBIT expectations to the prior year level underlines that tariffs, FX and China weakness can still overpower those levers in the short run.
Mercedes-Benz Group's narrative projects €137.2b revenue and €6.8b earnings by 2029. That path assumes revenue expands by 1.9% a year and earnings increase by €1.8b from €5.0b today to reach the 2029 consensus figure.
Uncover how Mercedes-Benz Group's fair value indicates a 28% potential upside to its current price, which could narrow quickly as sentiment catches up.
Exploring Other Perspectives
One big swing factor that bearish analysts focus on is long term profitability at Mercedes-Benz Group. Before this guidance cut, the lowest forecasts were already baking in flat revenue near €129.2b by 2029 and earnings easing toward €5.2b. That is a much more cautious story than consensus and could shift again after this update. Treat it as one lens and compare several viewpoints yourself.
Explore 4 other Mercedes-Benz Group fair value estimates, including one that suggests as much as 17% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Mercedes-Benz Group research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Mercedes-Benz Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mercedes-Benz Group's overall financial health at a glance.
Looking for more investment ideas beyond Mercedes-Benz Group?
Once the Mercedes-Benz Group story is clear in your mind, it can help to widen the lens and compare it with other opportunities that match your risk tolerance, income needs, or focus on financial resilience using the Simply Wall St Screener.
- If you want strong fundamentals with fewer balance sheet surprises, scan a 207 resilient stocks with low risk scores that have historically scored well on financial resilience checks.
- For investors hunting for value, a curated 226 high quality undervalued stocks can help you spot businesses where fundamentals and current pricing look out of sync.
- If growing passive income is your priority, use a 227 dividend fortresses to find higher yielding companies that may warrant a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com