


EN
Why Kakao Fell Even As Sales Rose
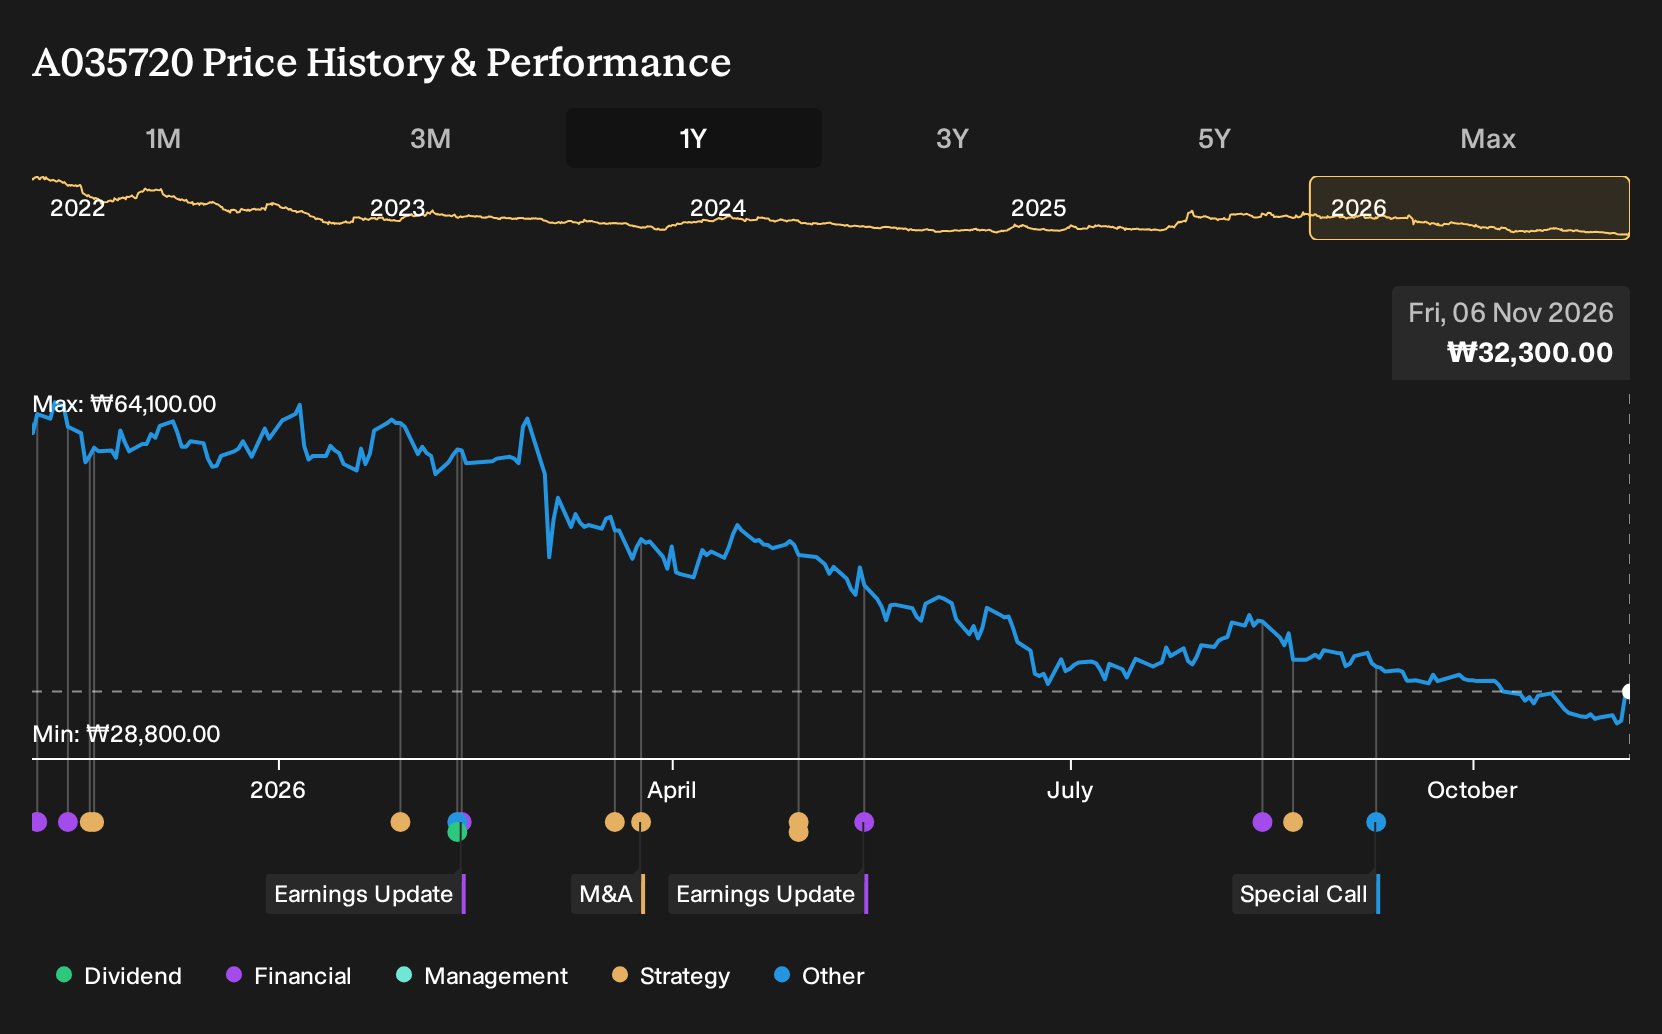
If you only glanced at Kakao’s headlines, recent revenue growth alongside rising AI and fintech ambitions might have looked like the start of a new leg higher. For Kakao shareholders, the loss over the past year was 48.5%, including dividends. If you had been weighing an entry back in November 2025, the real puzzle is whether weaker net income and a slipping margin were already hinting that something in the super app story did not quite add up.
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Kakao. Zero in on 226 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Had To Weigh On Kakao
The shares cost ₩60,800 at the start of the period, and anyone looking at Kakao then had to choose between two very different stories that both sounded reasonable.
On the bullish side, the Fair Value was set at ₩86,333, based on the idea that proprietary multimodal and on-device AI, together with a fully owned data center, could lift revenue growth and net margins across the whole super app ecosystem.
The bearish narrative put Fair Value at ₩41,917, emphasizing that tighter data privacy rules and antitrust scrutiny in South Korea might restrict data monetisation and increase compliance costs over time.
What The Results Changed For Kakao
The most telling update came from the Q2 2026 figures. Kakao reported revenue of ₩2,098,456.1m, up from ₩1,917,469.7m a year earlier, which leaned toward the optimistic growth story. Net income slipped to ₩194,276.6m from ₩206,130.2m and net margin moved from 10.8% to 9.3%, which challenged the bullish profitability assumptions. The evidence cut both ways.
The lesson is simple. When a growth story leans on margin expansion, do not just track sales. Watch whether net income and the reported net margin move in the same direction as the pitch.
What Kakao’s Lower Price Is Asking You To Believe
With Kakao now at ₩32,300, the analyst consensus Narrative on Simply Wall St places its Fair Value above that level, based on a heavier weighting to KakaoTalk, AI services and higher-margin digital ads.
For that higher figure to make sense, a buyer today would need to believe KakaoTalk can convert AI-driven engagement into material, profitable revenue growth while holding infrastructure costs in check.
"The current valuation suggests that the market is focusing more on near-term execution risk in AI, advertising mix, and non-core segments rather than on the potential upside from a higher-margin, KakaoTalk-centered ecosystem."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Which Company Could Surprise You Next?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 17% below our estimate - sells automated cooking systems as kitchens adopt resource efficient technology and digital control.
- Company 2 - 15% below our estimate - scales an asset light legal platform as senior lawyers choose flexible, self employed structures.
- Company 3 - 25% below our estimate - expands a probiotics portfolio as adult and oral health products gain traction in direct channels.
Three companies from the same screener. Open every one of the 193 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com