


EN
Pfizer (PFE) Lifts Guidance Following Pipeline Wins While Fair Value Looks Near Reach
Pfizer (PFE) just lifted its 2026 revenue guidance by US$1.5b to a range of US$62b to US$64b, a move that puts earnings expectations, cancer drugs, and AI partnerships firmly in focus for shareholders.
Pfizer’s raised guidance lands after a mixed stretch for the shares, with the 1-day and 7-day share price returns down 1.64% and 4.17% respectively. At the same time, a 10.41% 90-day share price gain and 28.57% 1-year total shareholder return highlight investor focus on the drug pipeline, new AI partnerships and recent approvals in oncology and prostate cancer.
Scan beyond Pfizer and size up other large drug makers with a 31 resilient stocks with low risk scores that filters for balance sheet strength and more resilient earnings profiles.
After a strong 1-year return and a higher 2026 revenue range, Pfizer now looks more like a recovery story than a contrarian bet. Does the current valuation still leave enough upside to compensate for the risks?
Most Popular Narrative: 1% Undervalued
Pfizer’s last close at $29.39 sits just below the analyst consensus Narrative fair value of $29.72, which the analyst consensus Narrative on Simply Wall St builds from detailed earnings and revenue forecasts using a 7.24% discount rate.
Expansion of launched and acquired products, which management now describes as running at around a US$13b annualized revenue rate and growing in the 20% range, continues to support the view that Pfizer can further shift its mix toward non COVID therapies and sustain revenue as loss of exclusivity pressures emerge.
See why 563 investors see Pfizer as 1% undervalued.
Result: Fair Value of $29.72 (ABOUT RIGHT)
Still, the Pfizer story can be knocked off course if drug pricing reforms bite harder than expected or if key pipeline drugs fall short of current expectations.
Find out about the key risks to this Pfizer narrative.
Another View: Pfizer On Earnings Multiples
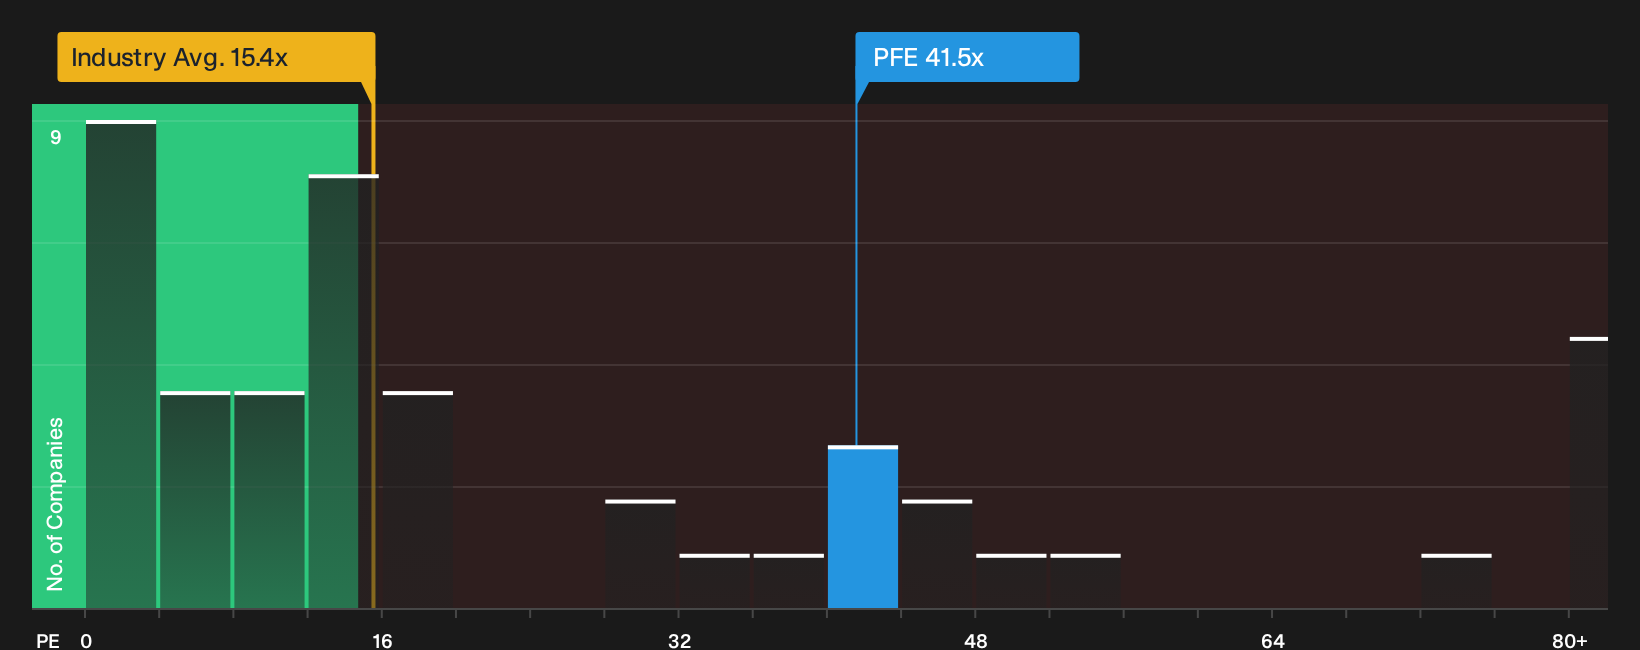
The fair value narrative for Pfizer at $29.72 leans on future earnings forecasts and discount rates. A quick check against today’s P/E tells a sharper story. The stock trades at about 41.5x earnings, while the US Pharmaceuticals group sits nearer 15.4x and the fair ratio sits around 31.9x.
That gap suggests the market already prices in more earnings strength for Pfizer than both the sector and the fair ratio imply. This raises a simple question for investors: Are you comfortable paying a richer multiple for this pipeline and cost saving plan, or would you rather wait for the valuation to line up more closely with peers and the fair ratio?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on valuation and sentiment can make Pfizer hard to read at a glance. Move quickly, test the data for yourself, and pressure test both the upside and the weak spots using our breakdown of 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Pfizer?
If Pfizer already sits on your radar, do not stop there. Broaden your watchlist with a few focused stock ideas that match your risk and income preferences.
- Target potential value opportunities by focusing on companies that pair quality fundamentals with pricing that still looks reasonable using our 38 high quality undervalued stocks.
- Strengthen your income stream by zeroing in on businesses that offer higher yields and more durable payouts through our 7 dividend fortresses.
- Dial down portfolio stress by concentrating on companies that carry healthier balance sheets and steadier fundamentals using the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com