


EN
CoStar Group (CSGP) Stock Dropped, What Is Behind Its Latest Move?
CoStar Group (CSGP) just paired a swing back to profitability in the third quarter of 2026 with fresh guidance that outlines expected revenue ranges for both the fourth quarter and the full year.
Despite the profit return and updated guidance, CoStar Group’s share price tells a more cautious story. The 1-day share price return declined 4.68%, and the year-to-date share price return fell 53.49%, contributing to a 1-year total shareholder return that declined 54.75%. This points to momentum that remains weak even after recent quarterly gains.
Scan beyond CoStar Group and review other real estate and property-focused companies that currently screen well using the list of solid balance sheet and fundamentals (25 results).
CoStar Group has returned to profit while the share price has been reset hard. Does that selloff leave enough upside potential to justify the risks at today’s valuation?
Most Popular Narrative: 15% Undervalued
CoStar Group’s most followed narrative pegs fair value at $35.85, above the last close of $30.55. This frames the recent selloff as a valuation reset rather than a straightforward verdict on the business.
The key thing that has to go right is that CoStar Group turns Homes.com, Apartments.com, Zonda, international portals and AI products into a durable, profitable multi-vertical platform, despite muted bookings, lower revenue guidance and competitive pressure in multifamily advertising.
The current valuation of CoStar Group implies that the market is discounting execution risk around revenue growth, Homes.com scalability and AI disruption more heavily than the recent uplift in margins and record adjusted EBITDA guidance. This underpins the view that the stock is undervalued and that the narrative is bullish.
See why 32 investors see CoStar Group as 15% undervalued.
Result: Fair Value of $35.85 (UNDERVALUED)
Still, the bullish CoStar Group narrative relies on some fragile assumptions, particularly around muted net new bookings and pressure on Apartments.com pricing power.
Find out about the key risks to this CoStar Group narrative.
Another View: CoStar Group Through The P/E Lens
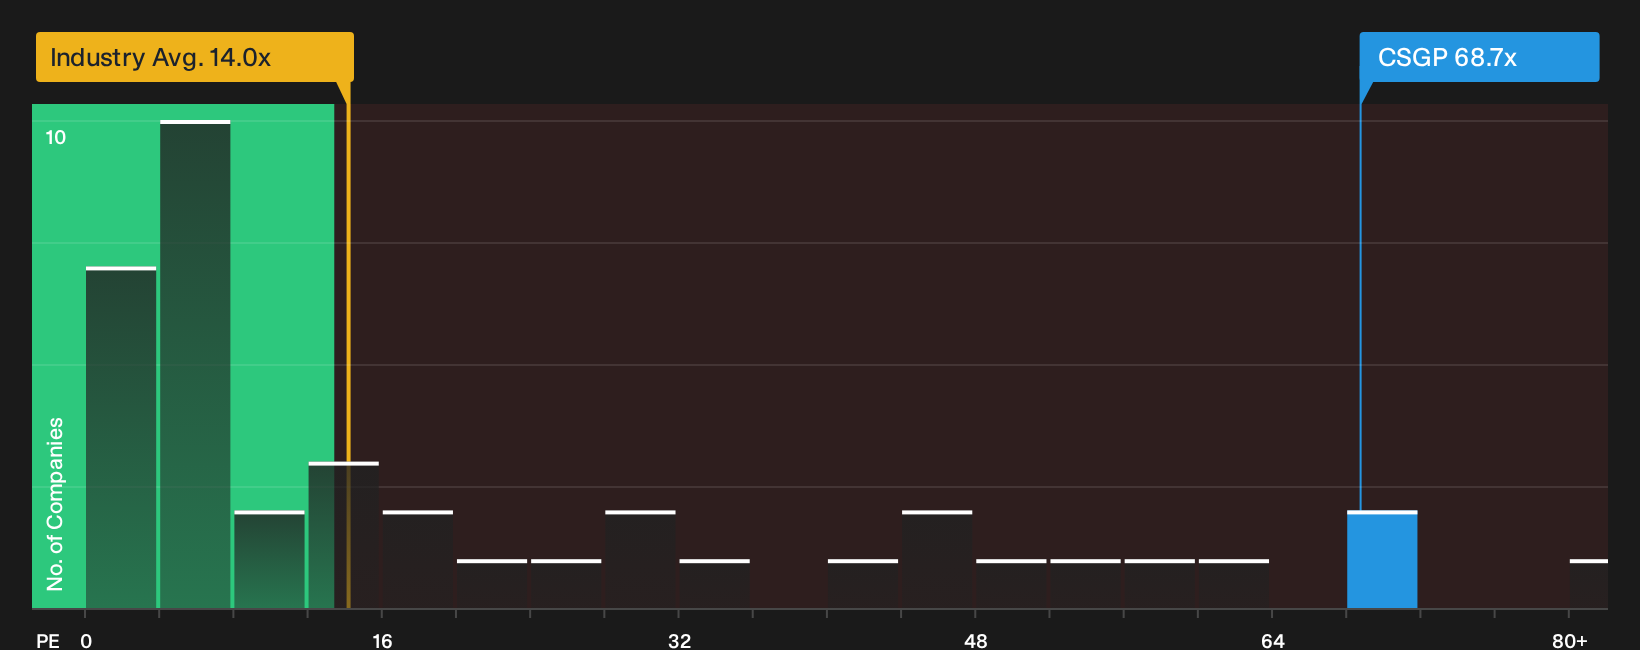
The first narrative leans on future cash flows and a fair value of $35.85. Using the current P/E tells a different story. CoStar Group trades on 68.7x earnings, well above the US Real Estate industry at 14x and peers at 33x, and also above a fair ratio of 38.7x.
That kind of gap suggests investors are already paying a heavy premium for execution, even with the share price reset. The question is whether you see that premium as justified optionality, or valuation risk if growth or margins land closer to the industry pack. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around CoStar Group can either be a warning or an opportunity, and the difference comes down to how you read the numbers and risks. If you want to see what optimistic investors are focusing on, take a close look at the 3 key rewards.
Looking for more investment ideas beyond CoStar Group?
Do not stop your research with CoStar Group alone. The real edge often comes from comparing several high quality opportunities side by side before committing capital.
- Target robust balance sheets and steadier fundamentals by scanning a curated list of solid balance sheet and fundamentals (25 results) that filters for financial strength.
- Hunt for potential mispricings by reviewing a focused 38 high quality undervalued stocks that highlights stocks where quality and valuation may be out of sync.
- Prioritise resilience and capital protection by checking a hand picked 31 resilient stocks with low risk scores that concentrates on companies with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com