


EN
Does Quarterly Earnings Change The Bull Case For AXIS Capital Holdings (AXS)?
- AXIS Capital Holdings reported third quarter 2026 results with revenue of US$1,789.93 million and net income of US$209.08 million, alongside a buyback that retired 1.46% of shares during the period.
- The business paired higher year to date revenue and slightly higher nine month net income with a completed US$146.63 million repurchase that reduced the share count by 1.97%, which tightened per share exposure to its specialty insurance and reinsurance earnings profile.
- We will now see how AXIS Capital Holdings' latest earnings and share repurchase activity could shape the existing investment narrative.
Compare AXIS Capital Holdings' latest earnings and buyback with a curated group of insurers and financials showing resilient fundamentals in today's market using list of solid balance sheet and fundamentals (25 results).
AXIS Capital Holdings Investment Narrative Recap
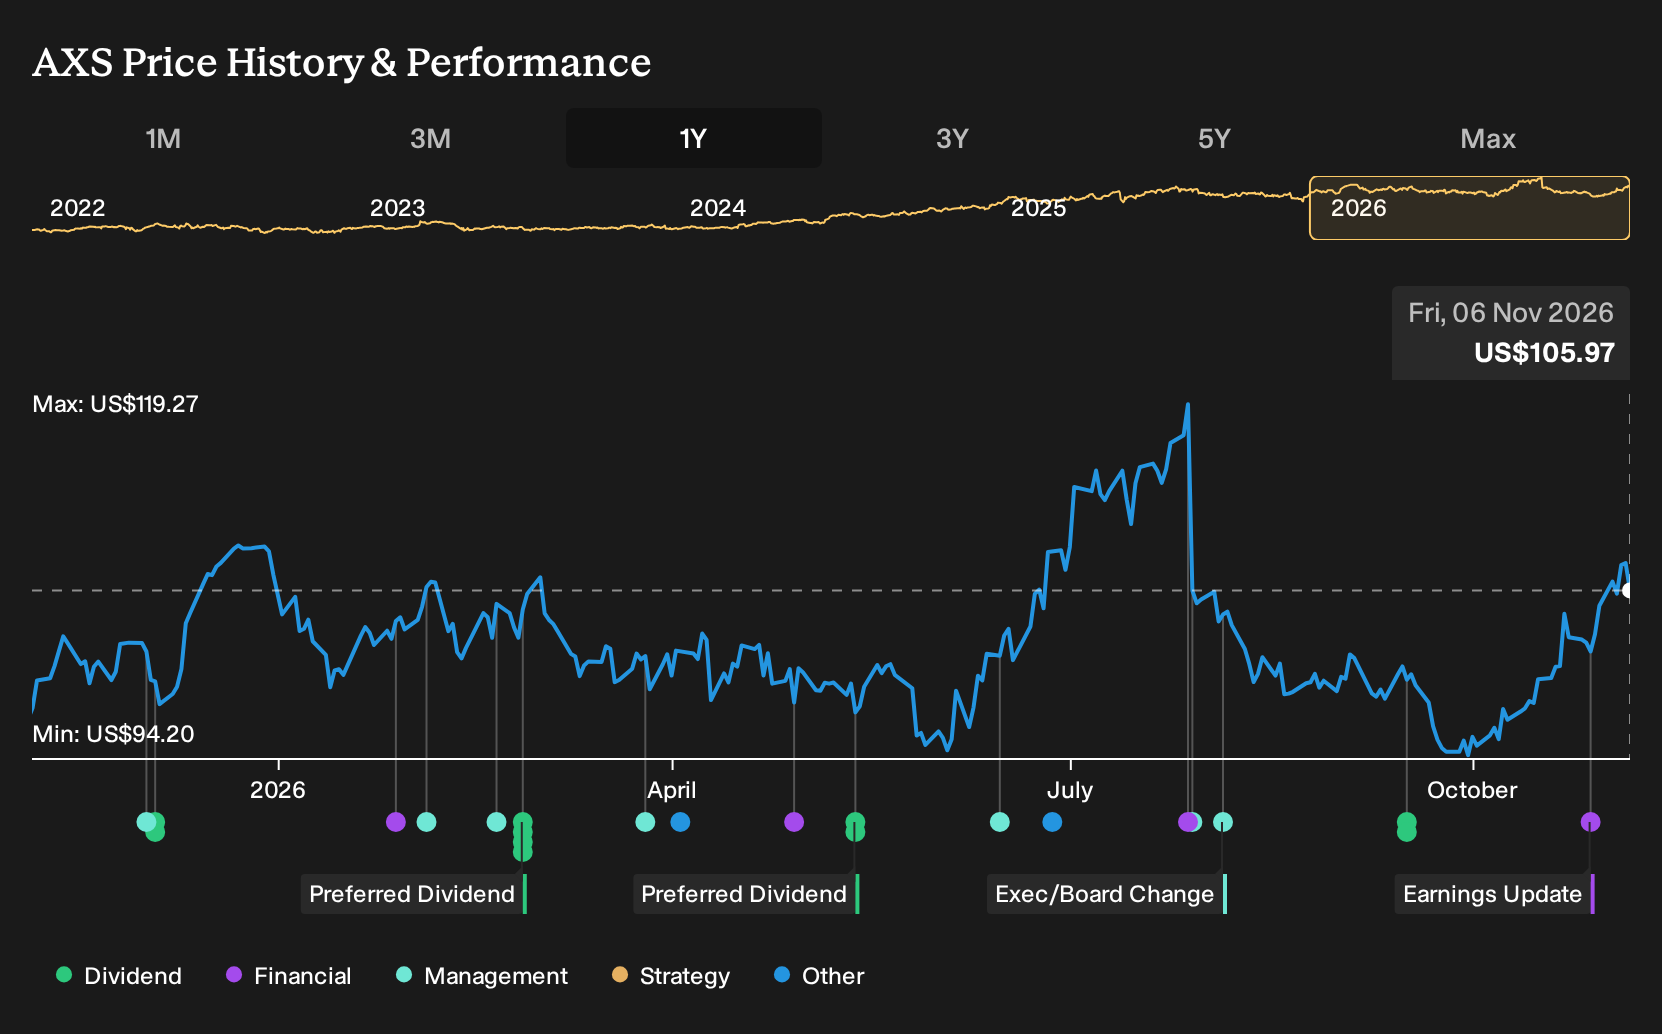
To stay invested in AXIS Capital Holdings, you need to be comfortable with a story that leans on specialty insurance growth, tighter underwriting and fee income from capital light structures. The latest quarter showed higher revenue but lower quarterly net income and earnings per share, which keeps near term profitability in focus rather than changing the long term thesis.
The key near term swing factor is how underwriting margins hold up as pricing pressure and loss trends evolve, especially after management reset loss ratio expectations earlier in 2026. The biggest risk is that competitive pressure in property and cyber lines, together with reduced reinsurance exposure, keeps squeezing profitability more than current results already suggest.
The fresh information that matters most here is the third quarter 2026 earnings detail. AXIS Capital Holdings reported quarterly revenue of US$1,789.93 million and net income of US$209.08 million, with earnings per share from continuing operations lower than the same period in 2025, while nine month net income and per share earnings were slightly higher year on year.
That pattern puts execution under the microscope. Investors are likely to focus on whether management can protect combined ratios while continuing to rotate into shorter tail specialty business, build fee based revenue from AXIS Capacity Solutions and similar structures, and keep expenses contained through technology and the How We Work program as the underwriting cycle softens.
AXIS Capital Holdings' current narrative points to revenue of US$7.4b and earnings of US$1.0b by 2029, based on analyst forecasts that assume 2.2% yearly revenue growth and an earnings increase of about US$18.7m from US$981.3m today.
Uncover how AXIS Capital Holdings' fair value indicates a 12% potential upside to its current price that could narrow quickly if AXIS Capital Holdings continues to execute effectively.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide band, from about US$119 to more than US$304 per AXIS Capital Holdings share. This shows how far apart retail views can be. Put that next to earnings that recently missed expectations and a completed buyback, and you get real tension between execution risk and potential re rating.
Explore another AXIS Capital Holdings fair value estimate, including one that suggests it could be worth just $118.82.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AXIS Capital Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AXIS Capital Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AXIS Capital Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond AXIS Capital Holdings?
If AXIS Capital Holdings is already on your radar, it can help to broaden your watchlist with other companies that have clear balance sheets, income profiles or return potential. The Simply Wall St Screener can surface ideas that match different risk and reward preferences, so you can build a line up that fits your own approach rather than relying on a single stock.
- For investors who want stability first, filter for companies with robust financial footing using a list of solid balance sheet and fundamentals (25 results) that highlights businesses with strong fundamentals and lower balance sheet stress.
- If upside potential is your priority, scan for quality companies that trade below their estimated worth using a curated 38 high quality undervalued stocks to spot candidates for further research.
- Those hunting for resilience with fewer red flags can focus on a 31 resilient stocks with low risk scores that screens for stocks with more measured risk scores and steadier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com