


EN
Does Growth Drug Sales Change The Bull Case For Bristol Myers Squibb Stock?
- Bristol-Myers Squibb reported third quarter 2026 revenue of US$13,069 million and net income of US$2,162 million, with diluted EPS from continuing operations of US$1.05.
- The latest results show the growth portfolio generating meaningful revenue that helps counter pressure from patent expirations on older drugs, which directly affects how resilient Bristol-Myers Squibb’s earnings mix looks to investors.
- We will now see how Bristol-Myers Squibb’s investment narrative is affected by the earnings-driven lift from its newer growth drug portfolio.
Scan how Bristol-Myers Squibb compares with other large-cap healthcare stocks that balance mature franchises and new therapies using our hand-picked 31 resilient stocks with low risk scores.
Bristol-Myers Squibb Investment Narrative Recap
To own Bristol-Myers Squibb, you need to be comfortable with a mature drug portfolio facing patent pressure while newer therapies take on more of the workload. The big belief is that the growth portfolio and pipeline can offset erosion in legacy products like Eliquis over time. The latest quarter, with US$13.1b in revenue and US$2.2b in net income, broadly supports a stable operating base rather than a sharp inflection point.
The key near term swing factor is how quickly newer brands scale relative to any pricing or volume hit on older franchises, and to what extent one off items muddy earnings quality. The main risk is that patent cliffs or safety and regulatory issues slow that handover, especially with some major readouts now timed around 2027. The fresh numbers do not materially change that central tension, but they show the shift in mix is already in motion.
The most relevant data point here is the third quarter 2026 earnings report. Revenue moved from US$12,222 million a year ago to US$13,069 million, while net income was US$2,162 million compared with US$2,201 million. Diluted EPS from continuing operations was US$1.05 versus US$1.08. That mix of slightly higher sales and flat to softer earnings keeps the focus on margins and product mix.
Over the first nine months of 2026, Bristol-Myers Squibb reported US$37.5b in revenue and US$8.2b in net income, with EPS from continuing operations close to US$4 on a basic basis. That sits alongside a growth portfolio that management reports grew revenue 12% in the quarter, helping offset legacy pressure. For you as a shareholder, execution on that newer portfolio and the timing of late stage programs remain central catalysts, while patent cliffs and high debt remain important watchpoints.
Bristol-Myers Squibb's current narrative anchors on analysts expecting revenue of US$39.1b and earnings of US$8.4b by 2029, based on a forecast yearly revenue decline of 7.4% and an earnings decrease of about US$0.9b from US$9.3b today.
Uncover why Bristol-Myers Squibb's fair value indicates a 5% potential upside to its current price, before other investors close that discount.
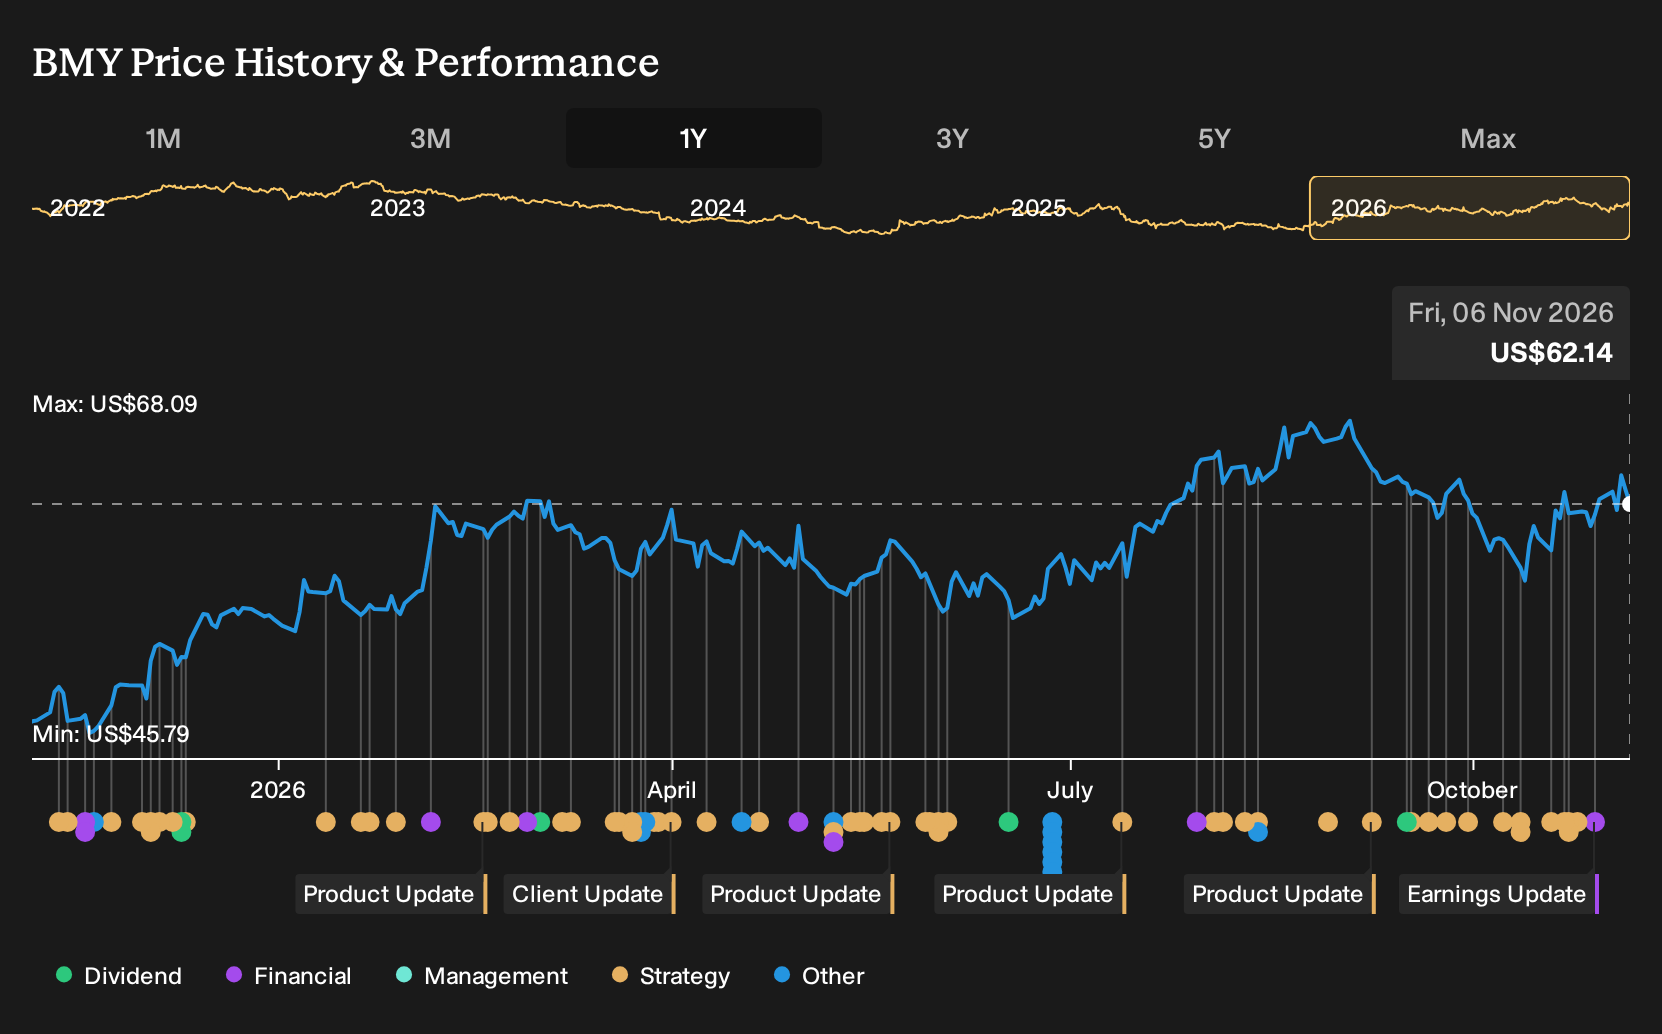
Exploring Other Perspectives
Some bullish analysts focus on Bristol-Myers Squibb’s profit margin potential rather than just patent risk. Before this earnings report, the most optimistic forecasts had revenue reaching about US$42.2b and earnings of US$10.6b by 2029, with margins near 25.2%. You can compare that upbeat view with more cautious estimates and decide which story feels more realistic, keeping in mind that both were set before these latest numbers and may now change.
Explore 3 other Bristol-Myers Squibb fair value estimates, including one that suggests as much as 90% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Bristol-Myers Squibb research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bristol-Myers Squibb. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bristol-Myers Squibb's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bristol-Myers Squibb?
If this Bristol-Myers Squibb update has sharpened your view on healthcare risk and reward, use that same lens to broaden your watchlist. The Simply Wall St Screener can help you quickly spot other companies with balance sheets, income streams, and dividend profiles that better match your own risk tolerance and return goals.
- For income focused investors who want potential yield with an eye on resilience, review a curated set of high payout candidates through 7 dividend fortresses.
- If you prefer quality at what may be a discounted entry price, scan a hand picked pool of fundamental standouts using 38 high quality undervalued stocks.
- For readers who want sturdier financial foundations as a starting point, filter for businesses with stronger debt and liquidity metrics via the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com