


EN
Is Raised 2026 Guidance Altering The Investment Case For Colgate Palmolive (CL)?
- Colgate-Palmolive reported third quarter 2026 sales of US$5,369 million and net income of US$751 million, with basic and diluted earnings per share from continuing operations of US$0.94, and raised full year guidance for 4% to 5% net sales growth and a higher gross profit margin.
- The household products group now expects double digit earnings per share growth in 2026 while still increasing advertising as a share of net sales. This points to a focus on brand investment alongside efficiency gains from pricing, mix and cost programs.
- We will examine how Colgate-Palmolive's raised 2026 sales and margin guidance reshapes the investment narrative around premiumization and efficiency.
Scan beyond Colgate-Palmolive and spot other household and consumer staples stocks showing similar pricing power and earnings momentum with our curated list of 38 high quality undervalued stocks.
Colgate-Palmolive Investment Narrative Recap
To own Colgate-Palmolive, you need to believe that premium oral care, Hill's Pet Nutrition and emerging markets can keep offsetting softer categories and ongoing legal and debt related pressures. The raised outlook for 2026 net sales and gross margin leans on pricing, mix and productivity programs rather than aggressive cost cutting.
The key short term swing factor is whether category softness in U.S. oral care and pet food stabilizes enough for that pricing power to show through cleanly in volumes. The biggest risk remains prolonged weak demand in North America combined with higher legal or brand support costs that could cap the benefit from higher margins.
The most relevant update is Colgate-Palmolive lifting its 2026 guidance to 4% to 5% net sales growth and a higher gross profit margin, while still calling for double digit earnings per share growth. That signals that management is planning for pricing, premiumization and cost programs to feed through more clearly into profitability.
For you as an investor, the question is whether that outlook is realistic given recent nine month results, where sales reached US$16,055 million but net income was slightly lower than a year earlier and margin pressure was visible. If category growth stays muted or legal costs rise, execution on SGPP savings, AI tools and Hill's premium segments becomes critical to keeping that guidance intact.
Colgate-Palmolive's narrative projects US$23.1b revenue and US$3.5b earnings by 2029. This assumes 2.8% yearly revenue growth and an earnings increase of about US$1.4b from US$2.1b today.
Discover how Colgate-Palmolive's fair value indicates a 5% potential upside to its current price that may not last much longer.
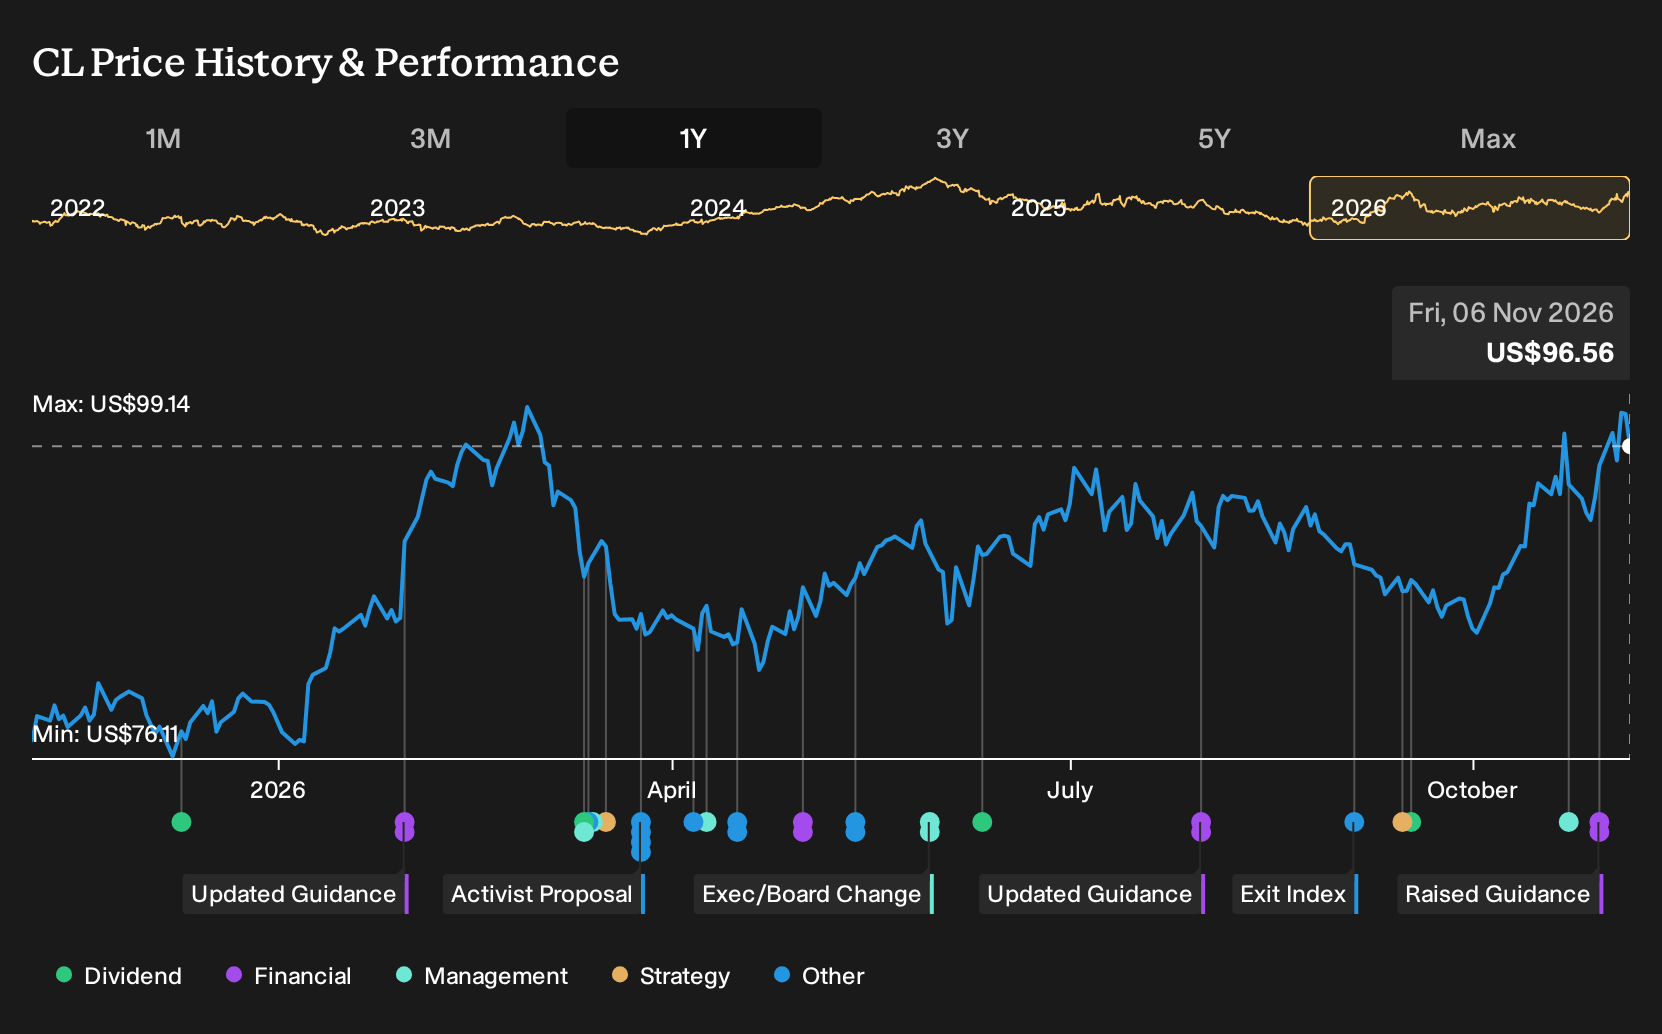
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community span roughly US$86 to US$126 per share, with some retail investors seeing Colgate-Palmolive as sharply discounted and others as richly priced. When you set those gaps against risks such as prolonged category softness and ongoing litigation, you get a wide spectrum of possible outcomes that you should explore directly.
Explore 3 other Colgate-Palmolive fair value estimates, including one that suggests as much as 10% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Colgate-Palmolive research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Colgate-Palmolive. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Colgate-Palmolive's overall financial health at a glance.
Looking for more Colgate-Palmolive style investment ideas?
Once you have formed a view on Colgate-Palmolive, it can help to compare that thesis with other businesses that share some of the same qualities, whether you care more about value, resilience or income potential.
- If you want a wider hunting ground for potential value, take a look at 19 high quality undiscovered gems that may not yet be widely followed but still show strong fundamentals.
- If balance sheet strength is a top priority for you, widen your watchlist with our list of solid balance sheet and fundamentals (25 results) that keep financial risk in check.
- If income is a key part of your plan, scan for stable payers using our 7 dividend fortresses that combine higher yields with thorough fundamental checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com