


EN
Is Stella Jones (TSX:SJ) A Bargain As Earnings And Buybacks Reset The Valuation Debate?
Why Stella-Jones is back on investors’ radar
Stella-Jones (TSX:SJ) just packed earnings, a fresh buyback plan, and a confirmed dividend into one trading day, giving investors new data on both cash generation and capital returns.
Over the past year, Stella-Jones has seen its share price give up ground despite the new buyback and dividend confirmation, with the 1-year total shareholder return declining 20.07% and the year-to-date share price return down 23.52%. However, the 5-year total shareholder return of 67.18% points to a longer-term story that has still rewarded patient holders.
Compare Stella-Jones' latest move on buybacks and dividends with a hand-picked group of sturdier balance sheet players through the list of solid balance sheet and fundamentals (5 results).
Stella-Jones now pairs weaker recent returns with fresh earnings pressure, but also a new buyback and dividend. Does that mix still tilt the risk reward in favour of buyers at today’s price, or not?
Most Popular Narrative: 15% Undervalued
On the most followed narrative, Stella-Jones looks underpriced, with a fair value of CA$77.47 against a last close of CA$65.85. That gap rests on execution in a few key projects rather than a broad rerating of the whole business.
Planned railway tie network optimization with targeted annual cost savings of $10 million to $15 million starting in 2027, combined with expected wood utility pole network efficiencies of $10 million to $12 million, is aimed at lifting net margins and supporting higher adjusted EBITDA once the one time charges roll off.
Expansion of steel transmission structures, with Candiac capacity on track to reach 20,000 tons by Q3 2026 and a 10 year customer contract covering about one third of output, together with the planned 20,000 ton Fayetteville facility, is set to add new revenue streams and support future earnings from grid related projects.
See why 27 investors see Stella-Jones as 15% undervalued.
Result: Fair Value of CA$77.47 (UNDERVALUED)
Still, the recent adjusted EBITDA margin pressure and repeated earnings misses could keep investors cautious if Stella-Jones struggles to deliver on its efficiency plans.
Find out about the key risks to this Stella-Jones narrative.
Another View: Stella-Jones on earnings multiples
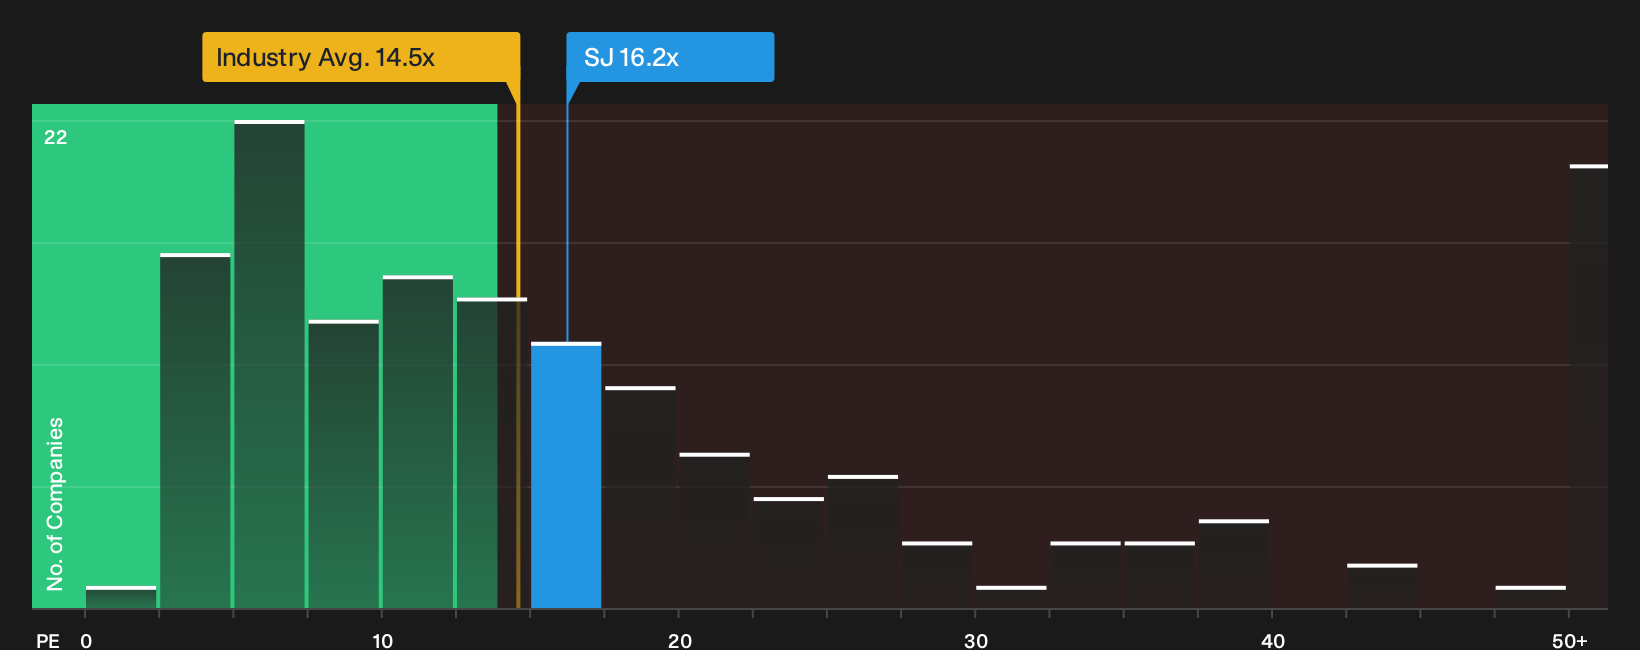
On the flip side of that 15% undervalued fair value, Stella-Jones trades on a P/E of 16.2x. That is richer than both the global forestry industry at 14.5x and its own fair ratio of 15.1x, which points to less room for error if execution wobbles again.
For investors weighing which signal to trust more, it helps to see what the numbers say about this price in a simple valuation breakdown, then decide which story you believe the market could move towards next. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Stella-Jones story so far. If you want to cut through the noise quickly and weigh both sides for yourself, start with the 3 key rewards and 2 important warning signs.
Looking for more Stella-Jones sized investment ideas?
If Stella-Jones has you thinking harder about risk and reward, do not stop here. The next move often comes from an idea you have not checked yet.
- Target resilient income by focusing on payouts you can actually count on through the 3 dividend fortresses.
- Hunt for quality at a marked down price and see which companies our valuation filters highlight in the 7 high quality undervalued stocks.
- Prioritize calmer nights by narrowing in on companies that carry fewer red flags with the 9 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com