


EN
Missed Elevance Health's Rally? What Holders Had To Believe
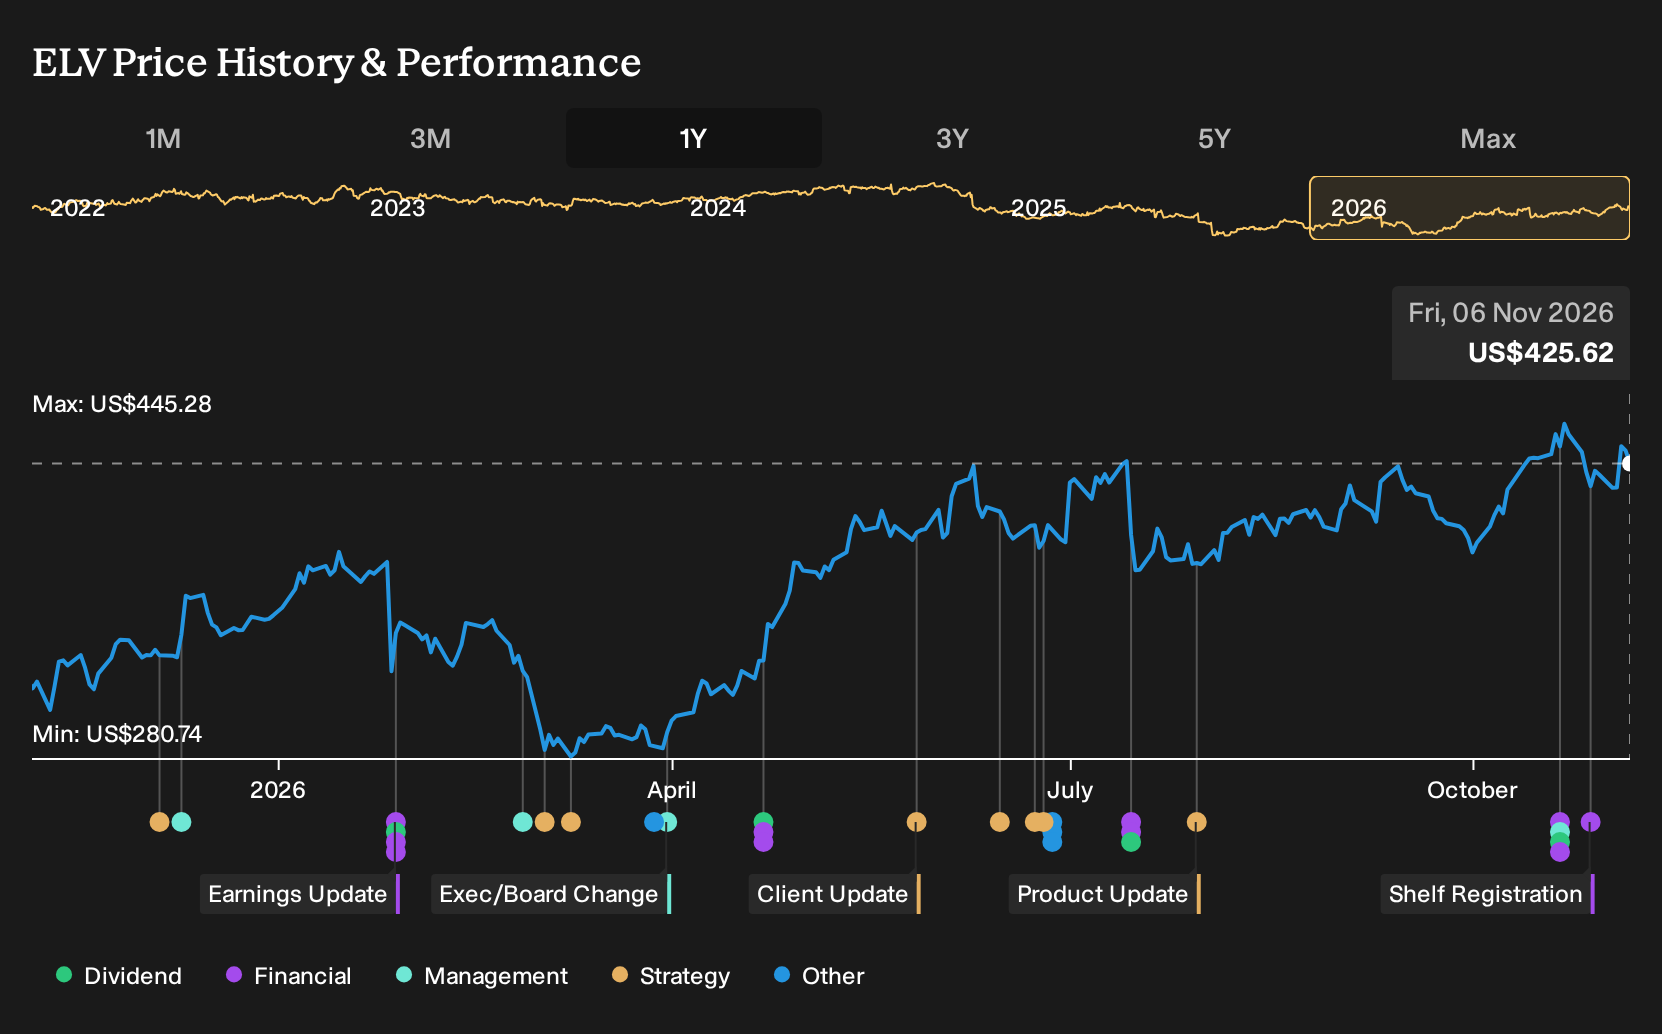
If you only glanced at the headlines about Elevance Health in late 2025, the story looked conflicted. Bulls argued that AI investments and value-based care could lift margins despite ACA and Medicaid pressure, while bears warned that the same government programs might keep squeezing profits. Holding Elevance Health over the past year would have returned 36.6%, including dividends. If you had been weighing those opposing views back then, what in the record really deserved your trust?
This theme extends beyond Elevance Health. See which of 35 healthcare AI stocks may still merit a closer look.
The Two Stories Investors Had To Choose Between On Elevance Health
The shares cost US$314 at the start of the period, and Elevance Health either looked like a margin recovery play or a government plan squeeze waiting to happen.
On the bullish side, one framework put Fair Value at US$370, a rough estimate of what the stock might be worth if its assumptions held. That case leaned on 6.8% annual revenue growth assumptions and profit margins rising toward 3.2% as AI tools and value-based care improved efficiency.
The bearish script set Fair Value at US$297 and focused on compressed profitability. It highlighted the risk that ACA and Medicaid cost trends would keep margins closer to 2.3% and that slow Medicaid rate realignment plus tougher provider tactics could keep earnings more volatile.
What The Results Changed For Elevance Health
Elevance Health reported Q3 2026 revenue of US$51,429 million and net income of US$1,365 million, both higher than a year earlier, and net margin moved from 2.3% to 2.7%. That lent weight to the bullish margin recovery story. Medicaid and ACA pressures still showed up in guidance, so the numbers cut both ways rather than closing the debate.
The key assumption investors were really betting on was margin resilience under government plan stress. For any other insurer with a similar story, track whether net margin and the benefit or medical expense ratio move in the same direction management had set out a year earlier.
What Elevance Health’s Price Now Asks You To Believe
With Elevance Health at US$426, the selected Narrative’s Fair Value sits above the current price and leans on a sharper earnings story tied to Carelon and internal AI platforms.
The Narrative argues today’s price still does not fully credit successful execution of the Medicare Advantage and Medicaid reset alongside sustained Carelon-driven medical cost savings.
"Key Takeaways: Bullish analysts expect Elevance Health to compound earnings power over time as AI-enabled HealthOS, Sydney Health and Carelon platforms compress decision cycles, automate workflows and support lower medical and operating costs across a larger government and Carelon base. The main factor that has to go right is successful execution of the multi-year Medicare Advantage and Medicaid reset, including targeted exits and benefit design changes."
The price and this Narrative do not agree. → Uncover what this Narrative says Elevance Health is actually worth
Looking Beyond Elevance Health
Following Elevance Health puts you in the thick of healthcare complexity. Government programs, medical trends and AI investments intersect there each quarter.
Step sideways and you see another insurer facing similar pressures. It is leaning on technology, automation and value-based models to manage medical costs.
This business is applying AI to claims work, call centers and clinical paperwork. The aim is simpler workflows that support more predictable earnings from complex members.
Its care arm is testing services that shorten hospital stays and expand home visits. If those efforts scale, cost and coverage tradeoffs could shift meaningfully.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 22% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com