


EN
Ashmore Group And 2 Other British Penny Stocks To Watch
China’s wholesale inflation has picked up again, with producer prices rising at the fastest pace since June 2022. That matters for you because shifts in Chinese factory costs often ripple into UK supply chains and investor sentiment. When markets start reassessing risk, smaller British companies with healthier finances can look more appealing. This article highlights three low priced UK stocks screened for stronger balance sheets and more disciplined cash habits.
The three stocks highlighted here offer a compelling starting point if you want exposure to lower risk early-stage businesses that still focus on financial strength. However, if you want the strongest names, these 17 elite penny stocks are the top of the list.
Ashmore Group (LSE:ASHM)
Overview: Ashmore Group is a London based asset manager that runs emerging markets equity, bond and alternatives funds for institutional and retail clients.
Operations: The business generates £139.3 million from investment management services, with revenue mainly sourced from the UK and Ireland at £88.4 million.
Market Cap: £1.34 billion
Ashmore Group plugs directly into the Financially Fit Penny Stocks theme by giving you exposure to smaller emerging markets through professionally run funds, while still operating as an established London manager with a focus on financial discipline.
"The renewed net inflow phase into emerging markets, with Ashmore Group reporting FY26 net inflows of $2.7b alongside rising subscriptions and lower redemptions, creates scope for a longer period of higher fee earning AuM than consensus typically models."
What really matters now is how one quiet shift in its profit mix filters through to future fee margins and cash generation.
That shift in profit mix is exactly what the full narrative for Ashmore Group unpacks, including how fee margins and cash generation could decouple from headline AuM trends.

Applied Nutrition (LSE:APN)
Overview: Applied Nutrition is a Liverpool based sports nutrition specialist selling proteins, performance supplements and wellness products to fitness focused consumers worldwide.
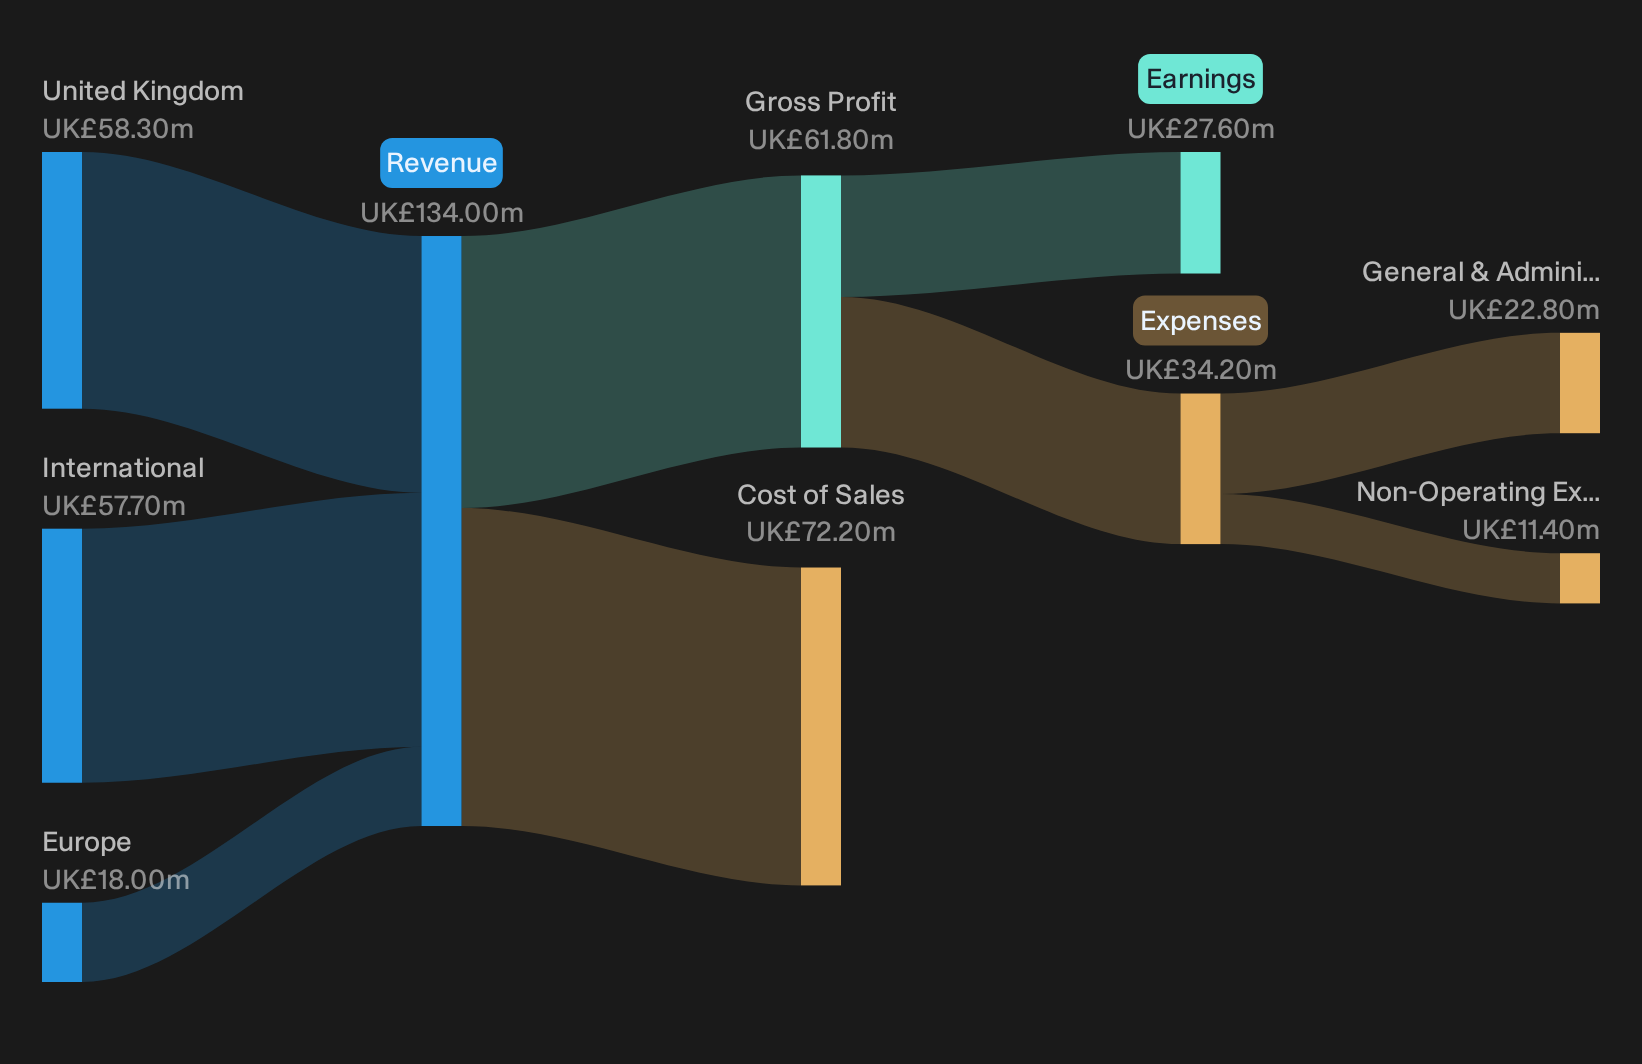
Operations: Applied Nutrition generates £134 million from manufacturing and selling sports nutrition products, with roughly equal revenue from the UK and overseas markets.
Market Cap: £754 million
Applied Nutrition plugs directly into the Financially Fit Penny Stocks idea because its sports nutrition range is the main engine behind a financially focused growth story, where a younger listed business is trying to scale while keeping funding and cash generation on a tighter leash than many early stage peers.
"High reported free cash flow conversion of 72% in FY25, combined with an adjusted EBITDA margin of 29% and a net cash position, provides Applied Nutrition with room to pursue bolt-on capacity or capability investments that could add incremental revenue without materially increasing financial risk."
What happens if that extra production and distribution capacity fills more slowly than planned could decide how resilient those margins really look.
That margin test is exactly where the full narrative for Applied Nutrition traces whether Applied Nutrition is quietly building an accelerating cash engine, or just masking pressure with early momentum.
Currys (LSE:CURY)
Overview: Currys is an omnichannel retailer selling affordable and higher end consumer electronics, mobile devices and related services across the UK and Nordics.
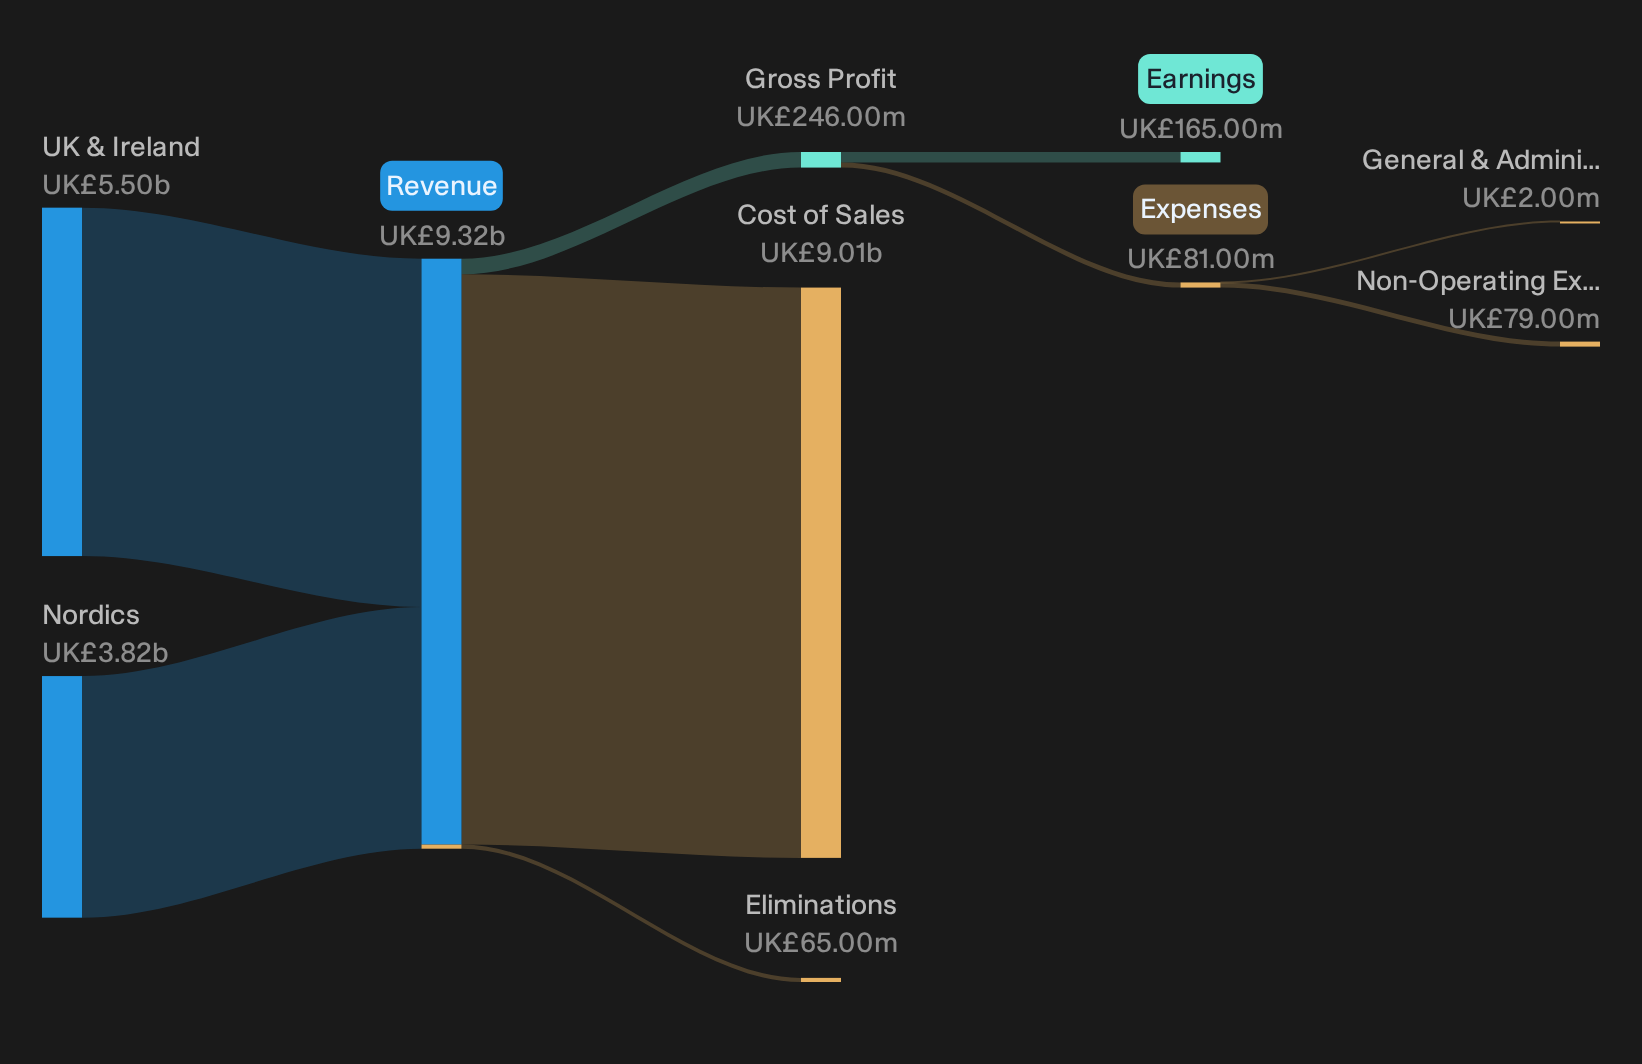
Operations: Currys generates £5.5b from the UK and Ireland and £3.8b from the Nordics, with the rest offset by eliminations.
Market Cap: £1.47b
Currys fits the Financially Fit Penny Stocks theme because its lower priced gadgets and bundle offers give cost conscious buyers a way into everyday tech, while the wider retail and services platform is built around keeping the balance sheet and cash generation in reasonable shape.
"Expansion of higher margin recurring services such as credit, installations, connectivity and repair, which now account for over 30% of UK revenue and have been growing faster than product sales, can affect Currys group revenue quality and EBIT margins as more customers shift into these offers."
What investors really need to watch is how one quiet shift in customer behaviour shapes the gap between headline sales and long term profitability.
If you want to see how that shift in customer behaviour could reshape Currys profit mix, the full narrative for Currys maps where recurring services might be quietly accelerating value.
Curious About What You Might Be Missing?
Fresh ideas move first. By the time momentum is obvious, early entries are often gone and spreads are wider. Scan these curated shortlists before the crowd and act now.
- Spot early movers with steady finances by running the 5 high quality undiscovered gems while information is still under the radar for now and conviction can build ahead of wider attention.
- Track cash rich compounders built for stress with the list of solid balance sheet and fundamentals (9 results) and avoid getting caught chasing fragile rallies once markets turn cautious.
- Ride structural themes instead of short term noise by filtering through the 4 resilient stocks with low risk scores before momentum sends quality assets out of your preferred range.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com