


EN
FirstSun Capital Bancorp (FSUN) Could Be 52% Below Fair Value On Stronger Q3 Results
FirstSun Capital Bancorp (FSUN) just delivered third quarter 2026 results that combined higher net interest income with stable earnings per share, completed a US$49.7 million buyback, and reported lower net charge offs.
Recent trading has been more muted. The share price is up 2.9% year to date, and the current 1-year total shareholder return of 19.1% sits well ahead of the short-term moves, hinting that buyers have been rewarding FirstSun Capital Bancorp for earlier progress rather than this week’s dip.
Capture how FirstSun Capital Bancorp’s latest quarter fits into the broader bank trade by scanning a curated set of list of solid balance sheet and fundamentals (25 results) for comparison.After a 1 year total return of 19.1% and a completed US$49.7 million buyback, the choice is straightforward but not necessarily easy: maintain exposure to FirstSun Capital Bancorp now, or wait for a potentially lower entry point.
Price-to-Earnings of 30.3x: Is it justified?
Valuation on FirstSun Capital Bancorp is not cheap on headline numbers. With the shares at $38.91 and a P/E of 30.3x, the market is assigning a much richer tag than the typical US bank or its closest peers.
The P/E ratio compares what investors pay today for each dollar of earnings. For a lender like FirstSun Capital Bancorp, that usually reflects expectations about future profitability, credit quality, and balance sheet strength rather than just the last twelve months of profit.
Here the gap is wide. FSUN trades on 30.3x earnings, while the broader US Banks industry sits at 11.3x and the peer group average is 12.7x. Even against an estimated fair P/E of 23.2x, the current multiple looks stretched and implies the market is already pricing in a much stronger earnings profile than the fair ratio suggests.
Explore the SWS fair ratio for FirstSun Capital Bancorp.
Result: Price-to-Earnings of 30.3x (OVERVALUED)
Still, the rich 30.3x P/E leaves little room for disappointment if earnings momentum cools or credit quality at FirstSun Capital Bancorp weakens from current levels.
Find out about the key risks to this FirstSun Capital Bancorp narrative.
Another View: What the SWS DCF Model Says
The P/E points to an expensive FirstSun Capital Bancorp, yet the SWS DCF model tells a different story. With the shares at $38.91 and an estimated future cash flow value of $59.14, the stock screens as undervalued. Which signal do you trust more when money is on the line?
Look into how the SWS DCF model arrives at its fair value.
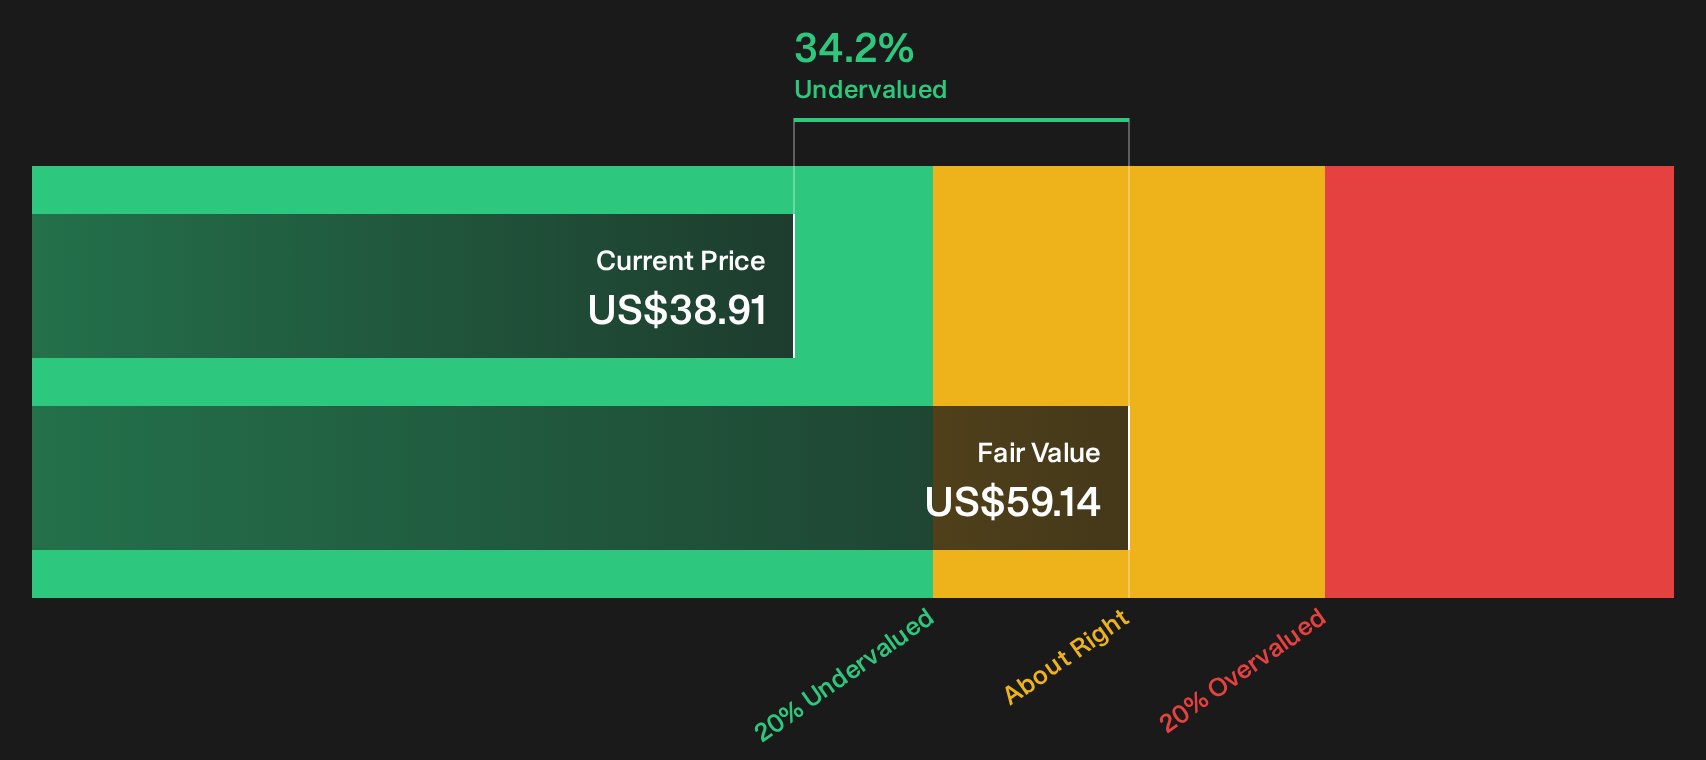
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out FirstSun Capital Bancorp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 38 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of mixed signals surround FirstSun Capital Bancorp right now, which is exactly why your own judgment matters. Act while the data is fresh and weigh both sides by reviewing the 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond FirstSun Capital Bancorp?
If FirstSun Capital Bancorp has your attention, do not stop here. The next winner in your portfolio might sit just a few clicks away.
- Scan for quality at a discount by reviewing the 38 high quality undervalued stocks, which combine solid fundamentals with prices the market has not fully recognised yet.
- Strengthen your income stream by focusing on the 7 dividend fortresses, which aim to pair higher yields with resilient business models.
- Protect your downside first and let upside take care of itself by filtering through the 31 resilient stocks with low risk scores, tailored for steadier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com