


EN
Bio Rad Laboratories (BIO) Could Be 14% Overvalued After Elliott Interest And Earnings
Bio-Rad Laboratories (BIO) moved into focus after fresh third quarter earnings showed sales of US$656.4 million and net income of US$458.6 million, alongside a US$49.8 million impairment on purchased intangibles.
The latest third quarter result and fresh attention from activist Elliott Investment Management arrive after a strong run in the Bio-Rad Laboratories share price, with a 1-day share price return of 3.41% and a year-to-date share price return of 24.99% at US$381.57.
Scan how other lab tools and diagnostics players with strong balance sheets compare by checking the hand-picked list of solid balance sheet and fundamentals (25 results) alongside Bio-Rad Laboratories.
Bio-Rad Laboratories now trades above the average analyst target and at a premium to some intrinsic value estimates, even after the latest jump in the share price. Is investor caution lagging reality, or is it still anchoring it?
Most Popular Narrative: 14% Overvalued
Against the latest close at $381.57, the most followed narrative pegs Bio-Rad Laboratories' fair value at $335, which implies investors are already paying up for execution on margins and ddPCR driven growth.
The multi year restructuring program announced in 2026, which targets US$30 to 35 million of net annual cost savings by 2028 and has already supported an improvement in non GAAP operating margin to 12.8%, may be encouraging investors to price in a faster move toward mid teens or higher operating margins than the current trajectory supports, inflating expectations for future earnings.
See why 7 investors see Bio-Rad Laboratories as 14% overvalued.
Result: Fair Value of $335 (OVERVALUED)
Still, if ddPCR momentum holds up and recent margin gains from Bio-Rad Laboratories’ restructuring persist, the current overvaluation narrative may be too conservative.
Find out about the key risks to this Bio-Rad Laboratories narrative.
Another View: What Multiples Say About Bio-Rad Laboratories
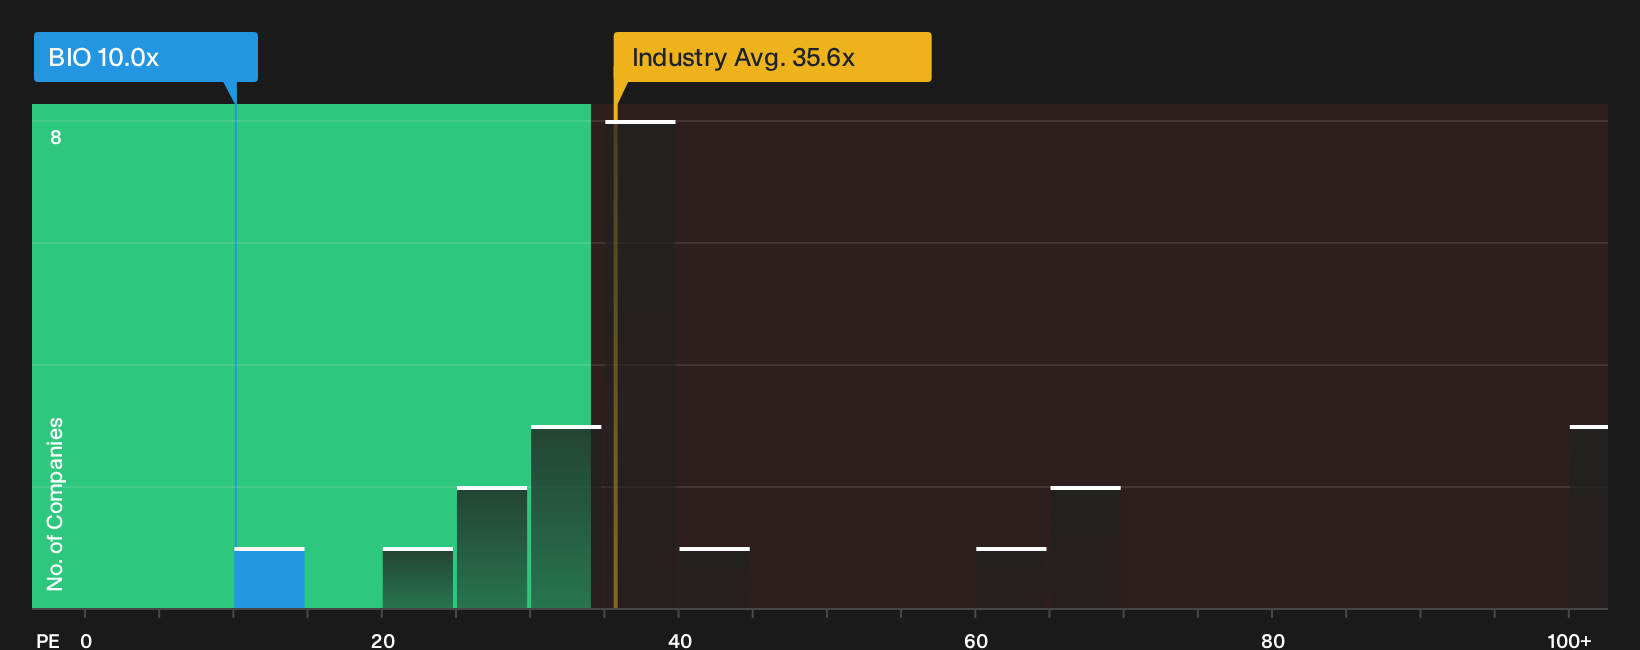
On simple P/E math, Bio-Rad Laboratories looks quite different from the overvaluation story. The stock trades at 10x earnings compared with roughly 40x for peers and 35.6x for the wider Life Sciences group, while the fair ratio sits close by at 10.3x.
That gap suggests investors are paying a steep premium versus analysts' fair value in dollar terms, yet only a modest premium versus the 10.3x fair ratio that the market could gravitate toward. This keeps the real question alive for you: is the risk in the growth story or in the multiple moving closer to peers?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Bio-Rad Laboratories so far. If you want your view grounded in more than headlines, compare the 3 key rewards and 2 important warning signs with your own expectations.
Looking for more investment ideas beyond Bio-Rad Laboratories?
If you want to sharpen your watchlist and not just react to the next Bio-Rad Laboratories headline, start hunting for fresh opportunities that actually fit your criteria.
- Target potential mispricings by scanning a focused set of quality opportunities through the 38 high quality undervalued stocks that may not yet be fully appreciated by the market.
- Prioritize resilience by reviewing the 31 resilient stocks with low risk scores so your next idea lines up with balance sheet strength and lower overall risk scores.
- Get ahead of the herd by searching the 19 high quality undiscovered gems and find companies with solid fundamentals before they are widely on investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com