


EN
Did CFO Change Just Shift PNC Financial Services Group's (PNC) Investment Narrative?
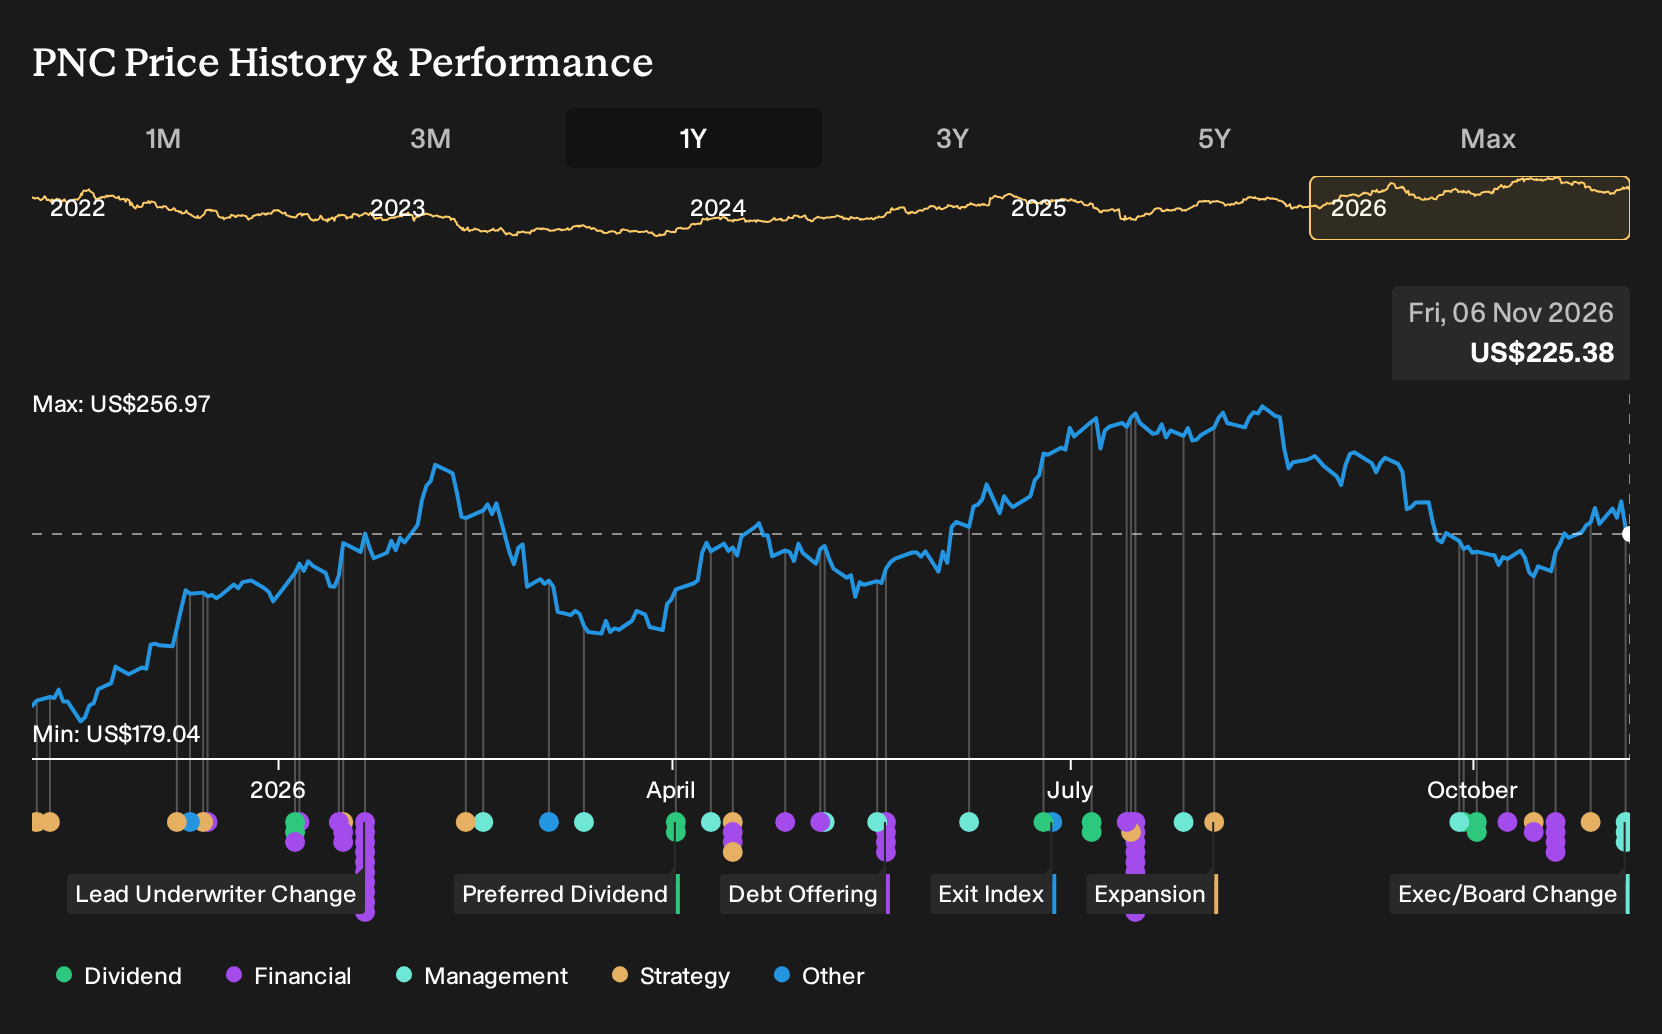
- PNC Financial Services Group has reshaped its senior leadership, with Alexander E. C. Overstrom set to assume the Chief Financial Officer role on March 1, 2027, and long serving CFO Robert Q. Reilly moving to Executive Vice Chairman, while the bank also rolls out PNC Payroll by ADP within its digital platform for small businesses.
- The combination of a new finance chief with deep retail and digital banking experience and an embedded ADP payroll offering indicates PNC Financial Services Group is tying executive responsibilities and product development more tightly to technology, small business services and integrated cash management.
- We will now look at how PNC Financial Services Group's investment narrative could be influenced by Overstrom's CFO transition and ADP partnership.
Compare PNC Financial Services Group's tech focused banking push with a curated set of peers by scanning 53 AI infrastructure stocks, building the rails for AI driven financial services and real time payments.
PNC Financial Services Group Investment Narrative Recap
To own PNC Financial Services Group, you need to be comfortable with a bank that leans heavily on technology spend, fee based businesses and a national branch buildout to support earnings over time. The near term story still hinges on whether that AI and automation program actually feeds through to the roughly 40 points of operating leverage management is targeting.
The biggest near term swing factor remains client activity in fee lines like capital markets, card and cash management. A pullback there or pressure on credit quality could matter more to results than this executive reshuffle. On that basis, the CFO transition and new title for Robert Reilly look more like governance housekeeping than an immediate catalyst.
Among the current announcements, PNC Payroll by ADP links most directly to the investment story. It plugs ADP’s AI enabled payroll, HR, insurance and retirement tools into PNC’s existing digital platform so small businesses can handle cash flow, payments, payroll and compliance in a single workflow. That sits squarely inside PNC’s push to grow fee income and deepen commercial relationships.
Execution risk is real. PNC needs small businesses to actually adopt this embedded service at scale for it to meaningfully support noninterest revenue and justify the heavy tech budget. Integration quality, uptime and customer support from both PNC and ADP will shape whether this becomes a visible earnings contributor or just another tool in the portal.
PNC Financial Services Group Analyst Setup: What The Numbers Assume
PNC Financial Services Group's narrative projects US$29.2b revenue and US$8.8b earnings by 2029. That path assumes 5.4% yearly revenue growth and an earnings increase of about US$1.3b from US$7.5b today.
Uncover why PNC Financial Services Group's fair value indicates a 17% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$264 to US$392 a share, which already shows how far opinions on PNC Financial Services Group can stretch. When you also consider the pending CFO change and the ADP partnership, alongside heavy tech investment, there is plenty of room for different interpretations of future execution. Use that spread as a prompt to test several contrasting viewpoints before deciding how this story fits your own expectations.
Explore another PNC Financial Services Group fair value estimate, including one that suggests it could be worth just $263.71.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your PNC Financial Services Group research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for PNC Financial Services Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PNC Financial Services Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond PNC Financial Services Group?
If PNC Financial Services Group is only one part of your watchlist, it can help to scan a wider field of opportunities that fit different risk and income profiles.
- Target steadier balance sheets and financial resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that meet strict fundamentals criteria.
- If capital preservation matters most, filter for companies with historically lower risk profiles through a focused 31 resilient stocks with low risk scores tailored to more cautious investors.
- For those willing to do deeper homework in search of underfollowed prospects, cast a wider net across a curated 19 high quality undiscovered gems with strong underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com