


EN
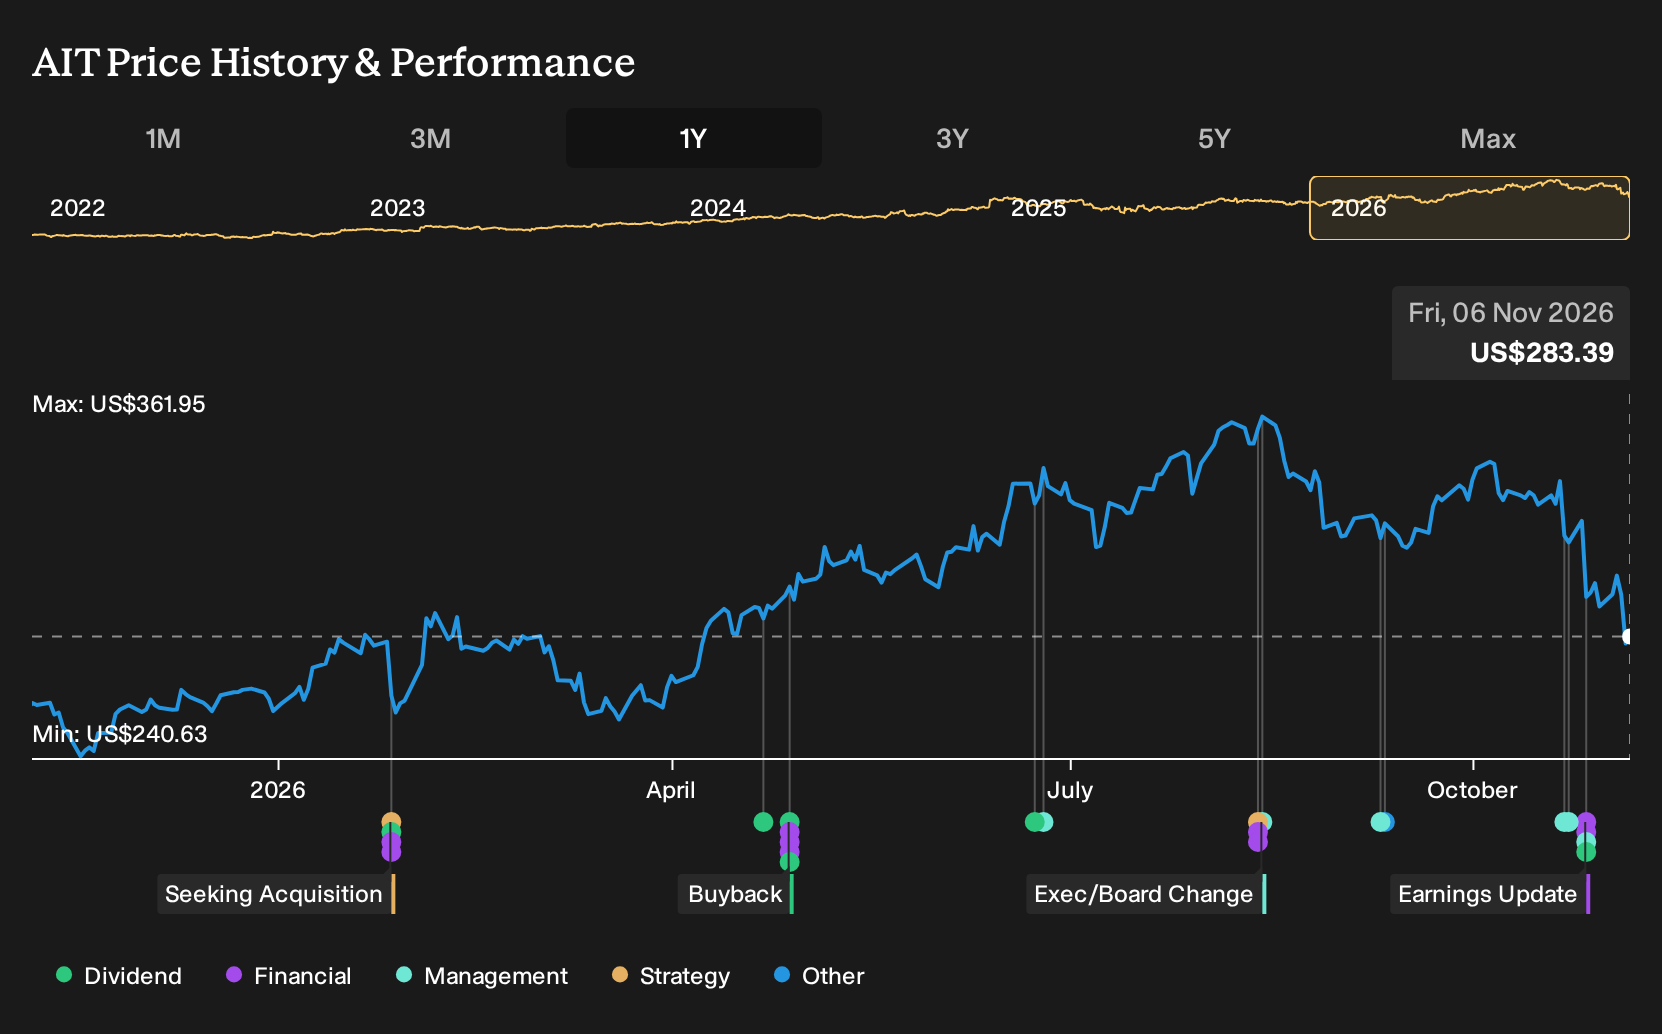
How Raised Earnings Guidance At Applied Industrial Technologies (AIT) Has Changed Its Investment Story
- Applied Industrial Technologies reported first quarter basic EPS from continuing operations of US$3.01 and diluted EPS of US$2.97, and the board declared a US$0.51 quarterly dividend per share payable on November 30, 2026 to holders of record on November 13.
- The board change, with long serving director Joe A. Raver becoming independent chairman as EPS guidance for fiscal 2027 is raised, highlights the alignment between governance and financial outlook at Applied Industrial Technologies.
- Investors can now assess how Applied Industrial Technologies' higher full year EPS guidance may influence perceptions of its longer term narrative.
Scan how Applied Industrial Technologies fits into your portfolio thesis by comparing its latest earnings, dividend profile, and governance shift with a curated set of list of solid balance sheet and fundamentals (25 results)
Applied Industrial Technologies Investment Narrative Recap
To own Applied Industrial Technologies, you need to be comfortable with a story built on steady demand for industrial motion, fluid power, and automation projects, plus disciplined capital deployment into Engineered Solutions. The raised EPS guidance points to management’s confidence in execution, but the near term swing factor still looks like order trends across cyclical end markets, where visibility remains limited.
The main risk remains that softness in machinery, metals, utilities, energy, aggregates, and chemicals lingers longer than expected, which could keep FY27 sales growth in the lower part of the 4% to 6.5% range and pressure EBITDA margins. Higher LIFO expense and acquisition integration missteps would add further strain.
The most directly relevant update is the higher fiscal 2027 EPS guidance to US$11.70 to US$12.20, which management attributes to a slightly lower diluted share count after first quarter repurchases. For you, the operational question is whether earnings quality keeps pace with per share math as Applied Industrial Technologies leans on buybacks alongside organic drivers.
This guidance still assumes sales rising 4% to 6.5%. As a result, the key near term catalyst is execution in automation and Engineered Solutions, where backlogs and project mix influence both growth and margins. If demand in higher value verticals like semiconductors and data centers holds up while LIFO and integration risks stay manageable, that supports the current narrative that the business can compound earnings steadily.
Applied Industrial Technologies' current analyst narrative points to revenues of US$5.8b and earnings of US$511.0m by 2029, based on assumed annual revenue growth of 5.2% and an earnings increase of about US$96.5m from US$414.5m today.
Uncover why Applied Industrial Technologies' fair value indicates a 34% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$300 to US$380 per share, which already shows how sharply views on Applied Industrial Technologies can split. Layer on raised EPS guidance, board turnover, and a reaffirmed dividend, and you get a mix of confidence and execution risk that invites you to weigh several competing viewpoints.
Explore another Applied Industrial Technologies fair value estimate, including one that suggests as much as 34% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Applied Industrial Technologies research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Applied Industrial Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Applied Industrial Technologies' overall financial health at a glance.
Looking for more investment ideas beyond Applied Industrial Technologies?
Once you have a view on Applied Industrial Technologies, it can help to set it alongside a wider watchlist assembled with the Simply Wall St Screener. That way you can compare quality, income potential, and risk across several options rather than anchoring on a single stock.
- If capital preservation is near the top of your list, scan a curated set of companies considered more resilient with 31 resilient stocks with low risk scores.
- For investors who care most about balance sheet strength and fundamentals, compare Applied Industrial Technologies with a list of solid balance sheet and fundamentals (25 results) as a useful cross-check.
- If you want to widen the search to underfollowed opportunities, expand your hunting ground with a collection of 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com