


EN
Should Record Concert Attendance Require Action From Live Nation Stock Investors?
- Live Nation Entertainment reported third quarter 2026 sales of US$10.1b and net income of US$447.8 million, alongside record attendance of more than 60 million fans and higher operating income across all divisions.
- The business raised its full year outlook for Ticketmaster and flagged double digit adjusted operating income growth in Concerts, with international venues and stadium tours supplying a large share of the incremental fan traffic.
- We will now look at how Live Nation Entertainment’s investment narrative could shift as record global concert attendance reshapes its growth mix.
Scan Live Nation Entertainment’s surge in global fan demand and then line it up against other event driven opportunities using our curated list of 19 high quality undiscovered gems for your next deep research session.
Live Nation Entertainment Investment Narrative Recap
To own Live Nation Entertainment, you need to believe the appetite for live events stays strong enough to support its venue buildout, Ticketmaster investments and sponsorship engine. The Q3 2026 update, with US$10.1b in sales and record attendance, reinforces that demand picture in the near term. The key short term catalyst remains efficient ramp up of new international venues and stadium tours, while the biggest swing risk is still regulatory and antitrust pressure on Ticketmaster economics.
Recent results also underline that earnings can move around. Nine month net income of US$353.2 million compares with US$698.1 million a year earlier, so higher fan counts are not automatically translating into higher profits yet. Pre opening venue costs and any future legal remedies could keep margins under pressure if not managed carefully.
The most relevant data point for this story is Q3 2026 attendance of more than 60 million fans, nearly 20% higher than the prior year period, driven by stadium shows and international markets. For an investor, that volume matters because it is the raw material for Ticketmaster fees, sponsorship deals and on site spending across Live Nation Entertainment venues.
Management also raised the full year outlook for Ticketmaster adjusted operating income to high single digit growth and flagged double digit adjusted operating income growth in Concerts. Those signals tie directly into the main catalysts investors already watch. These include international expansion and Venue Nation capacity additions. Regulatory outcomes around Ticketmaster remain the key external risk to how much of that fan activity flows through to future profitability.
What The Analyst Framework Implies For Live Nation Entertainment
Sell side forecasts around Live Nation Entertainment attempt to translate the current surge in fan volumes into a longer run financial arc. Analysts in the consensus set assume revenue can compound at 9.4% a year for the next three years, with profit margins moving from a 1.0% loss today to a 2.9% profit level over the same horizon. The model in focus points to earnings of US$996.6 million by 2029, based on revenue of US$34.4b, which would sit inside a wide range of earnings views that runs from US$792.0 million to US$1.7b. That variety of opinions gives you a sense of how much uncertainty still surrounds the eventual payoff from the current venue and technology spending cycle.
Live Nation Entertainment's narrative projects US$34.4b revenue and US$996.6 million earnings by 2029. This rests on 9.4% yearly revenue growth and an earnings increase of about US$1.25b from a loss of US$258.0 million today.
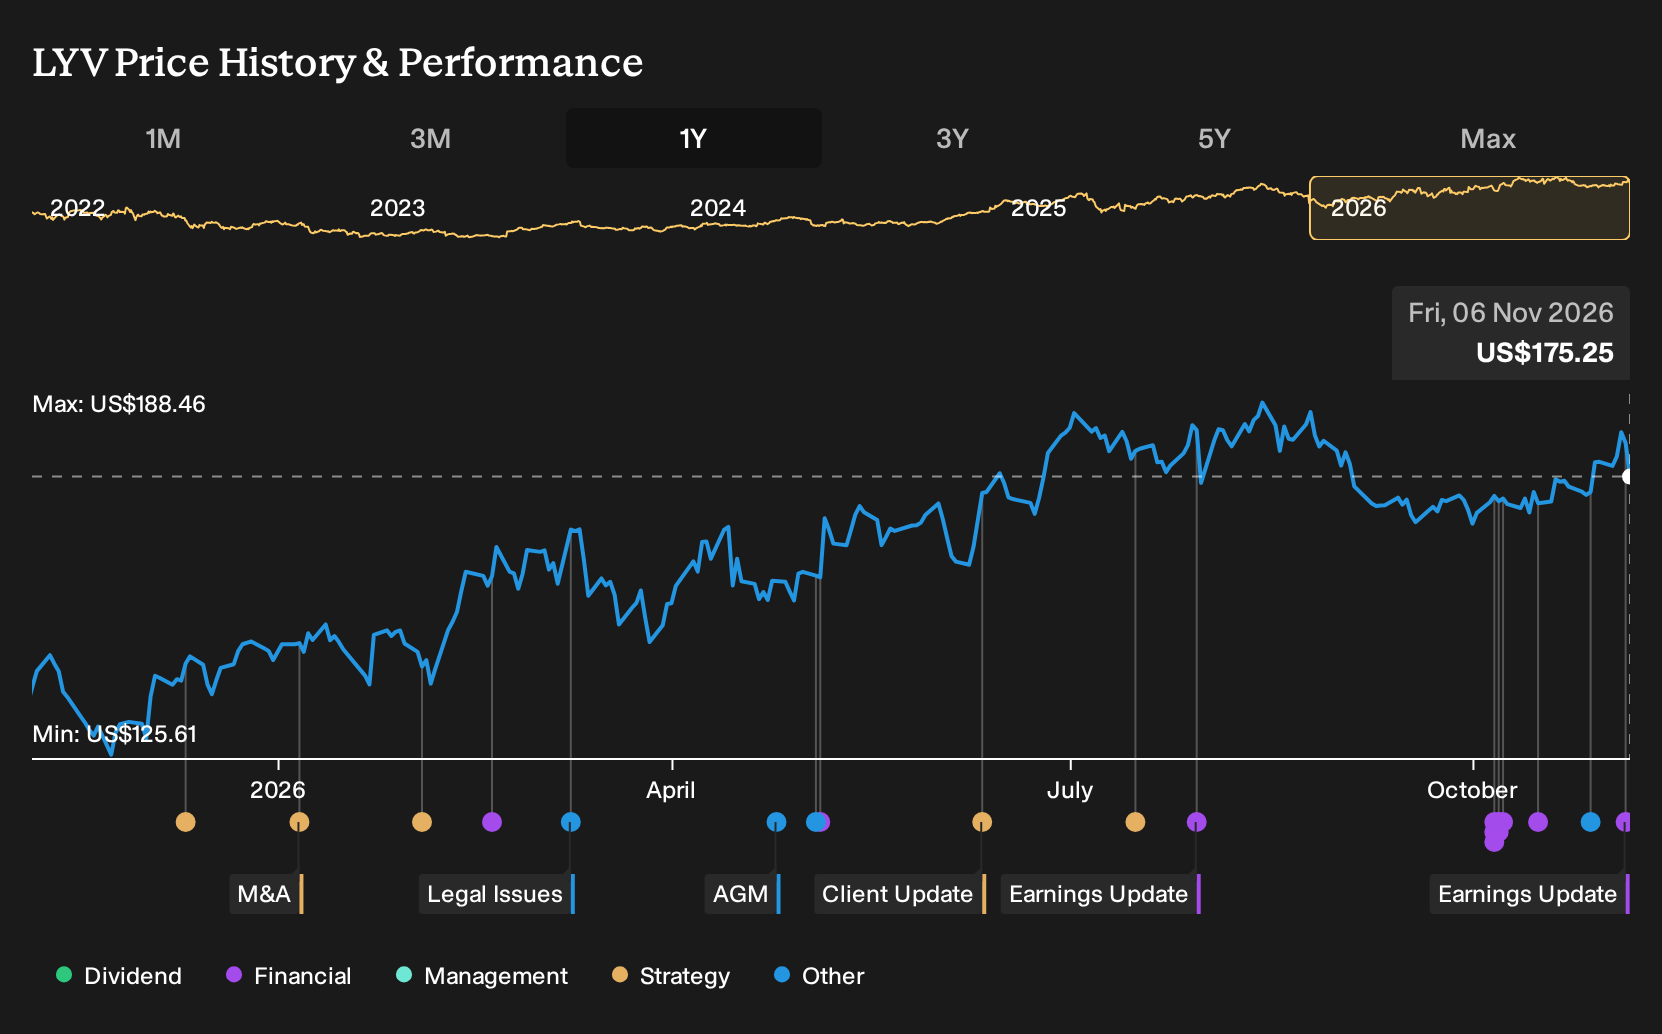
To get from these income forecasts to a price target, the same analyst framework applies a P/E of 63.0x to those 2029 earnings. This is higher than the current reported 21.3x P/E for the broader US Entertainment industry. At the time of the report, that set of inputs lined up against a consensus target price of US$201.96 per share compared with a spot price of US$167.12. Even with that upside gap baked into the models, the forecasting work still depends heavily on the idea that higher margin ticketing and sponsorship flows eventually catch up with, and make better use of, the record fan counts the business is seeing today.
The same worksheets also factor in modest dilution, with the share count expected to increase by about 0.32% annually over the next three years. That pace limits the drag on per share earnings growth if operating performance tracks the revenue and profit margin assumptions. For you as an investor, it means most of the heavy lifting in these Live Nation Entertainment scenarios still comes from how efficiently Ticketmaster fees, sponsorship contracts and new venues convert future fan demand into earnings per share rather than from financial engineering or aggressive buybacks.
Uncover why Live Nation Entertainment's fair value indicates a 15% potential upside to its current price that could narrow quickly as more investors focus on the Q3 story.
Exploring Other Perspectives
The Simply Wall St Community adds two retail fair value views for Live Nation Entertainment, clustered between about US$195.62 and US$201.96 per share. You are seeing a tight band from only a couple of contributors; setting that beside regulatory overhang on Ticketmaster, venue expansion plans and Q3 earnings volatility shows why opinions can still spread widely. Explore those alternative takes before deciding how this concert giant fits your own risk and return expectations.
Explore another Live Nation Entertainment fair value estimate, including one that suggests as much as 15% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis when forming an opinion.
- A great starting point for your Live Nation Entertainment research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Live Nation Entertainment. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Live Nation Entertainment's overall financial profile at a glance.
Looking For More Investment Ideas Beyond Live Nation Entertainment?
Once you have a view on Live Nation Entertainment, it can help to widen the lens and compare it with other opportunities that suit your risk profile and income goals. The Simply Wall St Screener lets you quickly narrow the field to businesses that line up with the kind of balance sheets, valuations or income streams you prefer.
- If capital preservation sits high on your priority list, you can start by focusing on sturdier businesses and review a 31 resilient stocks with low risk scores that may better match a calmer ride through the market cycle.
- If income is the main objective, you can prioritise cash returns to shareholders and review a group of 7 dividend fortresses that could help anchor a yield focused portfolio.
- If you want to look for potential future leaders before they are widely followed, you can channel your research time into a curated 9 elite penny stocks with strong financials that combines smaller size with stronger underlying financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com