


EN
Learn Why The Bull Case For Cushman And Wakefield Stock Could Change Following Q3 Earnings Guidance
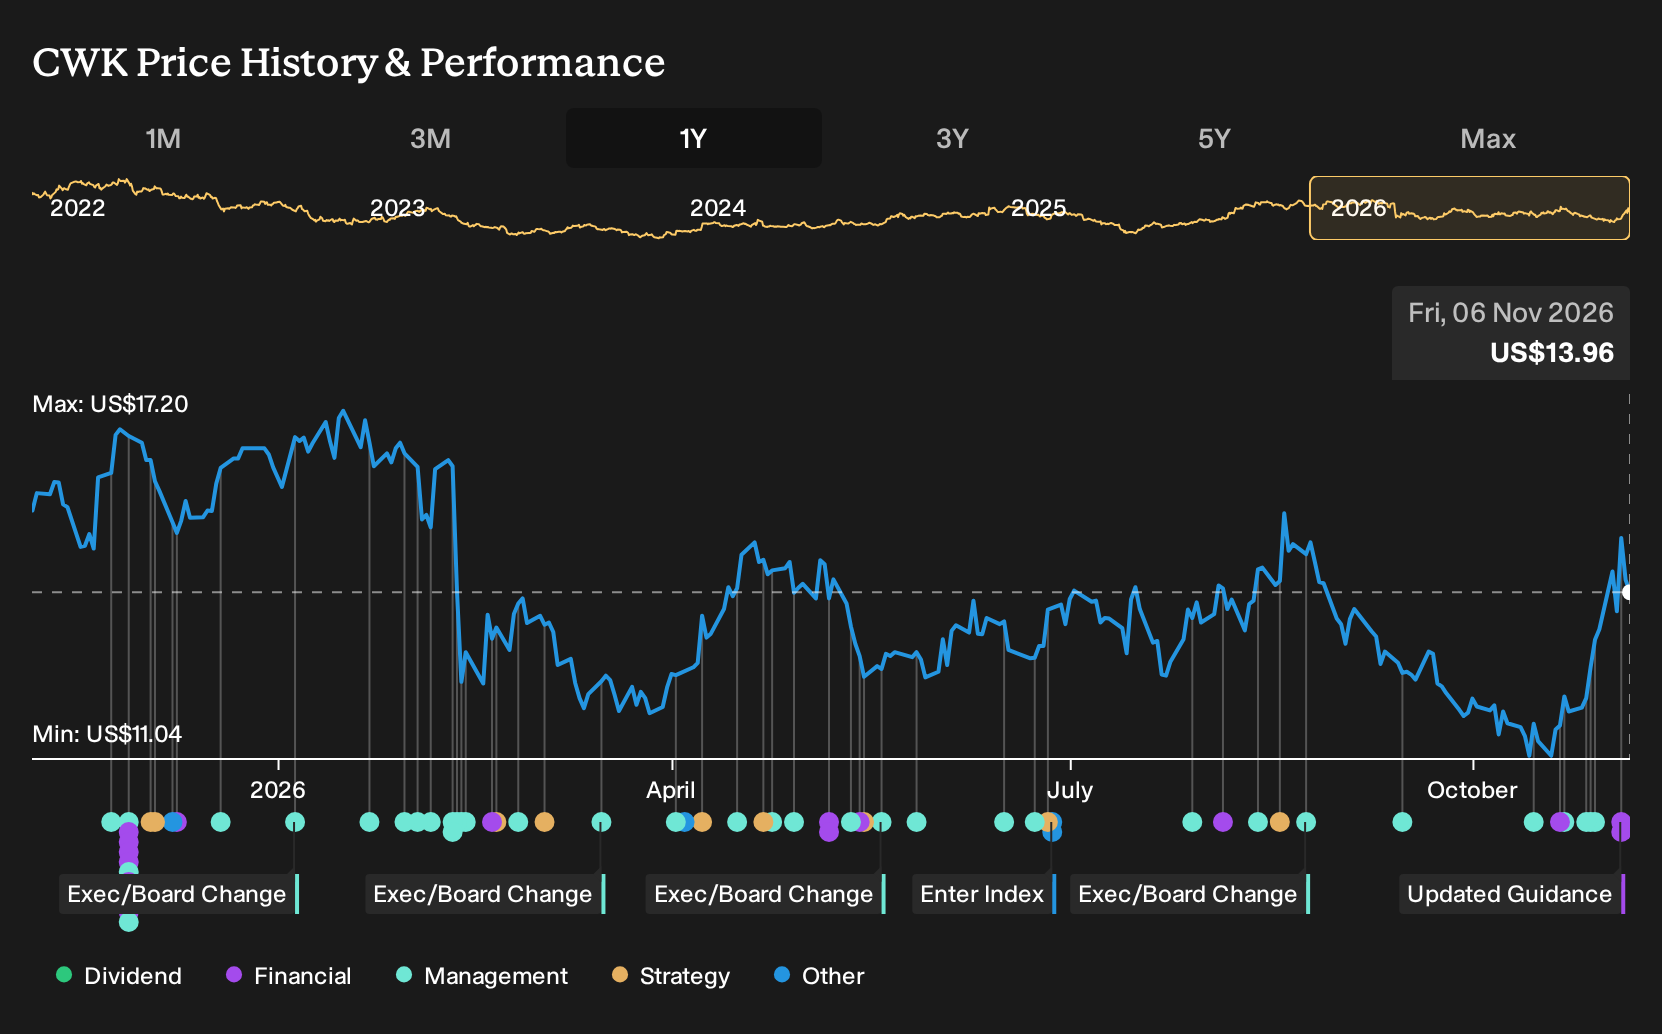
- Cushman & Wakefield reported third quarter 2026 results with sales of US$2,807.8 million and net income of US$52.1 million, and reaffirmed full year guidance for revenue growth at the mid to high end of its 6% to 8% target range.
- The mix of higher sales but lower nine month net income of US$92.2 million, compared with US$110.6 million a year earlier, highlights the pressure on profitability even as Cushman & Wakefield signals confidence in its revenue outlook.
- We will now look at how Cushman & Wakefield's reaffirmed revenue guidance and mixed profit picture could reshape the broader investment narrative.
Cushman & Wakefield Investment Narrative Recap
To own Cushman & Wakefield, you need to believe the business can keep turning solid client demand for services into steadier fees, while managing through choppy capital markets and tight margins. The reaffirmed 2026 revenue guidance in the mid to high end of the 6% to 8% range supports that top line story. The key short term swing factor is whether cost discipline and mix shift can offset pressure on profitability.
The biggest risk right now remains earnings sensitivity to slower transactional activity and higher financing costs, especially with net income for the first nine months below the prior year. The latest quarter does not radically change that risk profile. It simply underlines that decent revenue progress, by itself, may not quickly fix thin profit margins or interest cover.
The recent expansion of Cushman & Wakefield’s data center advisory platform led by Mark Bauer looks most relevant to the current guidance. Management is leaning into an area where it already reports rapid data center related revenue growth and a meaningful share of the integrated facilities management pipeline. That fits with the narrative that higher value services can support more durable fee income.
For you as a shareholder, the question is whether this build out can meaningfully rebalance earnings away from cyclical leasing and capital markets work, while still keeping capital intensity in check. Execution on complex data center leasing, development advice and portfolio work also carries operational risk. If Bauer’s team converts its long experience and relationships into recurring mandates at scale, that would directly speak to the main catalyst and help address some of the margin concerns highlighted by the latest results.
Cushman & Wakefield's narrative projects US$12.8b revenue and US$432.2 million earnings by 2029. This assumes 5.7% yearly revenue growth and an earnings increase of about US$363.1 million from US$69.1 million today.
Uncover how Cushman & Wakefield's fair value indicates a 22% potential upside to its current price. This potential could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternate view leans hard into Cushman & Wakefield’s data center and AI related exposure. Those more optimistic analysts were modelling about 8.5% annual revenue growth and roughly US$535.6 million in 2029 earnings before this guidance and Q3 report. You can read that as a far more upbeat script that may get rewritten after these results.
Explore another Cushman & Wakefield fair value estimate, including one that suggests as much as 135% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cushman & Wakefield research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Cushman & Wakefield. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cushman & Wakefield's overall financial health at a glance.
Looking for more investment ideas beyond Cushman & Wakefield?
If the Cushman & Wakefield story has you thinking about portfolio balance, use the Simply Wall St Screener to line up other stocks that match the mix of quality, resilience and income you want.
- For investors who care most about resilient balance sheets and solid fundamentals, start with this curated list of solid balance sheet and fundamentals (25 results) that can help you filter for financial strength.
- If value is your priority and you want businesses priced below what their fundamentals suggest, scan through the 38 high quality undervalued stocks to see which candidates fit your return and risk preferences.
- Income focused investors who want yield with substance rather than just a high headline number can review the 7 dividend fortresses to spot payout profiles that may better match long term goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com