


EN
Will Credit Line Extension Change New Jersey Resources (NJR) Narrative
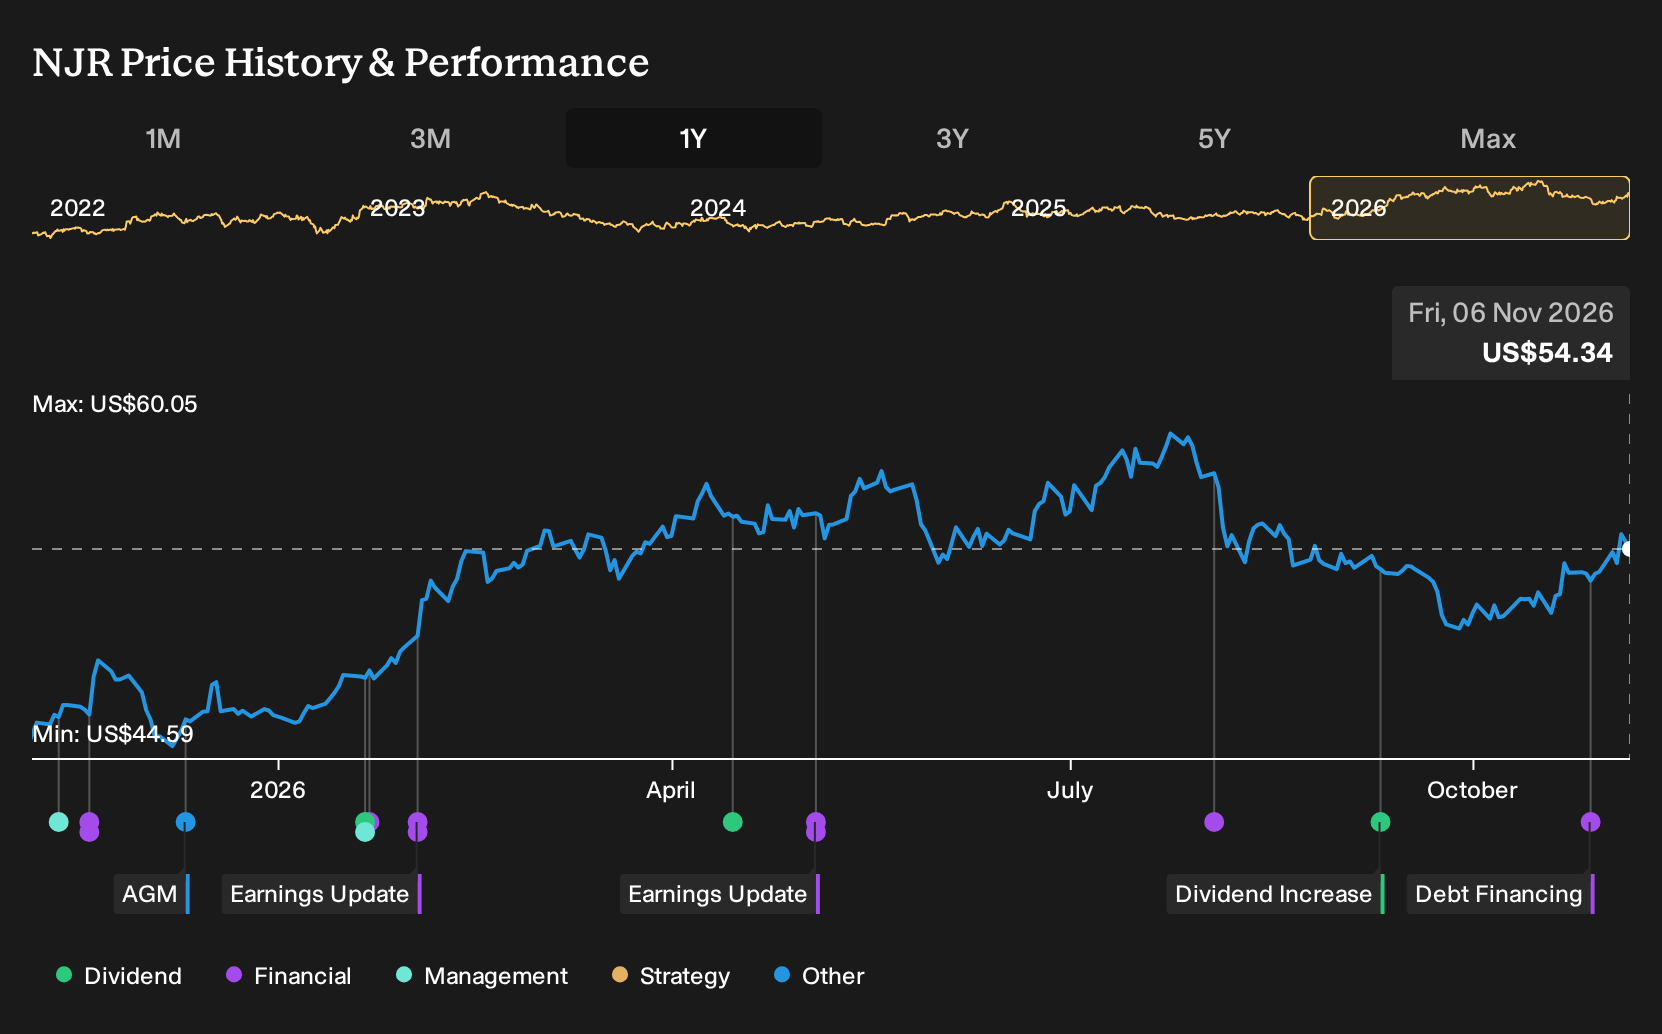
- New Jersey Resources Corporation amended its senior unsecured revolving credit facility, raising total commitments to US$650 million and extending the maturity to October 27, 2031, while New Jersey Natural Gas Company kept its US$250 million facility size and moved the maturity to the same date.
- The extended maturities and higher borrowing capacity give New Jersey Resources more room to fund its multi year capital plans and manage liquidity without immediately relying on new equity issuance.
- We will examine how New Jersey Resources' investment narrative intersects with the extended credit maturities and higher revolving capacity now in place.
Scan how New Jersey Resources’ renewed credit headroom compares with peers by reviewing the hand picked 31 resilient stocks with low risk scores benefiting from durable balance sheets and measured risk profiles.
New Jersey Resources Investment Narrative Recap
To own New Jersey Resources you need to be comfortable with a gas focused utility that is investing heavily in infrastructure, storage and solar while still relying on regulatory approval and customer demand for natural gas. The bigger picture hinges on consistent execution of the US$4.8b to US$5.2b capital plan and on those projects earning a fair return.
The recent expansion and extension of the revolving credit facilities looks incremental for the near term story. It supports funding flexibility but does not change the key near horizon catalyst, which remains regulatory decisions on cost recovery and bill impacts, or the main risk, which is pressure on cash flow coverage of debt and dividends.
The credit facility amendment is closely tied to that capital spending agenda, because New Jersey Resources is leaning on external borrowing to fund growth at New Jersey Natural Gas, Storage & Transportation and Clean Energy Ventures. More committed lending capacity and a 2031 maturity window help the business line up liquidity with multi year build schedules.
This plays directly into the catalyst around regulated investment and clean energy expansion, where execution risk is significant but supported by a seasoned management team and high quality earnings metrics. At the same time, the extension does not remove the financial watch points flagged by analysts, including debt not being well covered by operating cash flow and dividend coverage described as thin on a free cash flow basis.
How New Jersey Resources' Credit Flexibility Links To Analyst Expectations
New Jersey Resources is now backing its larger revolving credit capacity with a consensus outlook that leans on steady usage of that balance sheet flexibility rather than dramatic swings in performance. Analysts in the Simply Wall St report are assuming revenue grows by 1.7% each year over the next three years, with profit margins moving from 16.4% today to 17.3% by around 2029 as projects in gas distribution, storage and solar mature.
On earnings, the same analyst set expects New Jersey Resources to move from current earnings of US$366.2 million to a 2029 consensus of US$405.5 million, which is an increase of about 11% or US$39.3 million over that period. Some forecasts go higher, with the most optimistic at US$447.0 million, but the core scenario used in the valuation work is that US$405.5 million outcome tied to modestly higher margins and measured share count growth of 0.72% per year.
Those assumptions then feed directly into how the stock is being framed on valuation screens. The report notes that for investors to align with the current analyst narrative, they would need to be comfortable with New Jersey Resources trading at a P/E of 18.9x on those 2029 earnings, compared with a current multiple cited at 14.3x and an industry P/E for US gas utilities of 15.8x. That future multiple sits above the sector reference point, which means the thesis leans heavily on earnings quality and visibility from regulated and contracted projects.
New Jersey Resources' narrative projects US$2.3b revenue and US$405.5 million earnings by 2029. This assumes 1.7% yearly revenue growth and an earnings increase of about US$39.3 million from US$366.2 million today.
Analysts have translated this profile into a consensus price target of US$59.86 per share, compared with a recent share price of US$51.59, with individual targets spanning from US$53.00 to US$63.00. Forecasts in the Simply Wall St summary also reference a P/E of 18.9x on the US$405.5 million earnings estimate and apply a discount rate of about 7.2% to reach today’s fair value range, which gives readers a clear sense of the hurdle rates being used behind the scenes.
Uncover why New Jersey Resources' fair value indicates a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide band, from about US$13.07 at the low end to nearly US$59.86 at the top, underscoring how far opinions on New Jersey Resources can stretch. With fresh credit capacity in place and long term gas policy risk still unresolved, you may wish to explore these contrasting viewpoints before setting your own stance.
Explore another New Jersey Resources fair value estimate, including one that suggests as much as 76% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your New Jersey Resources research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for New Jersey Resources. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate New Jersey Resources' overall financial health at a glance.
Looking for more New Jersey Resources style investment ideas?
If New Jersey Resources has you thinking about where else solid fundamentals, income potential and risk management intersect, the Simply Wall St Screener can help you cast a wider net without losing focus on quality.
- For investors who care most about resilience, start with a 31 resilient stocks with low risk scores that aim to keep drawdown risk in check while still offering room for long term compounding.
- If dividend income is your anchor, scan a curated set of 7 dividend fortresses that put cash returns to shareholders at the center of their appeal.
- When you want to pair quality with a potential mispricing, look through a 38 high quality undervalued stocks that combine fundamentals with a valuation profile that might not yet be fully appreciated.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com