


EN
What Stryker (SYK)'s Goodwill Impairment Means For Shareholders
- Stryker reported third quarter 2026 sales of US$6,520 million and net income of US$753 million, alongside a US$293 million goodwill impairment, while nine month results showed higher sales and earnings compared with the prior year period.
- The combination of higher revenue, lower quarterly earnings per share, and a sizeable non cash goodwill charge highlights the earnings quality and balance sheet trade offs that investors need to weigh in Stryker.
- We will now examine how Stryker's investment narrative could be influenced by the earnings mix shift created by the recent goodwill impairment.
Compare how Stryker's balance sheet movements stack up against other medical names facing similar capital and earnings trade offs using the curated list of solid balance sheet and fundamentals (25 results) in this space.
Stryker Investment Narrative Recap
Stryker appeals to investors who believe its mix of orthopaedics, MedSurg and neurotechnology can support steady procedure demand and a recurring equipment and service base. The recent quarter showed higher sales and nine month earnings, but lower quarterly EPS and a goodwill impairment complicate the short term picture. Execution in peripheral vascular manufacturing and joint replacement demand looks key.
The most important near term catalyst still sits in operational clean up and margin work, particularly around peripheral vascular recovery and broader use of Mako systems. The biggest risk remains extended manufacturing disruption and legal overhang, which could keep pressure on profitability even if top line trends hold up.
The universal shelf registration filed on 4 November 2026 matters because it gives Stryker flexibility to issue common or preferred stock, debt, warrants or other securities. That kind of funding menu can support acquisitions, capital spending or refinancing plans, but it also keeps equity and leverage questions in focus for you as a shareholder.
Alongside the recent goodwill impairment, this shelf facility sharpens the spotlight on capital allocation, especially with existing comments about Stryker having a high level of debt and primarily higher risk funding. Any future issuance or refinancing that comes off this shelf could influence how the margin program, portfolio expansion and hospital capital demand translate into actual earnings power.
Stryker's narrative projects US$32.9b revenue and US$7.7b earnings by 2029. This aligns with analyst assumptions of 7.7% yearly revenue growth and implies an earnings increase of about US$4.1b from US$3.6b today.
Uncover why Stryker's fair value indicates an 8% potential upside to its current price that could narrow quickly.
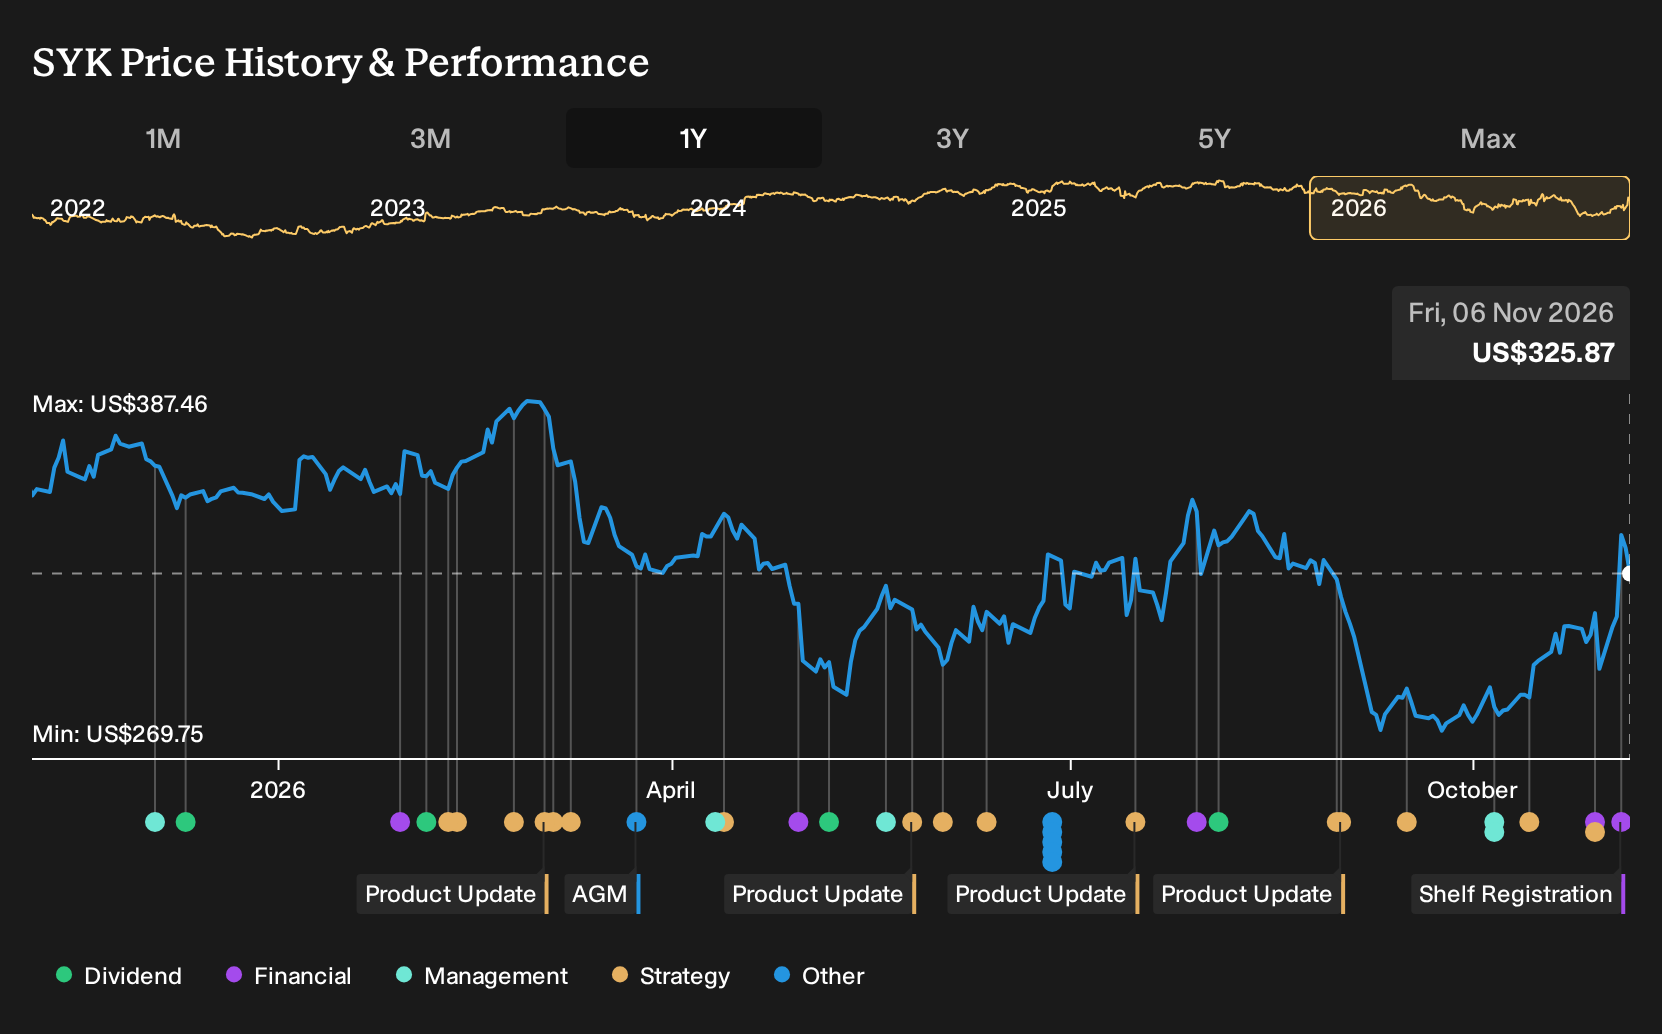
Exploring Other Perspectives
One alternate view says the real swing factor is slower hip and knee procedures rather than the new shelf or goodwill hit. The most cautious analysts were already only pencilling in about US$31.8b of 2029 revenue and US$6.5b of earnings, so this fresh news could push their Stryker story even further from the consensus path.
Explore 5 other Stryker fair value estimates, including one that suggests it could be worth just $311.21.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Stryker research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Stryker. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Stryker's overall financial health at a glance.
Looking For More Investment Ideas Beyond Stryker?
Once the Stryker story feels clear, it can help to widen your watchlist and compare it with other companies that match the kind of balance sheet strength, income profile, or under the radar potential you are aiming for.
- If capital preservation is near the top of your list, start with a basket of companies that score well on resilience using our 31 resilient stocks with low risk scores.
- If you prefer cash income alongside potential capital gains, scan for businesses with stronger yield support through the 7 dividend fortresses.
- If you want to get in early on under followed opportunities, look through the 19 high quality undiscovered gems, which pair quality fundamentals with less crowded ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com