


EN
Easterly Government Properties (DEA) Updates Guidance On A Valuation Narrative Still Under Review
Easterly Government Properties (DEA) has drawn fresh attention after updating its net income guidance for 2026 and 2027, pairing that outlook with recently reported third quarter and year to date earnings.
The new guidance lands after a mixed year for Easterly Government Properties holders, with a 5.49% year to date share price gain but a much weaker 5 year total shareholder return of 38.24% decline, pointing to longer term fatigue. Recent earnings and the updated 2026 and 2027 net income ranges appear to have steadied sentiment, with a 13.60% total shareholder return over the past 12 months hinting that investors are reassessing both income potential and perceived risk at the current US$22.48 share price.
Compare Easterly Government Properties' latest guidance with other income-focused real estate plays by scanning our hand picked 7 dividend fortresses for potential alternatives in the same yield-focused corner of the market.
Easterly Government Properties now sits at an awkward crossroads where firmer earnings guidance meets a share price still shaped by years of fatigue. Is this latest move about business progress or sentiment finally thawing, and what does that mean for valuation next?
Most Popular Narrative: 11% Undervalued
Easterly Government Properties is trading at $22.48 against a most followed fair value estimate of $25.36, so the current quote sits at a discount that the narrative links directly to its project pipeline and capital plan. That gap hinges on whether management can turn identified developments and lending into steady income without overloading the balance sheet.
The main thing that has to go right is that Easterly Government Properties executes on its capital plan by reducing leverage toward its stated targets while converting its development and mezzanine opportunities into durable income without eroding balance sheet resilience.
See why 12 investors see Easterly Government Properties as 11% undervalued.
Result: Fair Value of $25.36 (UNDERVALUED)
Still, Easterly Government Properties carries a high 7.3x net debt to EBITDA load and a dividend payout that could pressure funding if growth in core FFO slows.
Find out about the key risks to this Easterly Government Properties narrative.
Another View: Easterly Government Properties Looks Expensive On Earnings
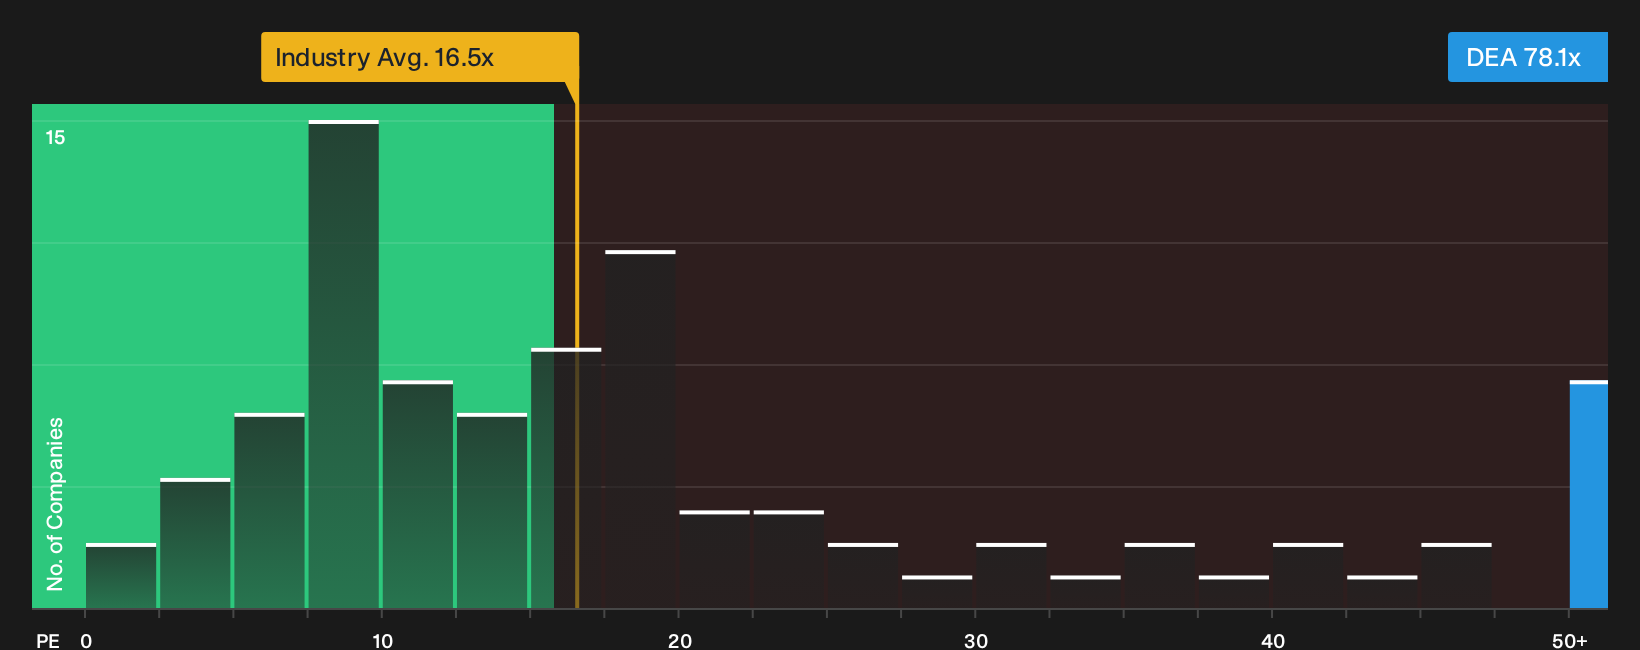
The DCF work suggests Easterly Government Properties is trading at a large discount to an estimated future cash flow value of $46.21, which points to an undervalued setup on that model. The P/E picture tells a very different story, with a 78.1x multiple versus a 35.1x fair ratio, US Office REITs at 16.5x and peers at 58.4x. That kind of gap increases the risk that even small disappointments in earnings or sentiment could hit the share price hard before any long term cash flow thesis plays out.
Look into how the numbers line up by reviewing See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of optimism and caution around Easterly Government Properties feels familiar, do not sit on the fence. Go through the numbers, weigh the trade off between its income story and balance sheet pressure, and then ground your view with the 2 key rewards and 2 important warning signs.
Looking for more Easterly Government Properties sized income ideas?
Do not stop your research with Easterly Government Properties. Broaden your watchlist using a few focused screens that surface different types of opportunities other investors might miss.
- Target resilient payouts by scanning income focused candidates that screen well for yield in the 7 dividend fortresses.
- Hunt for quality at a discount by reviewing companies that appear mispriced on fundamentals in the 38 high quality undervalued stocks.
- Zero in on sturdier balance sheets by filtering for financially robust businesses using the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com