


EN
Italgas (BIT:IG) Posts Fresh Earnings, Is A 15% Undervalued View Still Fair?
What Italgas’ Latest Earnings Tell You
Italgas (BIT:IG) has just posted third quarter and nine month earnings to 30 September 2026, giving investors fresh numbers on sales, revenue mix, and profit resilience.
Italgas’ latest figures arrive after a strong run in recent weeks, with a 30 day share price return of 11.76% and a 90 day gain of 3.64%, even though the year to date share price return is down 5.67% and the current price sits at €9.122.
That near term momentum, together with a 1 year total shareholder return of 2.73% and very large 3 and 5 year total shareholder returns, suggests investors have been weighing the fresh earnings alongside a longer history of value creation rather than reacting only to this quarter’s headline numbers.
Scan how Italgas compares with other regulated utilities and infrastructure players that combine cash generation with perceived upside in our hand-picked list of 226 high quality undervalued stocks.
Italgas looks like a solid regulated utility with long roots and steady earnings, and the recent share price rebound sharpens the real issue: Are you paying a fair price for that stability today?
Most Popular Narrative: 15.2% Undervalued
On the most followed narrative, Italgas screens as around 15% below an estimated fair value of €10.75, compared with the latest close at €9.12. The current price is being judged against a story that leans on long term infrastructure and policy support rather than short term trading swings.
The structural role of gas networks in a cost constrained, security focused European energy mix, with electricity prices remaining a multiple of gas and rising AI driven power demand, supports sustained utilization of Italgas grids and underpins long term revenue visibility and RAB growth.
The multi decade shift from fossil gas to biomethane, hydrogen and synthetic methane, backed by REPowerEU and rapidly expanding biomethane projects and reverse flow investments, positions Italgas as a key enabler of renewable molecules. This supports higher allowed returns on incremental green CapEx and medium term earnings growth.
See why 6 investors see Italgas as 15% undervalued.
Result: Fair Value of €10.75 (UNDERVALUED)
Still, if Italgas delivers its planned €16.5b investment program and squeezes further efficiencies from 2i Rete Gas, today’s undervaluation narrative could appear conservative by comparison.
Find out about the key risks to this Italgas narrative.
Another View on Italgas’ Valuation
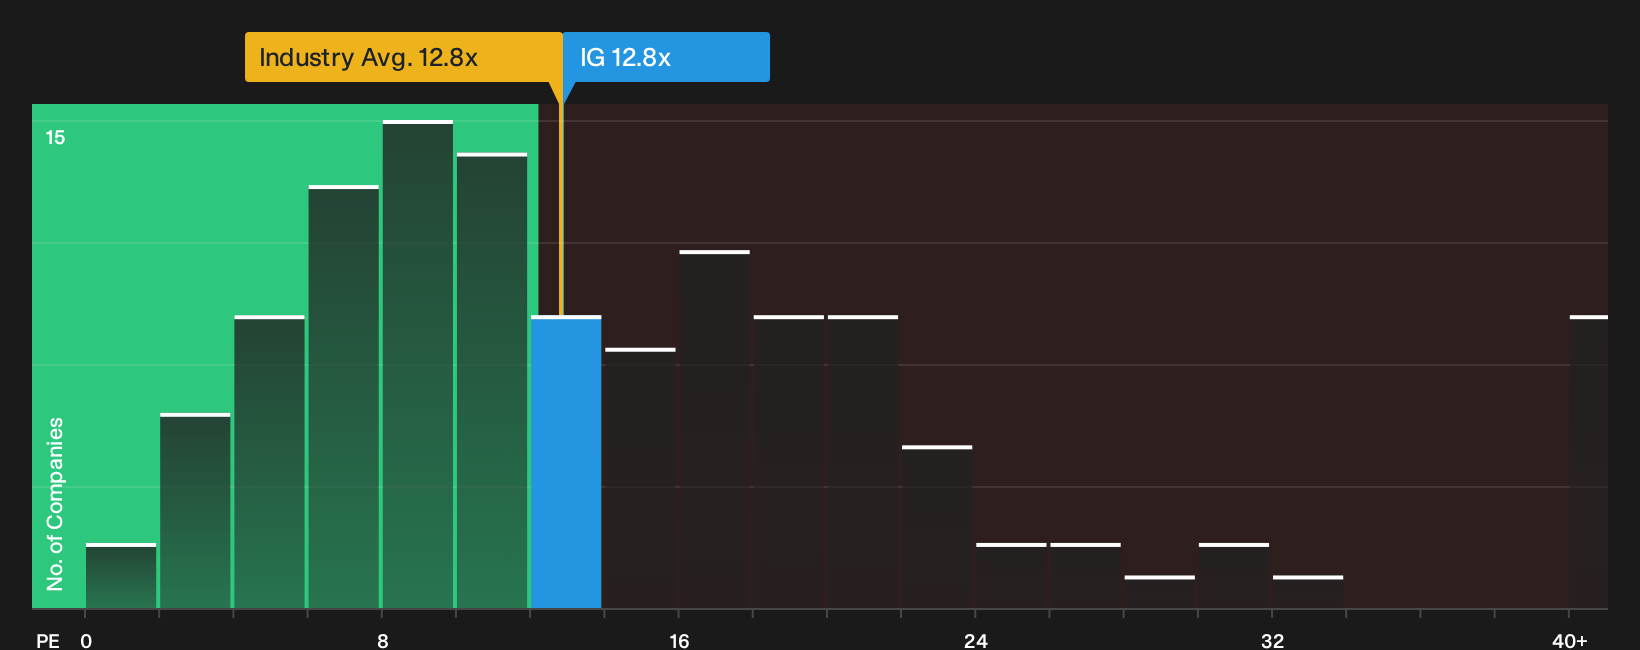
The DCF driven fair value story around €10.75 presents Italgas as about 15% undervalued. A different lens tells a cooler story. At €9.12, the stock trades on a P/E of 12.8x, which is exactly in line with the global gas utilities group at 12.8x and sits well below the estimated fair ratio of 17.2x. That gap points to potential upside in the multiple over time, but it also suggests the market is not clearly mispricing this business today. Which version of “fair” do you place more weight on when real money is on the line?
For investors weighing how much to lean on this earnings based cross check versus cash flow models, See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Italgas for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 226 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Italgas is mixed, with clear risks on one side and genuine upside on the other. Check the data for yourself and decide where you stand based on 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Italgas?
If you only stop at Italgas, you risk missing other opportunities that might better match your goals, risk limits, and income needs.
- Target punchy potential by scanning 126 elite penny stocks with strong financials that combine smaller size with solid financial footing.
- Zero in on value by reviewing a focused 573 high quality undiscovered gems list that filters for quality and strong fundamentals.
- Dial down volatility by checking a curated 208 resilient stocks with low risk scores set of businesses screened for more resilient profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com