


EN
Trane Technologies (TT) Looks Repriced Following Strong Results And Higher 2026 Guidance
Guidance upgrade and strong quarter put Trane Technologies in focus
Trane Technologies (TT) moved into the spotlight after raising full year 2026 earnings guidance, pairing that outlook with third quarter results that showed higher sales and net income compared with a year earlier.
Recent trading tells two different stories. The share price is up 2.38% on the day to US$401.76, yet the 30 day share price return is down 15.77%. Over the longer stretch, total shareholder return declined 6.67% over one year but is up 83.61% over three years and 121.78% over five years. This suggests Trane Technologies is coming off a strong multi year run even as short term sentiment cools and investors reassess the raised 2026 guidance and latest earnings beat.
Compare Trane Technologies with a curated list of industrial peers that also show strong fundamentals and multi year return potential using our list of solid balance sheet and fundamentals (25 results).
Bulls see Trane Technologies as a temporary casualty of profit taking after upgraded guidance and stronger quarterly numbers. Bears argue the long run-up still leaves the stock stretched. Which case does the valuation support next?
Most Popular Narrative: 24% Undervalued
On the most followed narrative, Trane Technologies screens as undervalued, with an estimated fair value of $526.67 versus the latest close at $401.76. That gap rests on specific assumptions about backlog conversion, earnings quality and how long current demand holds up.
The focus on energy efficiency and the ability to deliver attractive paybacks for customers is now reinforced by services reaching roughly one-third of revenue with a low-teens growth rate since 2020 and digital solutions deployed across more than 70,000 connected buildings, which together can support recurring revenue and margin expansion.
See why 41 investors see Trane Technologies as 24% undervalued.
Result: Fair Value of $526.67 (UNDERVALUED)
Still, the bullish Trane Technologies story leans heavily on that US$12.1b Commercial HVAC backlog, as well as on pricing keeping up with cost and regional mix pressures.
Find out about the key risks to this Trane Technologies narrative.
Another View: What Trane Technologies’ P/E Is Telling You
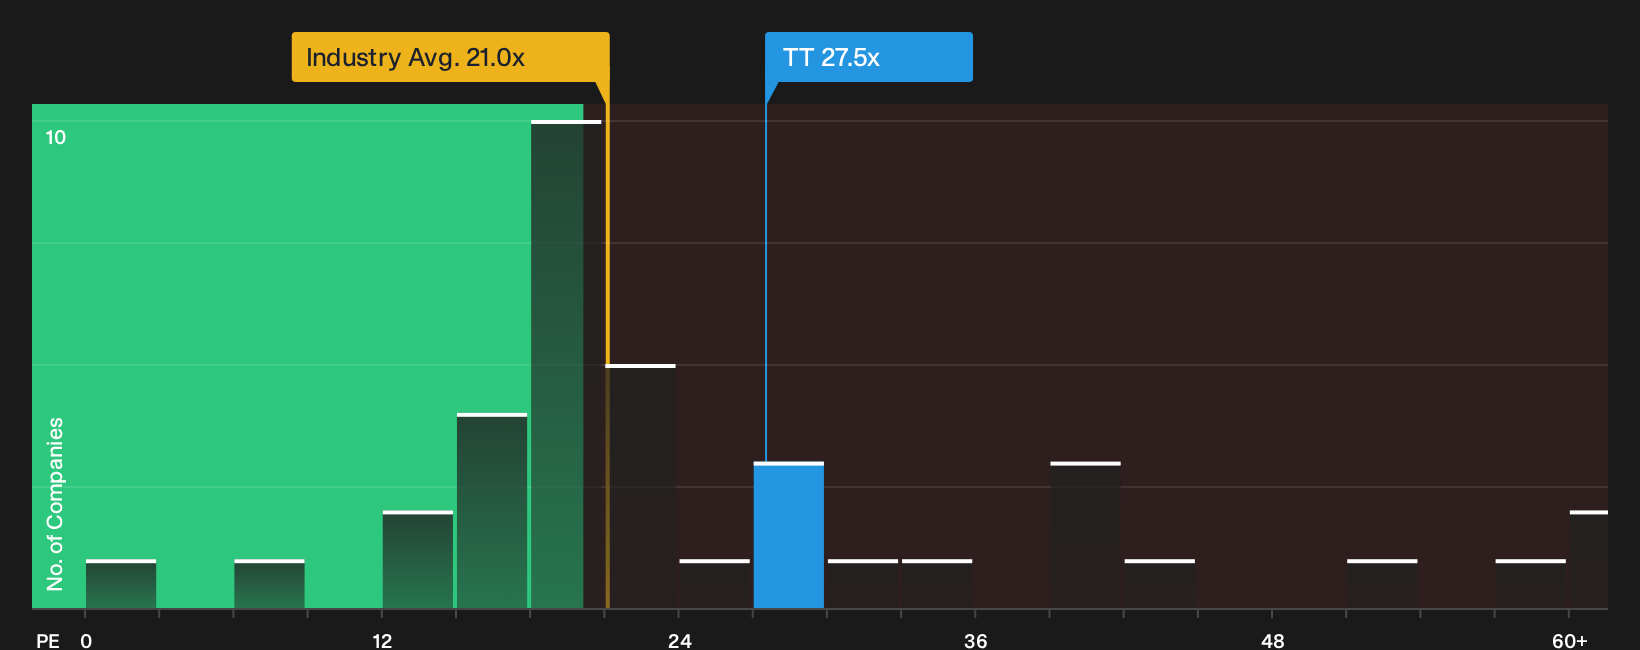
On a cash flow lens Trane Technologies looks undervalued, yet the earnings multiple paints a tighter picture. The stock trades on a P/E of 27.5x, above both the US Building industry on 21x and peers at 22x, and only slightly below a fair ratio of 29.9x that the market could move toward. That mix points to some valuation risk if sentiment cools, but also some potential upside if earnings continue to align with the more optimistic narrative. Which signal do you put more weight on when you consider your own margin of safety?
For a closer look at how this earnings multiple compares with peers and that fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Trane Technologies debate feels finely balanced, treat that as your prompt to move quickly: review the underlying data and form your own stance. To see what optimistic investors are focusing on, start with 4 key rewards.
Looking for more investment ideas beyond Trane Technologies?
Trane Technologies may sit at the center of your watchlist today, but your next strong idea often comes from widening the net with a targeted screener.
Use the Simply Wall St Screener to surface fresh opportunities that match specific goals before they slip onto everyone else's radar.
- Target potential mispricings by scanning companies that combine quality fundamentals with appealing valuations through the 38 high quality undervalued stocks.
- Build a steadier base for your portfolio by reviewing businesses that score well on balance sheet strength using the list of solid balance sheet and fundamentals (25 results).
- Hunt for off-the-radar opportunities by sorting through financially sound smaller stocks via the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com