


EN
Pacira BioSciences (PCRX) After Earnings Surprise Is The Stock Already Fully Valued
Pacira BioSciences earnings jolt investor focus
Pacira BioSciences (PCRX) just posted third quarter results that paired a slight dip in revenue with a sharp jump in profitability, giving investors fresh numbers to reassess the pain management specialist.
At a share price of US$36.43, Pacira BioSciences has logged a 90 day share price return of 49.12% and a year to date share price gain of 48.94%. The 1 year total shareholder return of 65.22% suggests recent momentum has started to rebuild after weaker 5 year total shareholder returns.
Scan beyond Pacira BioSciences and compare this earnings driven move with hand picked 38 high quality undervalued stocks that show strong fundamentals and warrant further scrutiny.
Bulls view Pacira BioSciences as a profitable non opioid pain specialist trading at a steep intrinsic discount. Bears, on the other hand, point to modest sales growth and mixed long term returns. Which story does the valuation actually support next?
Most Popular Narrative: 9% Overvalued
On Simply Wall St's most followed narrative, Pacira BioSciences screens as modestly overvalued, with a fair value of $33.57 against the latest close at $36.43. This leaves the story hinging on how much of its long term plan is already reflected in the price.
The main thing that has to go right is sustained EXPAREL and ZILRETTA execution, including continued uptake in outpatient surgery, effective use of the expanded patent estate, and progress on PCRX-201 and PCRX-2002 through the next clinical milestones.
Advancement of PCRX-201 and PCRX-2002, backed by published Phase 1 data and an ongoing Phase 2 ASCEND study with Part B enrollment underway, introduces potential new high-prevalence musculoskeletal indications that can diversify revenue and support longer term earnings.
See why 11 investors see Pacira BioSciences as 9% overvalued.
Result: Fair Value of $33.57 (OVERVALUED)
Still, Pacira BioSciences leans heavily on EXPAREL and reimbursement support, and any setback in PCRX-201 or PCRX-2002 trials could quickly weaken that upbeat narrative.
Find out about the key risks to this Pacira BioSciences narrative.
Another View on Pacira BioSciences valuation
The analyst narrative sees Pacira BioSciences as about 9% overvalued at $36.43 versus a fair value of $33.57. A different lens, the SWS DCF model, points in the opposite direction, suggesting the shares trade around 71% below an estimated future cash flow value of $124.67. Which signal do you put more weight on?
Look into how the SWS DCF model arrives at its fair value.
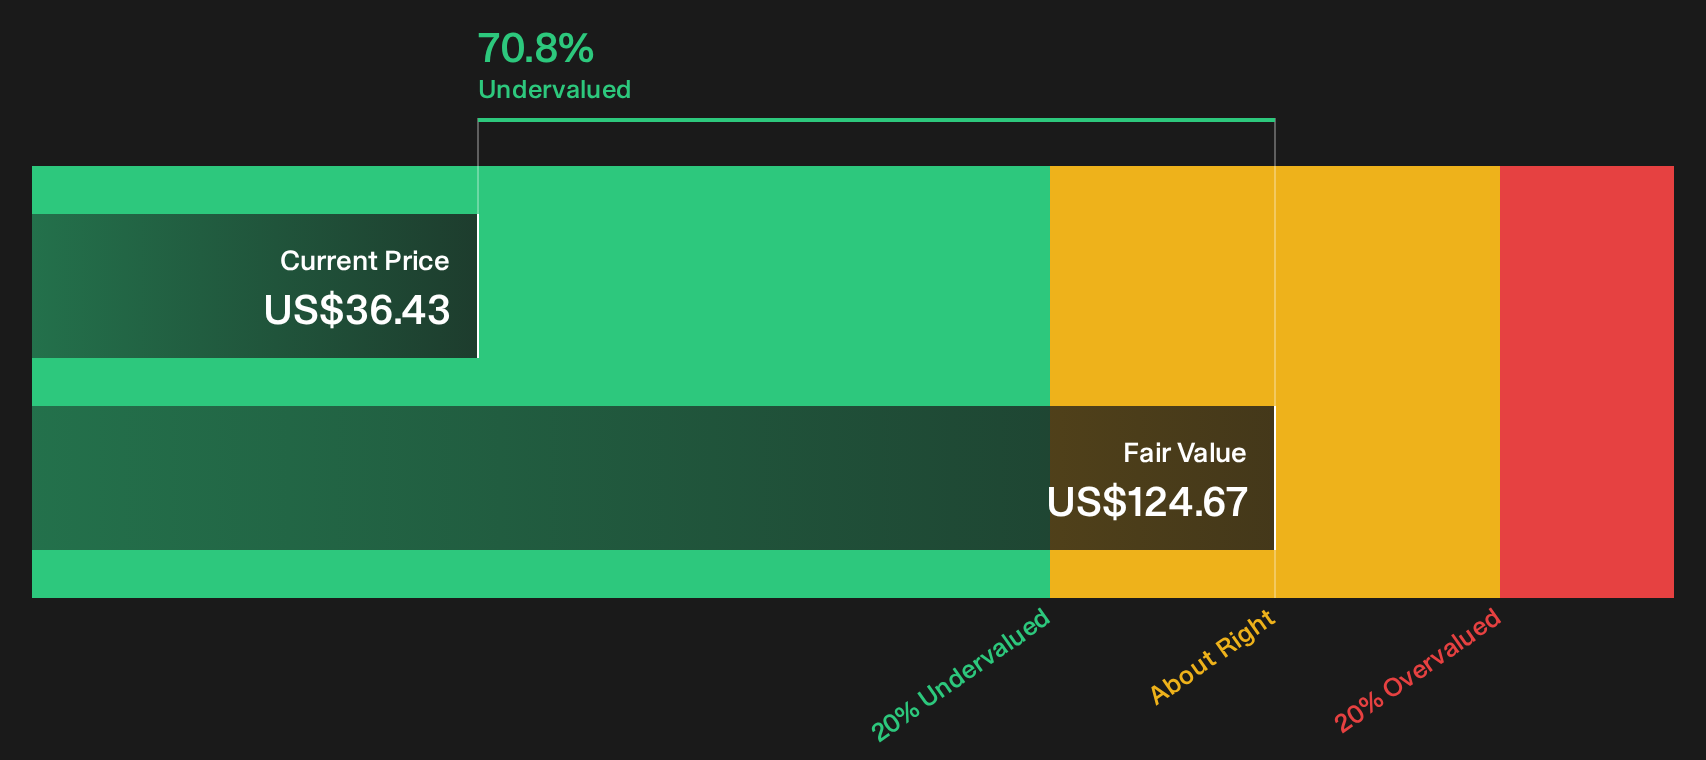
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Pacira BioSciences for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 38 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the Pacira BioSciences story, arriving just as fresh earnings reset expectations, often reward investors who pressure test the numbers themselves and move early. To see both sides of that debate in one place, go through the 3 key rewards and 3 important warning signs.
Looking for more Pacira BioSciences sized ideas?
If Pacira BioSciences has sharpened your appetite for opportunity, do not stop here. Broaden your watchlist and let fresh ideas challenge your current portfolio.
- Target steadier compounding by screening for resilient companies with strong finances using the 31 resilient stocks with low risk scores.
- Hunt for quality at a potential discount through the 19 high quality undiscovered gems before the wider market starts paying closer attention.
- Focus on financial strength and funding flexibility with a list of solid balance sheet and fundamentals (25 results) that can help you stress test your next idea.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com