


EN
Earnings Guidance Cut Might Change The Case For Investing In Zoetis (ZTS)
- Zoetis reported third quarter 2026 results with sales of US$2,391 million and net income of US$591 million, with earnings per share from continuing operations at US$1.44, and also provided nine month figures alongside updated full year guidance.
- The full year 2026 outlook now points to a slightly higher revenue range but a trimmed diluted EPS range, highlighting pressure on profitability even as underlying demand and product volumes support overall revenue expectations.
- The focus now turns to how Zoetis' tighter full year earnings guidance could reshape the broader investment narrative around its animal health portfolio.
Scan how Zoetis' latest guidance compares with peers by checking out our curated list of 31 resilient stocks with low risk scores that aim to balance earnings resilience with steadier risk profiles.
Zoetis Investment Narrative Recap
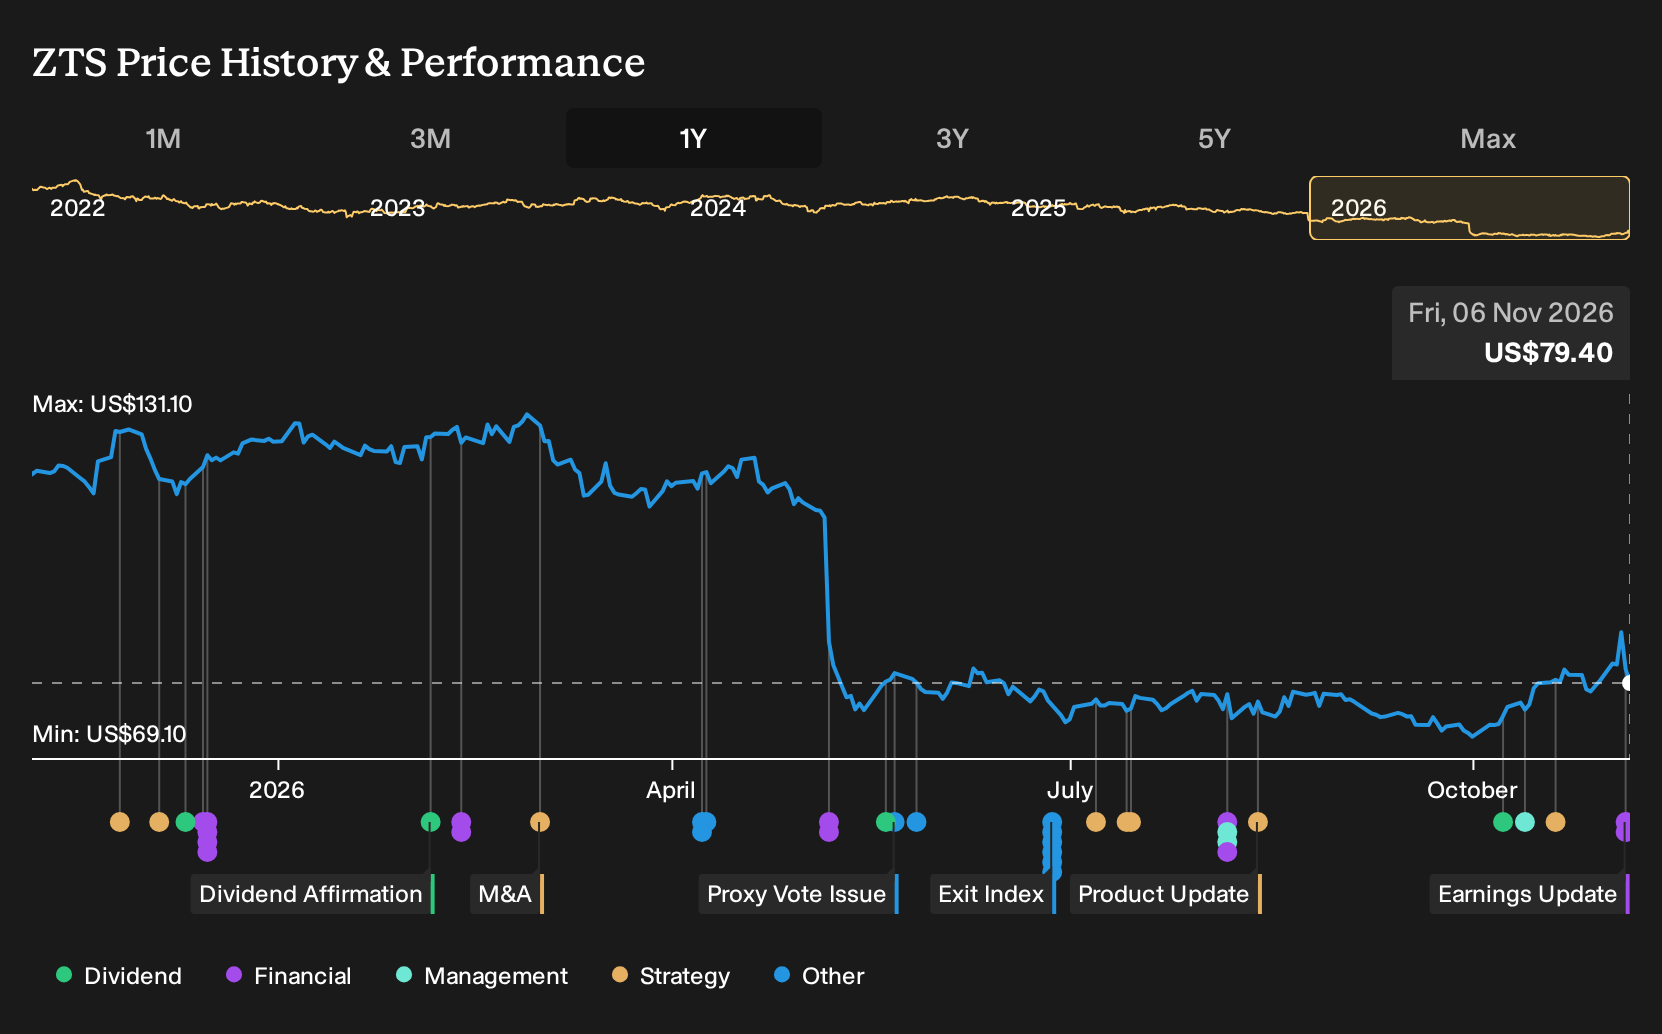
To own Zoetis, you need to believe the animal health demand story is intact while the firm works through near term pricing and competitive pressure. The third quarter showed softer sales and lower earnings per share than a year ago, and the slightly trimmed full year EPS guidance reinforces that margin pressure is real rather than theoretical.
The key near term catalyst remains execution on the existing portfolio as rebates and promotions ramp, plus how quickly companion animal trends stabilise. The biggest risk stays the same. Heavier discounting in parasiticides and dermatology could erode price and share further, and the latest guidance tightening does not materially change that risk profile.
The updated full year outlook on 5 November 2026 is the announcement that matters most here. Revenue guidance was edged higher within a narrowed range of US$9,220 million to US$9,320 million, yet diluted EPS was guided slightly lower to US$5.50 to US$5.60. That mix indicates growth is currently more volume and rebate driven than margin led.
For you as a shareholder, the question is whether Zoetis can rely on its R&D pipeline, diagnostics and international exposure to offset ongoing pressure in mature franchises. Execution on that broader platform is the operational swing factor. If competition in core categories intensifies further, the gap between resilient sales and compressed earnings could widen.
Zoetis' narrative projects US$9.8b revenue and US$2.7b earnings by 2029, which implies 1.1% yearly revenue growth and a US$0.1b earnings increase from the current US$2.6b level.
Uncover how Zoetis' fair value indicates an 11% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Some of the lowest ranked Zoetis analysts focus on a different catalyst. They worry the renal and osteoarthritis pipeline will not fully replace softer companion animal trends. Before this earnings update, the most cautious group was modeling revenue of about US$9.2b and earnings near US$2.3b by 2029, so their narrative already built in much slower progress. Those expectations pre date the new guidance, so treat them as one possible path and compare several viewpoints before deciding where you sit.
Explore 10 other Zoetis fair value estimates, including one that suggests as much as 7% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Zoetis research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Zoetis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zoetis' overall financial health at a glance.
Looking for more Zoetis style investment ideas?
If Zoetis has you thinking more broadly about risk, income and long term compounding, use the Simply Wall St Screener to line up other companies that fit the kind of portfolio you want to build.
- For investors who care most about capital preservation and steadier performance, start with a 31 resilient stocks with low risk scores that score well on resilience and business quality.
- If you want potential mispricing opportunities, scan a curated 38 high quality undervalued stocks where fundamentals and price appear out of sync.
- For those who prefer a pay cheque from their holdings, focus on a 7 dividend fortresses that combine higher yields with a focus on strength and sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com