


EN
Will Earnings Strength Change Mohawk Industries Stock Narrative
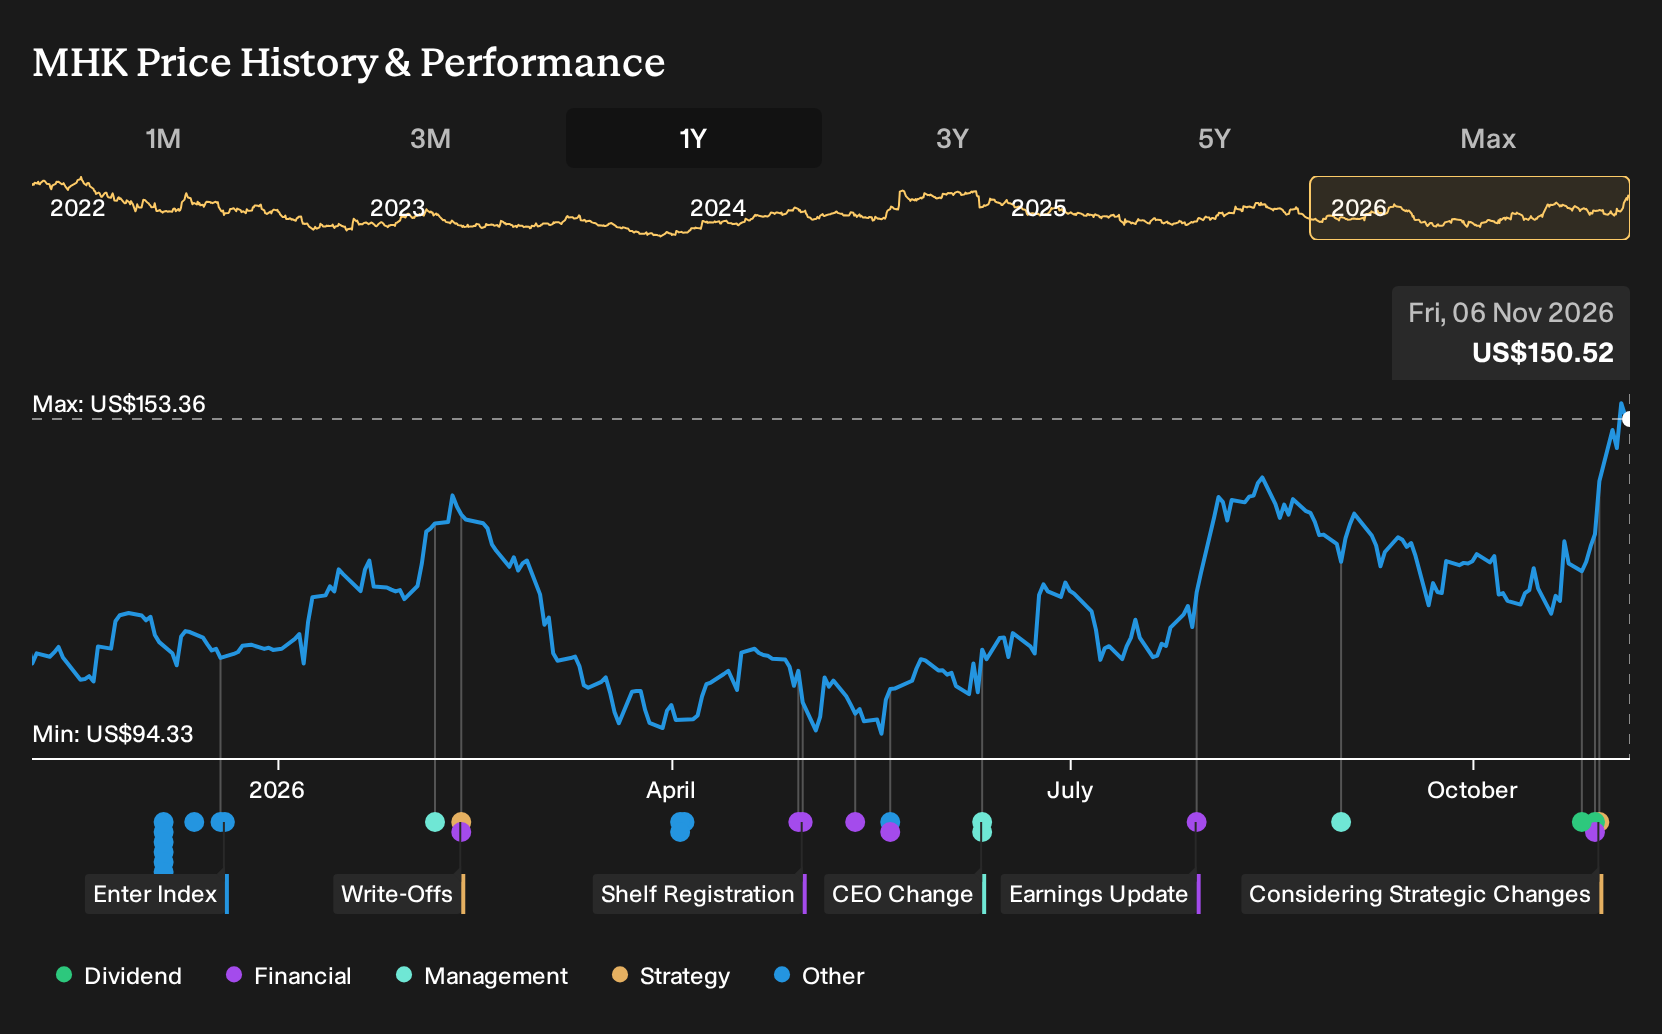
- Mohawk Industries reported third quarter 2026 sales of US$2,786 million and net income of US$163.1 million, alongside a completed US$500 million share repurchase and a review of all business units to assess market position and cash profitability.
- The broad portfolio review, which may lead to fixing, repositioning or selling weaker assets, points to management focusing closely on business quality, cost structure and long term margin potential rather than only near term earnings headlines.
- We will now assess how Mohawk Industries' reported earnings and full scale business review could reshape the investment narrative investors rely on.
Mohawk Industries Investment Narrative Recap
For an investor to stay with Mohawk Industries, the belief has to be that a cyclical flooring market can still support steady earnings through cost control, pricing discipline, and product mix. The broad business review and recent quarter suggest management is concentrating on cash profitability and margins rather than just chasing volume.
The key short term catalyst remains execution on restructuring and productivity projects that are expected to deliver sizeable cost savings over the next few years. The main risk still sits with flooring demand. Extended weakness in residential remodeling or new construction could blunt the benefit of these internal efforts.
The most relevant update here is the full review of every Mohawk Industries business unit, with options to fix, reposition, or exit underperforming pieces. That kind of clean up can change how investors think about the earnings base, especially when paired with ongoing cost initiatives already targeted to deliver hundreds of millions in savings through 2027.
This ties into potential catalysts in a straightforward way. A tighter portfolio plus restructuring could support margins if flooring volumes eventually stabilize. Any divestments might simplify the group but also remove some revenue. At the same time, execution risk is significant. If weaker assets continue to weigh on results, or if restructuring benefits are realized more slowly than planned, the current earnings profile could remain under pressure.
Mohawk Industries' current analyst narrative points to forecast revenue of US$11.9b and earnings of US$656.4 million by 2029. That profile rests on 2.1% yearly revenue growth and a US$138 million earnings increase from the US$518.4 million earnings level cited for today.
Uncover why Mohawk Industries' fair value indicates Mohawk Industries is roughly in line with its current price.
Exploring Other Perspectives
One alternate view for Mohawk Industries leans heavily on execution risk. Those analysts worry that the US$480 million 2026 investment plan and new plants could struggle to ramp, so their low case assumed revenue of about US$11.6b and earnings near US$710.8 million by 2029. That is a more cautious story than consensus. Both sets of forecasts were built before this business review and buyback update, so treat them as starting points and explore how your own expectations might shift after the latest news.
Explore 2 other Mohawk Industries fair value estimates, including one that suggests it could be worth just $149.13.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Mohawk Industries research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Mohawk Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mohawk Industries' overall financial health at a glance.
Looking For More Ideas Beyond Mohawk Industries?
Once you have a view on Mohawk Industries, it can help to widen your watchlist with other companies that match the kind of risk, return and balance sheet profile you prefer. The Simply Wall St Screener offers a few quick ways to do that without getting buried in tickers.
- For investors who want stronger balance sheets and sturdier fundamentals at the core of their portfolio, start with this list of solid balance sheet and fundamentals (25 results) to find candidates that may better match your comfort level.
- If you are hunting for potential bargains with quality traits, use the 38 high quality undervalued stocks to surface ideas that combine financial strength with pricing that may look appealing.
- For readers who care most about stability and capital protection, the 31 resilient stocks with low risk scores can help highlight businesses with lower risk scores that might suit a more cautious approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com