


EN
Viper Energy (VNOM) Lifts Dividend And Guidance, Is The Stock Still Cheap?
Viper Energy (VNOM) just posted third quarter 2026 results that showed higher revenue and net income compared with a loss a year earlier, along with updated production guidance and a raised cash dividend.
The latest earnings release and dividend decision landed after a choppy stretch for Viper Energy, with a 7 day share price return that declined 14.81% and a 30 day share price return down 5.51%, even as the 1 year total shareholder return reached 14.56%. Recent guidance on production and the higher base dividend arrive against that backdrop. The market reaction around the current US$40.62 share price suggests investors are reassessing both the growth profile and income appeal of the stock relative to where it traded earlier in the year.
Scan how Viper Energy compares with other income plays and cash-generative operators using our curated list of 7 dividend fortresses.
After that earnings rebound and a richer dividend, Viper Energy now trades below some valuation estimates and above where it started the year. Is most of the upside already captured, or does the current price still leave room?
Most Popular Narrative: 27% Undervalued
Viper Energy closed at $40.62, while a widely followed narrative anchored around a fair value of $56 suggests a meaningful valuation gap that leans heavily on what the mineral estate could earn over time rather than just the next few quarters.
Viper is not merely a stream of today's royalty checks. It is ownership of a large Permian mineral estate through which thousands of existing wells already produce, thousands more are being developed or contemplated, and future operators can continue turning buried geology into royalty income largely with somebody else's capital.
See why 32 investors see Viper Energy as 27% undervalued.
Result: Fair Value of $56 (UNDERVALUED)
Still, the Viper Energy narrative could be pressured if operator drilling slows materially or if future related party deals raise fresh governance questions.
Find out about the key risks to this Viper Energy narrative.
Another View: Viper Energy Looks Expensive On Earnings
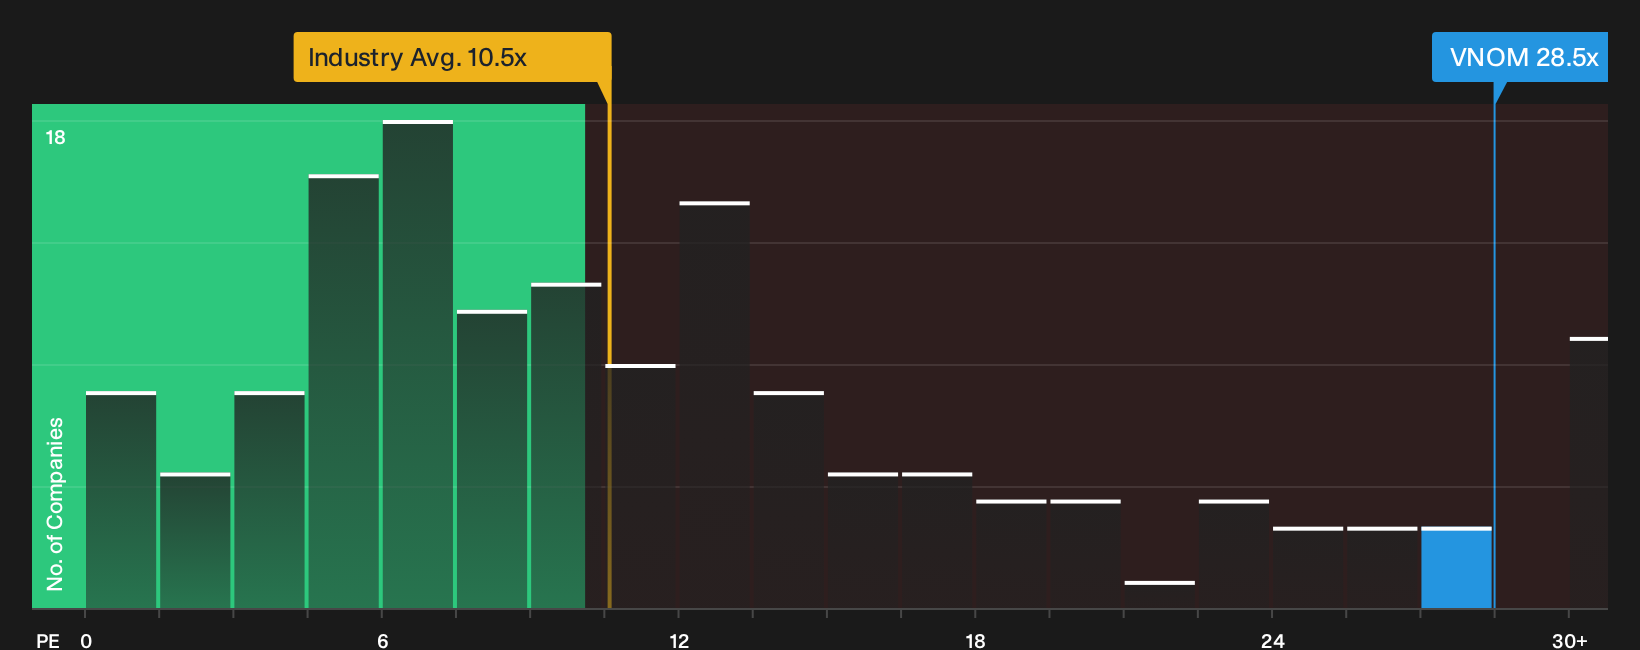
Viper Energy screens as undervalued on future cash flows, yet its current P/E of 28.5x sits far above the US Oil and Gas industry at 10.3x and a peer average of 9.7x. It also trades richer than an estimated fair ratio of 20.9x. Is the market already paying upfront for years of mineral upside?
That richer P/E profile means any disappointment in earnings or drilling activity could hit the share price harder than lower rated royalty peers, even if the mineral estate story proves broadly right over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Viper Energy is clearly mixed, with income appeal on one side and valuation questions on the other, so move quickly, look through the numbers yourself, and weigh both the upside narrative and the issues that could bite. To round out that view, make sure you read through the 4 key rewards and 3 important warning signs
Looking for more investment ideas beyond Viper Energy?
You have seen how quickly sentiment can shift around Viper Energy. Do not stop here. Broaden your watchlist now before the next move leaves you trailing.
- Target potential mispricings by scanning a curated pool of companies that screen as strong value opportunities using our 38 high quality undervalued stocks.
- Prioritise resilience and capital preservation by focusing on businesses that pass strict financial health filters through the list of solid balance sheet and fundamentals (25 results).
- Hunt for lesser known opportunities with strong fundamentals that are flying under most radars using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com